
The concept of an “unrealized gain tax” sits at the fascinating intersection of finance, public policy, and the economic forces driving innovation. While not a universally applied levy on all appreciating assets, its discussion and occasional application in specific contexts highlight profound implications, particularly for high-growth, innovation-driven sectors like drone technology. At its core, an unrealized gain refers to the increase in an asset’s value that has not yet been converted into cash through a sale. A tax on this phantom profit would mean that investors, founders, and employees holding equity in innovative drone companies could owe taxes on the rising paper value of their holdings, even if they haven’t sold a single share. This hypothetical tax presents a complex challenge to how capital is formed, allocated, and how cutting-edge technologies, from AI-powered autonomous drones to advanced remote sensing platforms, are financed and brought to market.
Defining Unrealized Gains in the Tech & Innovation Landscape
Understanding unrealized gains is critical for anyone involved in the dynamic world of drone technology, from venture capitalists funding a new aerial robotics startup to engineers receiving stock options. An unrealized gain represents the accrued appreciation of an asset’s value from its purchase price to its current market value, prior to its disposition.
The Core Concept Applied to Emerging Technologies
In the realm of tech and innovation, especially within the rapidly expanding drone industry, unrealized gains are a pervasive phenomenon. Consider a startup developing groundbreaking AI algorithms for autonomous drone navigation, or a company perfecting next-generation sensors for remote sensing applications. Early investors, founders, and employees often receive equity in these companies at a low valuation. As the technology matures, gains market traction, and the company demonstrates potential, its valuation—and thus the value of that equity—can skyrocket. These are unrealized gains: significant paper profits that reflect the market’s anticipation of future success, but which are not yet liquid cash. The promise of sophisticated features like AI follow mode, enhanced obstacle avoidance, or advanced mapping capabilities directly translates into this upward valuation, creating substantial unrealized wealth for stakeholders.
Distinguishing Unrealized from Realized Gains
The fundamental distinction between unrealized and realized gains lies in the act of sale. A realized gain occurs when an asset, such as shares in a successful drone manufacturing firm or a stake in a company specializing in FPV racing drone technology, is sold for a price higher than its original cost basis. At this point, the profit becomes tangible cash, and it typically triggers a taxable event under existing capital gains tax regimes. Conversely, an unrealized gain exists purely on paper. The asset has appreciated, but it remains in the hands of the owner. For instance, if an investor bought shares in a company developing innovative drone battery technology at $10 and they are now trading at $100, that $90 per share profit is an unrealized gain until the shares are sold. This distinction is particularly vital for the tech sector, where much of the wealth is often illiquid, tied up in company equity that cannot be easily converted to cash without potentially impacting company control or market perception.
The Hypothetical Impact of an Unrealized Gain Tax on Drone Tech Innovation
The imposition of a tax on unrealized gains, particularly on assets like equity in technology companies, could introduce profound shifts in capital markets and the innovation ecosystem. Such a policy would not merely represent a new revenue stream for governments but could fundamentally alter the risk-reward calculus for inventors, investors, and entrepreneurs in the drone industry.
Capital Allocation and Investment Incentives
A tax on unrealized gains would directly impact the fundamental incentives driving investment in nascent and high-growth drone technologies. Venture capitalists and angel investors typically pour capital into early-stage drone startups developing advanced flight technology, new sensor arrays, or sophisticated AI for autonomous operations. These investments are inherently high-risk, long-term ventures, often taking years to yield a return, if at all. The promise of substantial, tax-deferred capital appreciation upon a successful exit (IPO or acquisition) is a key motivator. If investors faced annual taxes on the paper gains of their illiquid holdings, it could significantly diminish the attractiveness of these long-horizon, high-risk endeavors. Capital might flow instead towards lower-risk, more liquid assets, starving innovative drone tech companies of crucial funding needed for R&D, product development, and scaling.
Startup Funding and Growth Trajectories
The lifeblood of innovation in drone technology—from micro drones to large-scale UAVs for remote sensing—is the ability for startups to secure patient capital to fund their ambitious visions. Many pioneering drone tech companies, whether focused on advanced navigation systems or creating immersive FPV experiences, operate for years without turning a profit, reinvesting heavily in research and development. An unrealized gain tax could force early investors or founders to liquidate portions of their equity prematurely to cover tax obligations. This forced selling could disrupt capital structures, dilute ownership stakes, or even trigger liquidity events that are not strategically optimal for the company’s long-term growth. Instead of focusing solely on innovation and market penetration, these companies would face added pressure to generate cash flow or seek earlier exits, potentially stifling groundbreaking advancements that require extended development cycles.

Employee Compensation and Talent Retention
Talent is the ultimate competitive advantage in the tech sector, and the drone industry is no exception. Companies developing cutting-edge autonomous flight systems, sophisticated mapping solutions, or robust anti-collision technology rely on attracting top engineers, data scientists, and robotics experts. Stock options and Restricted Stock Units (RSUs) are critical components of compensation packages, allowing employees to share in the potential success of the enterprise. These equity grants often represent significant unrealized gains for employees as the company’s valuation climbs. If employees were subject to an annual tax on the unrealized gains from their unvested or unsold stock, it would substantially reduce the appeal of working for high-growth drone startups. This could make it harder for innovative firms to compete for talent against more established companies or those in industries less affected by such a tax, leading to a “brain drain” from the very companies driving the future of aerial robotics and related applications.
Valuation Challenges in Rapidly Evolving Tech Sectors
One of the most complex practical hurdles in implementing an unrealized gain tax, especially within the tech and innovation space, lies in the inherent difficulty of accurately valuing assets that are rapidly evolving, often illiquid, and whose future potential is largely speculative.
Assessing Intellectual Property and Future Potential
How does one precisely value a proprietary algorithm for drone swarm intelligence, a patented design for a new type of propulsion system, or groundbreaking software for advanced remote sensing on an annual basis for tax purposes? Unlike mature, publicly traded companies with stable revenue streams, many drone tech innovators derive their value from intellectual property (IP) and the future potential of their disruptive technologies. Valuing IP is notoriously complex, relying on projections, market adoption rates, and competitive landscapes that can shift dramatically year to year. For private companies, where there’s no liquid market to set a daily price, valuation becomes an even more subjective exercise, typically requiring costly and time-consuming appraisals. Imposing a tax on a valuation that is inherently speculative and subject to rapid change could lead to significant inequities and administrative burdens for both taxpayers and tax authorities.
Market Volatility and Valuation Fluctuations
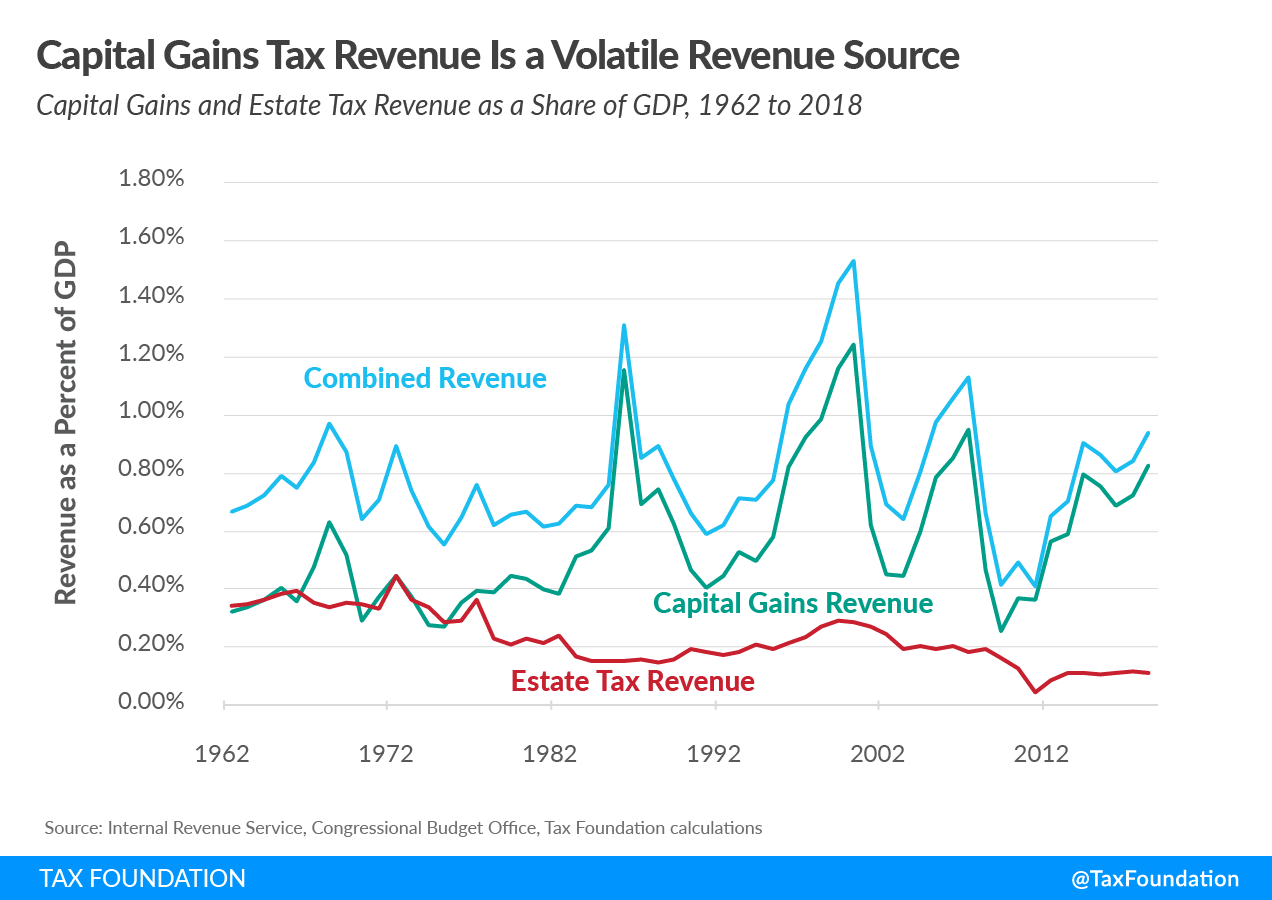
The stock market, particularly for companies in high-growth tech sectors like drones, is characterized by significant volatility. A drone company pioneering urban air mobility solutions might see its valuation surge on news of a successful test flight, only to dip sharply due to regulatory concerns or a shift in investor sentiment. Taxing “gains” that could easily evaporate before they are realized raises fundamental questions about fairness and practicality. An investor or founder could pay tax on an unrealized gain in one year, only for the asset’s value to decline the following year, leaving them with a tax bill on a profit that never materialized. This “taxation without realization” could create severe liquidity crises for individuals whose wealth is predominantly tied up in the shares of the innovative companies they founded or invested in, especially those focusing on capital-intensive development like drone hardware or complex AI systems.
Broader Economic Implications for the Drone Industry Ecosystem
Beyond individual investors and companies, an unrealized gain tax could ripple through the entire economic ecosystem supporting drone innovation, affecting the flow of capital, the pace of technological advancement, and the competitiveness of the sector on a global stage.
Impact on Venture Capital and Private Equity
Venture Capital (VC) and Private Equity (PE) firms are the primary engines fueling the growth of innovative drone technologies, from sophisticated aerial mapping solutions to revolutionary cargo delivery drones. These funds typically invest with a long-term horizon, accepting significant risks for the prospect of outsized returns. An unrealized gain tax would fundamentally alter the economic model for these crucial investors. If a VC fund invests in a drone AI startup, and its portfolio companies see significant paper gains, taxing these gains annually would reduce the effective return on investment. This reduction in expected returns could make long-term, high-risk investments less attractive, potentially shrinking the pool of available capital for groundbreaking projects. The drone industry, with its extensive R&D requirements and lengthy development cycles for technologies like autonomous flight and advanced sensor integration, is particularly reliant on patient, risk-tolerant capital, which an unrealized gain tax could diminish.

Potential for Innovation Stagnation or Acceleration
The ultimate consequence of an unrealized gain tax on the drone industry and broader tech innovation is a subject of intense debate. Proponents might argue it could “unlock” capital by encouraging faster realization of gains, which could then be reinvested. However, the more prevalent concern is that such a tax would likely lead to innovation stagnation. By penalizing long-term holdings and introducing liquidity pressures, it could disincentivize the patient capital formation essential for developing deep tech. Technologies such as next-generation drone propulsion, secure communication systems for UAVs, or new materials for lighter, more durable airframes require sustained investment over many years before they can yield commercial returns. An unrealized gain tax could create an environment where the incentive is to pursue short-term gains rather than revolutionary, long-term advancements. This could slow the pace of technological development, hinder the global competitiveness of drone tech companies, and ultimately limit the transformative potential of aerial robotics in various applications, from remote sensing and infrastructure inspection to autonomous logistics and beyond.