
The landscape of commerce in the digital age, particularly within the rapidly evolving sectors of technology and innovation, is profoundly shaped by various economic factors, not least among them, state sales tax rates. For businesses and consumers involved with cutting-edge technologies like drones, advanced sensors, AI-driven systems, and intricate mapping solutions, understanding the prevailing tax environment is crucial. In New Jersey, a state striving to foster a robust tech ecosystem, the sales tax rate directly influences operational costs, investment decisions, and ultimately, the accessibility and affordability of innovative products and services.
The Foundation: Understanding New Jersey’s Sales Tax Framework
New Jersey levies a state sales tax on the sale of tangible personal property and certain services within its borders. This tax is a significant component of the state’s revenue generation and applies broadly across most retail transactions. For entities engaged in the development, manufacturing, or sale of advanced technology, understanding the specifics of this framework is paramount, as it directly impacts financial planning and market competitiveness.
Current Standard Rate
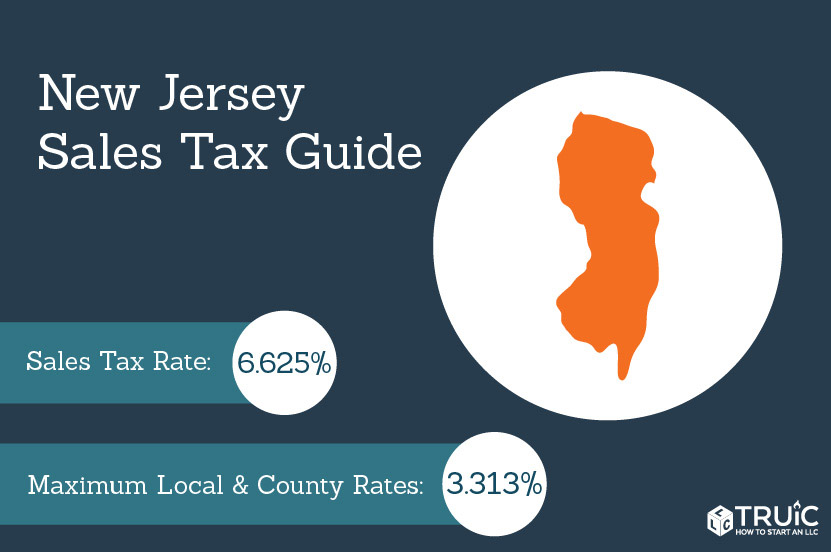
As of the current period, the standard New Jersey sales tax rate stands at 6.625%. This rate applies to the vast majority of taxable transactions. While seemingly a straightforward percentage, its application within the complex world of technology, which often involves a mix of physical components, software, digital services, and intellectual property, necessitates a closer examination. Businesses involved in the burgeoning drone industry, for example, from manufacturers of quadcopters and FPV systems to retailers of micro drones and racing drones, must account for this rate in their pricing strategies and inventory management. Similarly, consumers acquiring new flight technology, sophisticated cameras, or various drone accessories like advanced batteries and controllers, will see this tax applied to their purchases, impacting the overall cost of engaging with these innovative fields.
Scope of Taxable Goods and Services
New Jersey’s sales tax is generally imposed on the retail sale of tangible personal property. This broad definition encompasses the physical hardware central to the drone and advanced tech industries. Drones themselves, including their airframes, motors, and integrated systems, fall under this category. Likewise, specialized components such as navigation units, stabilization systems, GPS modules, various sensors (thermal, optical, LiDAR), and obstacle avoidance systems are typically subject to the sales tax when sold separately or as part of a complete unit.
Beyond physical goods, the scope of taxable services in New Jersey is also critical for the tech sector. While many services are exempt, specific enumerated services are taxable. For instance, charges for installing, maintaining, or repairing tangible personal property often fall within the taxable scope. This has direct implications for companies providing support for complex drone systems, FPV setups, or sophisticated camera gimbals. Furthermore, the burgeoning field of aerial filmmaking relies on specialized equipment and services. If these services involve the transfer of tangible property or specific taxable services, they too would be subject to the 6.625% rate. The nuanced interpretation of “tangible personal property” versus “intangible services” can be particularly complex when dealing with software, data processing, or cloud-based solutions, which are foundational to modern flight technology, AI-driven drone operations, and remote sensing applications.
Impact on the Tech & Innovation Ecosystem in New Jersey
The New Jersey sales tax rate isn’t just a number; it’s a dynamic factor that influences economic activity across the tech and innovation spectrum. Its application affects purchasing power, investment decisions, and the overall business environment for companies pioneering advancements in areas such as autonomous flight, advanced mapping, and remote sensing.
Cost Implications for Tech Businesses and Consumers
For businesses operating within New Jersey’s tech and innovation sector, the 6.625% sales tax rate translates into direct cost implications. Companies purchasing raw materials, manufacturing equipment for drone production, advanced computing infrastructure for AI development, or specialized sensors for R&D purposes must factor this tax into their capital expenditures. While some purchases may qualify for exemptions (e.g., for manufacturing equipment used directly in production), the general principle is that the tax adds to the cost of doing business. This can potentially influence decisions on where to establish or expand operations, especially for startups with tight budgets.
For consumers, the sales tax directly increases the price of cutting-edge technology. Whether it’s the latest 4K gimbal camera for aerial filmmaking, a new racing drone, or a sophisticated GPS module for enhanced navigation, the final price tag will incorporate the 6.625% sales tax. This can subtly impact consumer adoption rates, particularly for higher-priced items or emerging technologies where price sensitivity might be a factor. A higher overall cost could, in some instances, lead consumers to seek out sellers in states with lower or no sales tax, impacting local New Jersey retailers specializing in drone technology or advanced imaging equipment.
Taxation of Software and Digital Products
One of the most complex areas of sales tax application within the tech and innovation space is the treatment of software and digital products. Given that much of modern tech innovation relies heavily on software (e.g., drone flight control software, AI algorithms for autonomous flight, data processing for mapping, FPV systems’ digital interfaces), how these are taxed is critical.
In New Jersey, the sale of “canned” or prewritten software is generally subject to sales tax, whether delivered on a tangible medium (like a disc) or electronically. This includes operating systems, flight control software for drones, video editing software for aerial filmmaking, and analytical tools used in remote sensing. However, custom software development, where software is created specifically for a client, is often considered a service and may be exempt from sales tax, provided it remains a service and no tangible personal property is transferred. This distinction is vital for tech firms offering bespoke solutions for industrial drones, specialized mapping services, or AI-driven analytical platforms. Furthermore, the taxation of digital goods and cloud-based services (Software-as-a-Service, Platform-as-a-Service), which are central to many modern tech applications, presents ongoing challenges and evolving interpretations in tax policy, requiring vigilance from businesses relying on or providing such solutions.
Sales Tax and Drone/UAV Components
The modular nature of many drone systems and flight technology components means that businesses and enthusiasts frequently purchase individual parts for assembly, upgrades, or repairs. From high-performance motors and propellers for racing drones to advanced sensors and microcontrollers for custom UAV builds, these components are typically subject to the 6.625% sales tax. This also extends to essential drone accessories like batteries, remote controllers, and specialized cases.
For manufacturers of drones or flight technology, purchasing these components as part of their production process might qualify for specific exemptions, such as a resale exemption (if the component is incorporated into a product that will be resold) or a manufacturing equipment exemption. However, the intricacies of these exemptions necessitate careful compliance and record-keeping. The imposition of sales tax on individual components can aggregate, influencing the total cost of assembling or maintaining advanced drone fleets, thereby affecting the operational budgets of businesses utilizing drones for mapping, inspection, or delivery services.
Sales Tax, Innovation Incentives, and Economic Development
Beyond the immediate cost implications, New Jersey’s sales tax framework plays a role in the broader economic development strategy, particularly in how it might influence the attraction and retention of tech companies and foster innovation. Tax policy can act as both a hurdle and, when strategically crafted, an incentive.
R&D Exemptions and Their Limitations
Many states offer specific tax exemptions or credits to encourage research and development (R&D) activities, recognizing their critical role in driving innovation and economic growth. New Jersey does provide an R&D tax credit against corporate business tax, but direct sales tax exemptions for R&D equipment and supplies can be more limited and specific. While purchases of certain manufacturing machinery and equipment may be exempt, the broader spectrum of tools and materials used in pure R&D for AI, autonomous flight, or new sensor technologies might still incur sales tax. This means tech companies investing heavily in prototyping new drone designs, experimenting with novel flight algorithms, or developing advanced obstacle avoidance systems may still see their R&D expenditures increase due to sales tax on non-exempt purchases. A more comprehensive sales tax exemption for R&D inputs could further incentivize groundbreaking work within the state.
How Tax Policy Influences Tech Startups
For nascent tech startups, which often operate on lean budgets and require significant capital for development and scaling, every percentage point of tax matters. The 6.625% sales tax on equipment, software licenses, and even some services can add a noticeable burden. This might influence a startup’s decision on where to incorporate or establish their primary operations. States with more favorable tax structures or specific incentives for new technology businesses might appear more attractive. New Jersey’s efforts to foster a vibrant startup scene, especially in areas like drone technology and AI, must consider how the sales tax interacts with other incentives, such as angel investor tax credits or innovation zones, to create a truly competitive environment. The cumulative effect of sales tax on initial investments can be a significant hurdle for founders trying to get their innovative products to market.
Attracting and Retaining Tech Talent and Companies
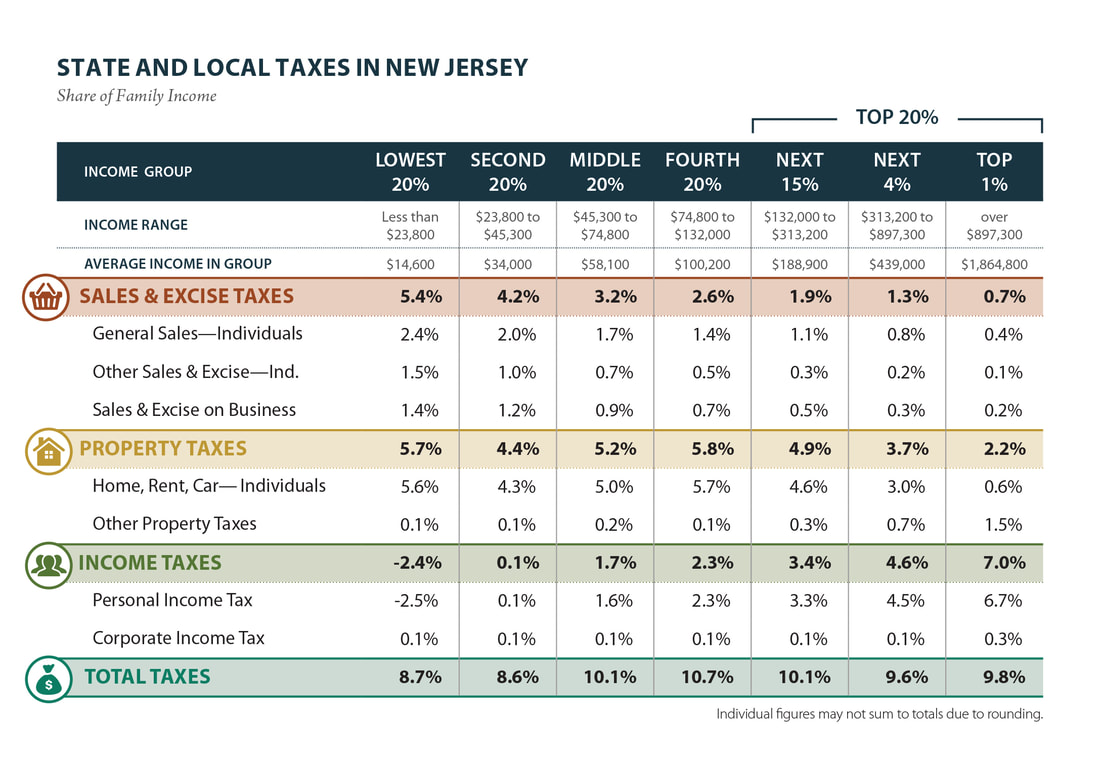
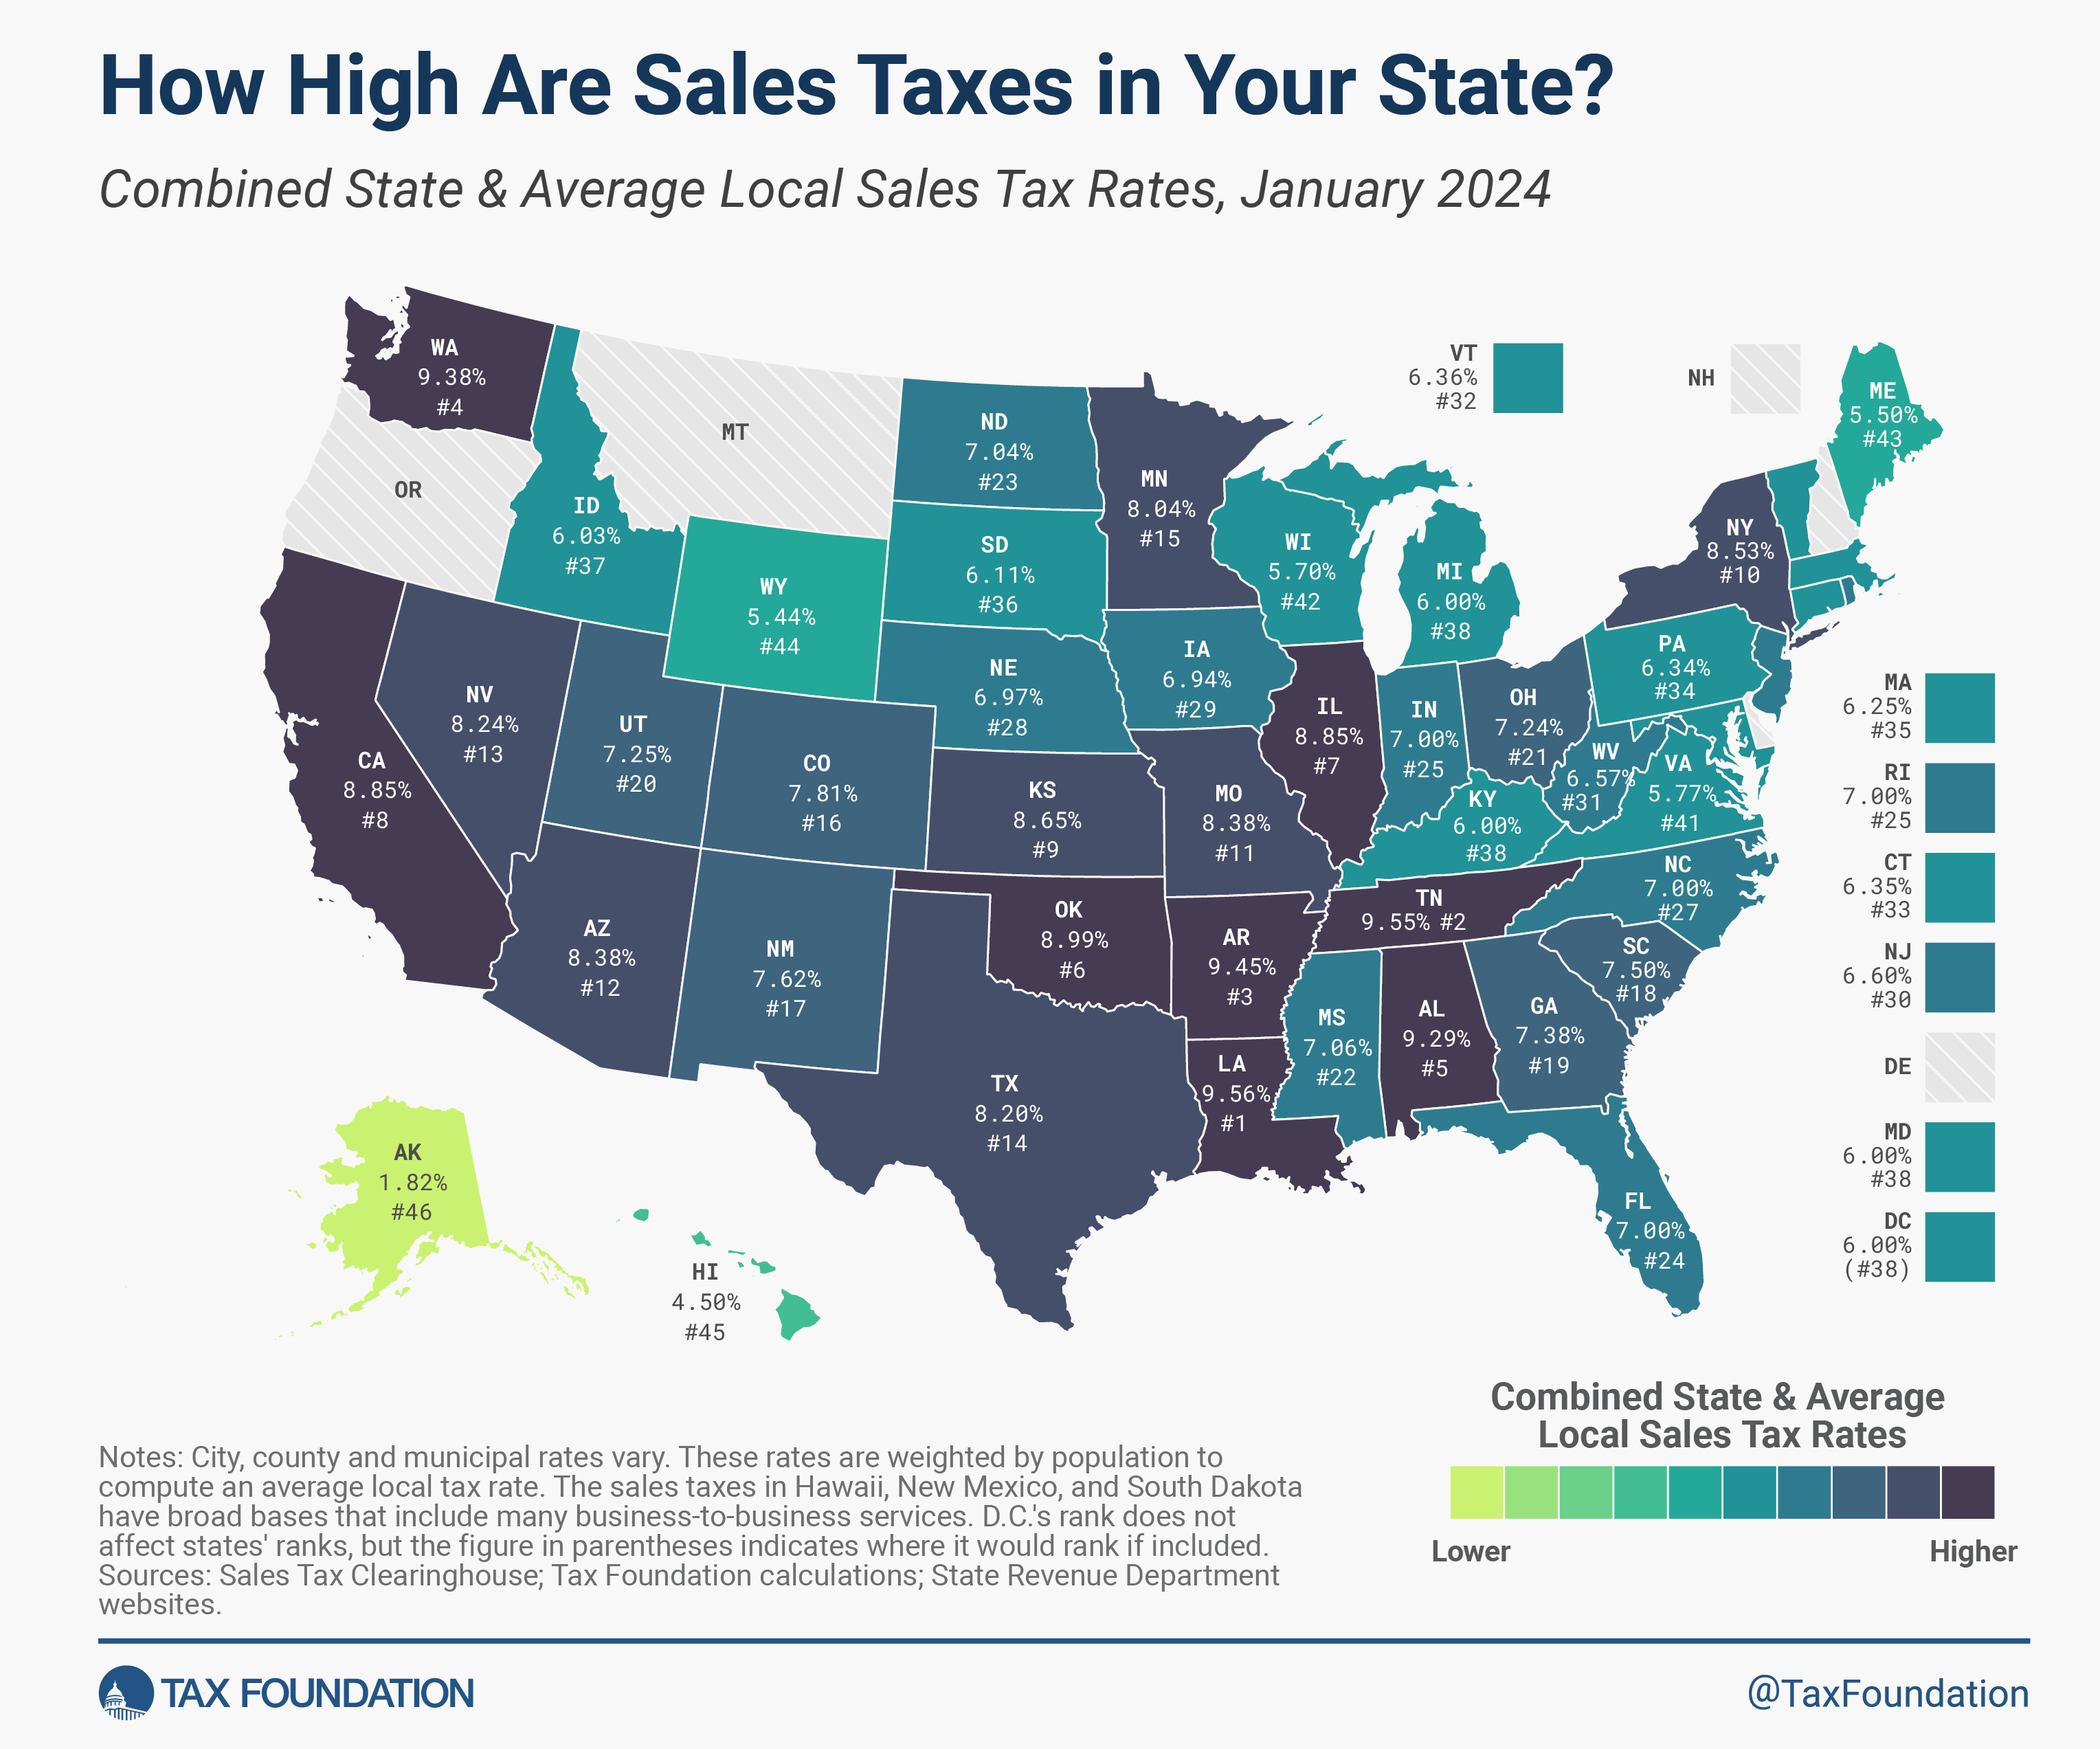
A state’s tax environment is one of several factors that companies, particularly in the highly mobile tech sector, consider when deciding where to locate and grow. While New Jersey boasts a strategic location, a skilled workforce, and reputable universities, its sales tax rate, when combined with other state and local taxes, contributes to the overall cost of doing business and living. For tech companies specializing in areas like advanced navigation, remote sensing, or intricate camera systems, the ability to minimize operational costs is paramount. A favorable tax structure can attract established firms looking to expand and help retain local startups that might otherwise consider relocating to states with lower tax burdens or more targeted tech incentives. Policy discussions around sales tax often encompass its potential role in strengthening New Jersey’s position as a hub for tech and innovation.
Navigating Sales Tax Compliance for Tech Enterprises
The complexities of New Jersey’s sales tax framework necessitate careful attention to compliance for tech enterprises. This is particularly true given the dynamic nature of technology sales, often involving online transactions and evolving interpretations of digital product taxation.
Remote Sales and Nexus Considerations
In the modern digital economy, many tech companies, especially those selling drones, flight technology, camera equipment, or drone accessories, engage in remote sales. The concept of “nexus” – a sufficient physical presence or economic activity in a state – determines whether an out-of-state seller must collect New Jersey sales tax. Following the South Dakota v. Wayfair Supreme Court decision, New Jersey, like many states, has implemented economic nexus rules. This means that even without a physical presence, businesses exceeding certain sales thresholds (e.g., $100,000 in sales or 200 separate transactions into New Jersey annually) are required to register and collect New Jersey sales tax. This is a critical compliance consideration for drone manufacturers, online retailers of FPV systems, or software providers serving customers in New Jersey, regardless of their own physical location.
Streamlining Tax Processes with Technology
Ironically, technology itself offers solutions for navigating sales tax complexities. Tech enterprises can leverage specialized tax compliance software and automated systems to manage sales tax calculations, collections, and remittances. These tools can automatically apply the correct 6.625% rate, handle exemptions, track economic nexus thresholds, and prepare accurate filings. For companies dealing with a high volume of transactions, selling diverse products (physical goods, software, digital services), or operating across multiple jurisdictions, investing in such technology can significantly reduce the administrative burden and minimize the risk of errors or non-compliance penalties. This showcases how innovation can be harnessed to streamline even the most traditional regulatory processes.
Future Outlook: Digital Economy Taxation
The rapid evolution of the digital economy, characterized by the growth of cloud computing, subscription services, and AI-driven platforms, continuously challenges existing sales tax frameworks. New Jersey, like other states, faces the ongoing task of adapting its tax laws to keep pace with technological advancements. Discussions around taxing data, digital services, and the digital aspects of “things as a service” models are ongoing. For tech and innovation companies, staying abreast of these potential changes is crucial. Future adjustments to the New Jersey sales tax rate or its application could significantly impact the business models of companies specializing in drone-as-a-service, mapping-as-a-service, or other cutting-edge offerings that blur the lines between tangible goods and intangible services. Understanding the current 6.625% rate is merely the starting point; anticipating how it might evolve in response to technological innovation is key to long-term strategic planning.