
Navigating Wealth Growth in the Innovation Economy
The landscape of modern innovation, from cutting-edge AI developments to autonomous systems and advanced remote sensing, often correlates with dynamic career paths and significant earning potential. For professionals and entrepreneurs thriving in these high-growth sectors, understanding the nuances of personal finance, particularly tax-advantaged retirement accounts like the Roth IRA, becomes paramount. While the allure of substantial income is a primary driver in the tech and innovation space, it also introduces complexities in leveraging certain financial tools designed with specific income thresholds in mind. A Roth IRA, celebrated for its tax-free withdrawals in retirement, presents a compelling opportunity for long-term wealth accumulation. However, its accessibility is directly tied to an individual’s income, making the “income cap” a critical consideration for many working at the forefront of technological advancement.

The Unique Financial Trajectories of Tech Innovators
Innovators and leaders in fields like AI, drone technology, and advanced robotics often experience rapid salary growth and varying income streams, including equity, bonuses, and entrepreneurial profits. This accelerated financial trajectory, while highly desirable, can quickly push individuals beyond the standard income limits for direct Roth IRA contributions. Unlike traditional IRAs, which often allow tax-deductible contributions regardless of income (though deductibility phases out), Roth IRAs have a hard cap on who can contribute directly. This necessitates a clear understanding of these limits and alternative strategies to ensure that the benefits of tax-free retirement growth are not overlooked. For those shaping the future of technology, strategic financial planning is as crucial as technical acumen.
The Appeal of Tax-Advantaged Retirement Savings
The primary draw of a Roth IRA lies in its tax treatment: contributions are made with after-tax dollars, and qualified withdrawals in retirement are completely tax-free. This offers a significant advantage, particularly for younger professionals who anticipate being in a higher tax bracket during retirement than they are today, or for those who simply prefer tax certainty in their golden years. For individuals in high-growth tech careers, whose future earning potential and therefore future tax bracket could be substantial, the Roth IRA acts as a powerful hedge against rising taxes. Furthermore, Roth IRAs offer flexibility, allowing contributions to be withdrawn tax- and penalty-free at any time (for the original contribution amount), providing a degree of liquidity often appreciated by those in fast-paced, sometimes unpredictable, career paths.
Decoding Roth IRA Eligibility and Contribution Limits
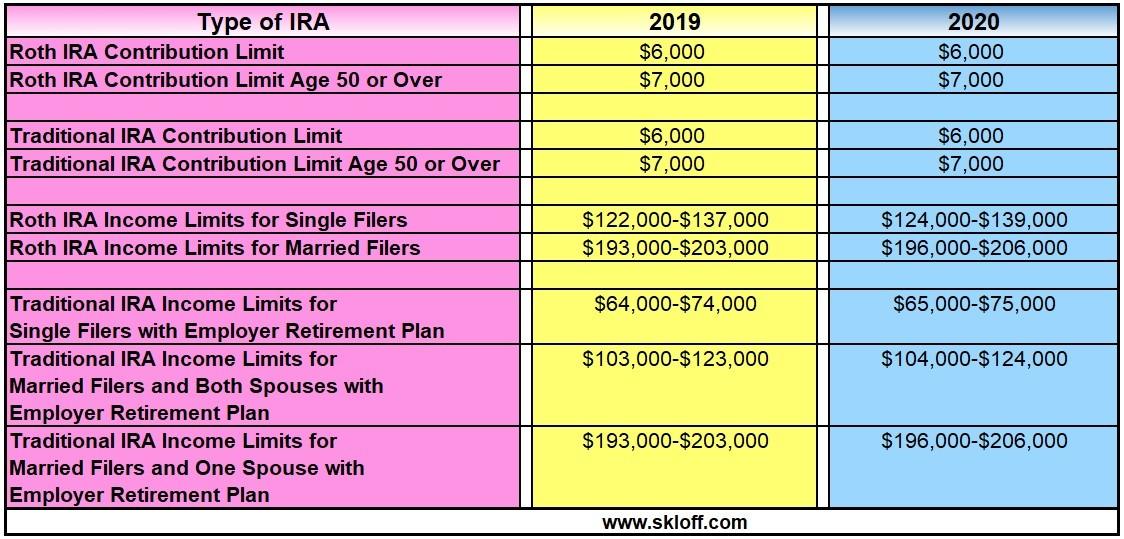
Understanding the specific income limitations is the first step for anyone considering a Roth IRA, especially for high-earning professionals in tech and innovation. These caps are not static and are subject to annual adjustments by the IRS, making it essential to stay informed about the most current figures. Eligibility is determined by an individual’s Modified Adjusted Gross Income (MAGI), a figure that can sometimes be more intricate to calculate than standard gross income.
Understanding Modified Adjusted Gross Income (MAGI)
Your Modified Adjusted Gross Income (MAGI) is the key determinant for Roth IRA eligibility. It’s calculated by taking your Adjusted Gross Income (AGI) and adding back certain deductions. Common items added back include deductions for student loan interest, one-half of self-employment taxes, and certain exclusions for foreign earned income. For many W-2 employees in tech, their MAGI might closely align with their AGI. However, for entrepreneurs, consultants, or those with complex investment portfolios common in the innovation sector, calculating MAGI accurately requires careful attention to detail. This figure directly impacts whether you can contribute directly to a Roth IRA, contribute a reduced amount, or are entirely phased out.
Current Income Phase-Out and Elimination Thresholds
For the 2024 tax year, the income caps for direct Roth IRA contributions are as follows:
- Single filers, heads of household, and married individuals filing separately (who did not live with their spouse at any time during the year):
- The ability to contribute to a Roth IRA begins to phase out when MAGI reaches $146,000.
- The ability to contribute is entirely eliminated when MAGI reaches $161,000 or more.
- Married individuals filing jointly and qualifying widow(er)s:
- The ability to contribute begins to phase out when MAGI reaches $230,000.
- The ability to contribute is entirely eliminated when MAGI reaches $240,000 or more.
- Married individuals filing separately (who lived with their spouse at any time during the year):
- The phase-out range is $0 to $10,000. This means virtually any income above $10,000 will eliminate their ability to contribute directly.
These thresholds illustrate why many experienced professionals in the tech sector, with competitive salaries and lucrative equity compensation, quickly find themselves above the direct contribution limits. Regularly reviewing these limits is crucial for anyone engaging in ongoing financial planning within the innovation economy.
The Impact of High Salaries in Tech on Direct Roth Eligibility
The rapid ascent of salaries in specialized tech fields, from senior software engineering to executive roles in AI startups, often means that individuals hit the Roth IRA income caps relatively early in their careers. While this is a testament to their professional success, it poses a challenge for direct Roth IRA contributions. A professional earning $170,000 as a single filer, for instance, is well beyond the direct contribution limit for 2024. This reality often necessitates exploring alternative strategies to access the tax-free growth benefits of a Roth IRA, ensuring that high income doesn’t become a barrier to optimized retirement savings. Understanding these limitations is not a roadblock, but rather a guidepost toward more sophisticated financial planning.
Advanced Strategies for High-Earning Innovators
For tech professionals whose income surpasses the direct Roth IRA contribution limits, the journey to tax-free retirement growth doesn’t end. Savvy financial planning offers several advanced strategies to bypass these caps, ensuring that innovators can still leverage the powerful advantages of Roth accounts. These tactics are particularly relevant for those generating significant wealth in dynamic, high-paying roles within the innovation sector.
The Backdoor Roth IRA Conversion: A Premier Tactic
The “backdoor Roth IRA” is a widely utilized strategy for high-income earners to contribute to a Roth IRA indirectly. This multi-step process involves:
- Contributing to a Traditional IRA: First, an individual contributes after-tax dollars to a traditional IRA. This contribution is non-deductible because their income is too high to deduct traditional IRA contributions.
- Converting to a Roth IRA: Soon after, these funds are converted from the traditional IRA to a Roth IRA.
- Tax Reporting: The conversion itself is generally a non-taxable event because the initial contribution was made with after-tax money. However, careful tax reporting is crucial using Form 8606 to track the non-deductible contributions and avoid double taxation.
This strategy is highly effective for circumventing the income caps. A critical consideration for the backdoor Roth is the “pro-rata rule.” If you have existing pre-tax funds in any traditional IRAs (including SEP IRAs or SIMPLE IRAs rolled into a traditional IRA), a portion of your conversion will be taxable. Therefore, individuals considering a backdoor Roth should ideally have no pre-tax funds in any traditional IRA accounts. This is often the case for younger professionals, but those with existing retirement savings need to carefully plan.
Exploring the Mega Backdoor Roth for Maximized Savings
For those working for companies that offer specific 401(k) plan features, the “mega backdoor Roth” can unlock even greater tax-free savings. This advanced strategy requires an employer-sponsored 401(k) plan that permits:
- After-tax 401(k) contributions: Contributions beyond the standard employee elective deferral and employer match, up to the overall IRS limit (which includes all contributions from employee and employer).
- In-service distributions or rollovers: Allowing these after-tax contributions to be moved out of the 401(k) while still employed.
The process involves contributing a significant amount of after-tax money to your 401(k), then immediately converting or rolling over these after-tax funds into a Roth IRA or a Roth 401(k) (if offered). This strategy allows individuals to contribute tens of thousands of dollars more into a Roth account than standard limits permit, leveraging the higher overall 401(k) contribution limits. The mega backdoor Roth is particularly powerful for very high earners in the tech sector whose employers offer the necessary 401(k) plan design, enabling them to build substantial tax-free retirement wealth.
Leveraging Employer-Sponsored Plans and Other Tax-Advantaged Accounts
Beyond Roth IRAs and their backdoor variants, high-earning innovators should fully optimize other available tax-advantaged accounts. Maximizing contributions to employer-sponsored 401(k)s, particularly if they offer Roth 401(k) options, is a foundational step. For self-employed individuals or those with significant consulting income in the tech space, SEP IRAs or Solo 401(k)s offer much higher contribution limits than traditional IRAs, allowing for substantial pre-tax savings. Health Savings Accounts (HSAs), often dubbed “the triple-tax-advantaged account,” provide tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses, making them an excellent complement to retirement savings. A holistic approach to retirement and investment planning, incorporating all available avenues, is essential for robust financial health in the innovation economy.
Strategic Financial Planning for a Dynamic Future
For professionals navigating the high-stakes, high-reward environment of tech and innovation, financial planning is not a static exercise but an ongoing, dynamic process. The rapid pace of wealth accumulation and the complexity of income structures in these fields necessitate a forward-thinking approach that goes beyond simply understanding Roth IRA income caps. It involves proactive engagement with financial strategies that adapt to evolving circumstances, ensuring long-term financial security and growth.
Proactive Planning Amidst Rapid Wealth Accumulation
The rapid growth in income and asset value for successful innovators can bring both opportunities and challenges. Proactive planning helps manage these complexities, from optimizing investment portfolios to minimizing tax liabilities. For instance, understanding when to exercise stock options, how to manage restricted stock units (RSUs), and how these impact MAGI for Roth IRA eligibility are critical considerations. Regularly reviewing and adjusting financial strategies in consultation with a financial advisor specializing in high-net-worth individuals or those in the tech sector ensures that wealth accumulation is not only efficient but also aligned with long-term goals. This foresight allows for strategic asset allocation, tax-loss harvesting, and optimized charitable giving, all designed to enhance net worth.
Diversification and Investment Beyond Retirement Accounts
While tax-advantaged retirement accounts like Roth IRAs are foundational, a comprehensive financial plan for tech innovators extends significantly beyond them. Diversification across various asset classes—stocks, bonds, real estate, and alternative investments—is crucial for managing risk and maximizing growth potential. Many innovators also find themselves with substantial equity in private companies or startup ventures. Balancing these concentrated positions with more diversified public market investments is a key aspect of prudent wealth management. Furthermore, taxable brokerage accounts play an important role, offering liquidity and flexibility for shorter-term goals or as an additional avenue for growth once tax-advantaged accounts are maximized.

Adapting to Evolving Tax Landscapes and Economic Shifts
The innovation economy is constantly evolving, and so too are tax laws and macroeconomic conditions. What holds true for Roth IRA income caps and tax strategies today may shift in the future. Professionals in this sector must remain agile, regularly reviewing changes in tax legislation, retirement contribution limits, and economic forecasts that could impact their financial plans. Staying informed about potential legislative changes related to retirement accounts or capital gains taxes is vital for making timely adjustments. A flexible financial plan, capable of adapting to these external factors, is a hallmark of sophisticated wealth management for those shaping the future through technology and innovation.