
The Evolving Risk Landscape in Drone Tech & Innovation
The rapid ascent of drone technology has not only reshaped industries from agriculture to logistics but has also fundamentally altered the landscape of operational risk. What began as a niche for hobbyists has blossomed into a sophisticated ecosystem of advanced aerial platforms, each pushing the boundaries of what is technically possible. This exponential growth in capability, autonomy, and application necessitates a re-evaluation of traditional risk management and insurance paradigms. As drones become more integrated into critical infrastructure and complex commercial operations, understanding and categorizing their inherent risks becomes paramount.
From Hobby to Hyper-Specialized Missions
Initially, the insurance concerns around drones were relatively straightforward, primarily covering accidental damage or third-party liability for recreational use. However, the advent of commercial drones brought about a new class of risks. Drones are now deployed for precision mapping in construction, detailed infrastructure inspection, agricultural spraying, and even last-mile delivery. Each of these applications involves unique operational environments, different levels of human interaction, and varying degrees of autonomy, leading to distinct risk profiles. A drone inspecting a remote pipeline carries a different risk than an autonomous swarm navigating an urban delivery route. The sheer diversity of these missions means that a one-size-fits-all approach to insurance is no longer viable, creating a need for more granular classifications.
Unprecedented Capabilities, Unforeseen Liabilities
Modern drones are equipped with cutting-edge technology: high-resolution multi-spectral sensors, LIDAR systems, sophisticated AI for navigation and object recognition, and advanced communication arrays. Features like AI Follow Mode, autonomous flight planning, and real-time remote sensing capabilities, while revolutionary, also introduce complex liability questions. Who is responsible when an AI-driven drone makes an unforeseen error? What are the implications of data breaches from sensitive information collected by remote sensing platforms? The very innovations that make these drones so powerful also create new categories of risk, ranging from cyber liabilities and privacy concerns to operational failures of highly complex integrated systems. As the technology outpaces existing regulatory and legal frameworks, insurers grapple with assessing novel risks that have no historical precedents, making precise classification and risk grouping indispensable.
Bridging the Gap: Tailored Insurance for Advanced Drone Systems
The traditional insurance industry, built on decades of actuarial data from established sectors, faces a significant challenge in accommodating the dynamic and often unpredictable nature of drone technology. Generic policies, designed for conventional assets and operations, are frequently ill-equipped to address the specific nuances and emerging risks associated with advanced aerial systems. This gap necessitates the development of specialized insurance products that can accurately assess, price, and cover the unique liabilities posed by drone innovation.
The Limitations of Generic Policies
Standard liability policies typically lack the granular detail required to differentiate between various drone types, their intended uses, the environments they operate in, or their level of technological sophistication. For instance, a policy designed for a manned aircraft might not adequately cover the risks associated with an autonomous drone operating beyond visual line of sight (BVLOS), which includes potential communication loss, software malfunctions, or unforeseen interactions with air traffic. Furthermore, traditional policies often do not account for emerging liabilities such as data collection privacy breaches, intellectual property infringement from mapping operations, or cyber-attacks targeting autonomous flight systems. This inadequacy means that commercial drone operators could be under-insured or, worse, uninsured for critical risks, stifling innovation due to unmanageable exposure.
The Rise of Drone-Specific Underwriting
To address these limitations, a specialized drone insurance market has emerged. Underwriters in this sector delve deep into the technical specifications of drone systems, understanding the intricacies of flight control software, sensor payloads, communication protocols, and the reliability of autonomous functions. They consider factors like pilot qualifications for manned operations, but also the robustness of AI algorithms for autonomous missions. This detailed analysis allows for the creation of bespoke policies that can cover a wide range of scenarios, from hull damage to third-party public liability, product liability for drone manufacturers, and even cyber liability for data-intensive operations. The goal is to provide comprehensive coverage that evolves with the technology, ensuring that innovative drone applications are supported by appropriate risk mitigation strategies. This shift towards specialized underwriting is crucial for fostering a secure environment for advanced drone development and deployment.
Introducing the “Tech Innovation Insurance Group Number”
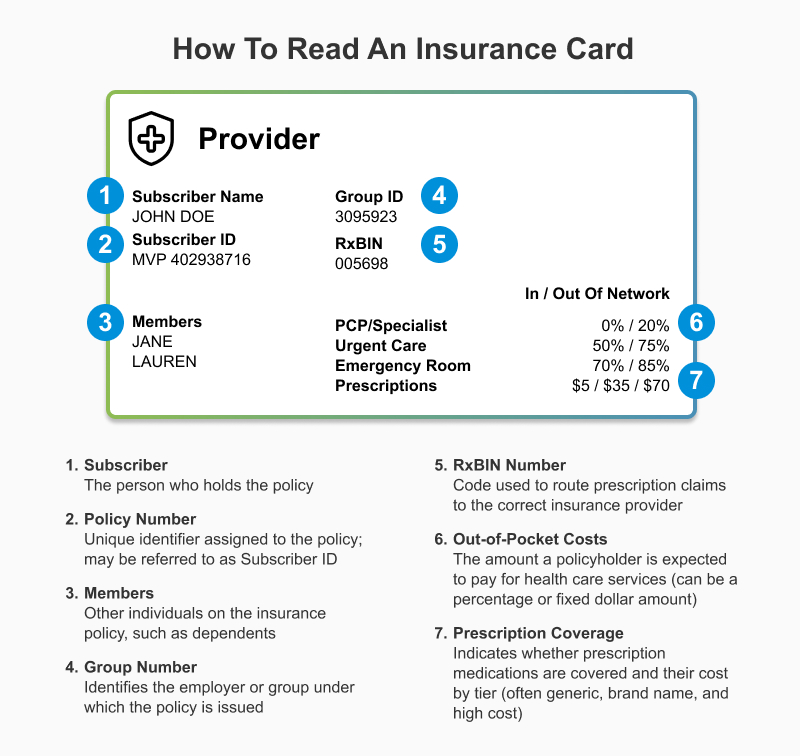
In the context of highly specialized and rapidly evolving drone technology, the concept of a “Group Number for Insurance” transcends a mere administrative identifier. Instead, it transforms into a critical classification system, a structured method by which insurers categorize drone technologies and operational profiles based on their inherent innovation, complexity, and associated risk. This “Tech Innovation Insurance Group Number” serves as a benchmark for risk assessment, helping to standardize the underwriting process for cutting-edge drone applications.
A Classification System for Risk and Autonomy
This conceptual “Group Number” acts as a unique identifier for a specific classification of drone technology, reflecting its level of autonomy, technological sophistication, and the risk matrix it embodies. Unlike traditional insurance group numbers tied to employment or policy type, this grouping is dynamically assigned based on the drone’s technical specifications and operational intent. For example, a basic quadcopter used for photography might fall into a lower risk group, while an AI-powered, fully autonomous drone conducting BVLOS inspections of critical infrastructure would be assigned a higher, more complex group number. This systematic classification enables insurers to move beyond generic assumptions and tailor coverage to the specific technological capabilities and liabilities of each drone system. It acknowledges that not all drones are created equal in terms of risk, and that innovation directly correlates with the need for refined risk assessment.
Parameters for Group Assignment
The assignment of a “Tech Innovation Insurance Group Number” would be based on a comprehensive evaluation of several key technical parameters:
- AI Integration and Autonomy Levels: The degree to which Artificial Intelligence governs flight, decision-making, obstacle avoidance, and mission execution. Higher levels of autonomy, particularly those involving advanced machine learning or neural networks, would typically correlate with higher risk groups due to the novel and sometimes unpredictable nature of AI behavior.
- Sensor Sophistication and Data Handling: The type and capability of sensors (e.g., thermal, LIDAR, hyperspectral imaging) and the sensitivity of the data they collect. Operations involving high-value data, critical infrastructure mapping, or personal data collection would fall into groups requiring specific cyber and privacy liability coverage.
- Operational Environment and Complexity: Whether the drone operates in controlled airspace, urban environments, remote areas, or challenging industrial settings. BVLOS operations, flights over crowds, or missions near sensitive facilities would command a higher group number due to increased operational complexity and potential for third-party impact.
- Hardware and Software Reliability: The proven track record and redundancy of the drone’s flight control systems, propulsion, communication links, and cybersecurity measures. Systems with experimental hardware or unproven software iterations might be placed in a higher risk group until their reliability is established.
- Payload Value and Risk: The nature and value of the payload being carried, especially for delivery or specialized sensing missions, where the payload itself could present significant liability if damaged or lost.
Impact on Premiums and Coverage Scope
The assigned “Tech Innovation Insurance Group Number” directly influences the premium rates and the scope of coverage offered. Drones classified in higher risk groups due to advanced AI, autonomous capabilities, or complex operations would naturally incur higher premiums to reflect their increased potential for incident and liability. Conversely, lower-risk groups would benefit from more affordable coverage. This classification system also dictates the mandatory and optional coverage components. For instance, a drone in a high-autonomy group might require comprehensive cyber liability and product liability for its AI systems, whereas a lower-tech group might only need basic third-party liability and hull coverage. By providing a clear, tech-driven grouping mechanism, insurers can offer more accurate pricing and ensure that policies precisely match the unique risk profile of each innovative drone application, fostering a robust and responsible ecosystem for aerial technology.
Driving Responsible Innovation Through Risk Assessment
The establishment of a sophisticated “Tech Innovation Insurance Group Number” system is not merely about managing risk; it is a strategic imperative for fostering responsible innovation within the drone industry. By clearly categorizing technologies based on their risk profiles, insurers play a crucial role in shaping safe development practices, encouraging adherence to emerging standards, and ultimately accelerating the adoption of groundbreaking aerial solutions.
Encouraging Adherence to Safety Standards
A well-defined grouping system creates a strong incentive for drone manufacturers and operators to prioritize safety, reliability, and robust system design. Drones that incorporate proven redundant systems, adhere to established software development best practices, and demonstrate rigorous testing of autonomous functions could be assigned to lower risk groups, translating into more favorable insurance premiums. This direct financial benefit encourages investment in advanced safety features, robust cybersecurity, and comprehensive training protocols for operators. It pushes the industry towards self-regulation and the adoption of high operational standards, ultimately leading to a safer air environment for everyone. Insurers, through their risk classifications, become de facto arbiters of best practices in an industry that is still rapidly maturing.
Facilitating Growth in Emerging Drone Sectors
For nascent drone sectors, such as autonomous urban air mobility or complex remote sensing for environmental monitoring, the availability of clear insurance frameworks linked to their technological sophistication is critical. Without a means to accurately assess and insure these novel risks, innovators might struggle to secure funding, obtain regulatory approvals, or even launch their services. The “Tech Innovation Insurance Group Number” provides a standardized language for risk communication between tech developers, operators, regulators, and insurers. This clarity reduces uncertainty, streamlines the underwriting process, and enables the development of tailored insurance products essential for de-risking new ventures. By making insurance accessible and appropriate for cutting-edge applications, this system lowers barriers to entry and stimulates investment, propelling the growth of transformative drone technologies.
The Future of Dynamic Risk Grouping
As drone technology continues its rapid evolution, the “Tech Innovation Insurance Group Number” must remain dynamic. Future iterations could incorporate real-time operational data, AI-driven risk analytics, and predictive modeling to adjust group classifications dynamically. For example, a drone’s group number could temporarily shift based on live weather conditions, detected airspace congestion, or even its recent flight performance history. This continuous feedback loop between operational data and risk assessment will allow for even more precise underwriting, rewarding operators who maintain exceptional safety records and adopt cutting-edge risk mitigation technologies. Ultimately, this sophisticated grouping system will be indispensable for navigating the complexities of an increasingly autonomous and intelligent aerial future, ensuring that innovation continues responsibly and sustainably.