
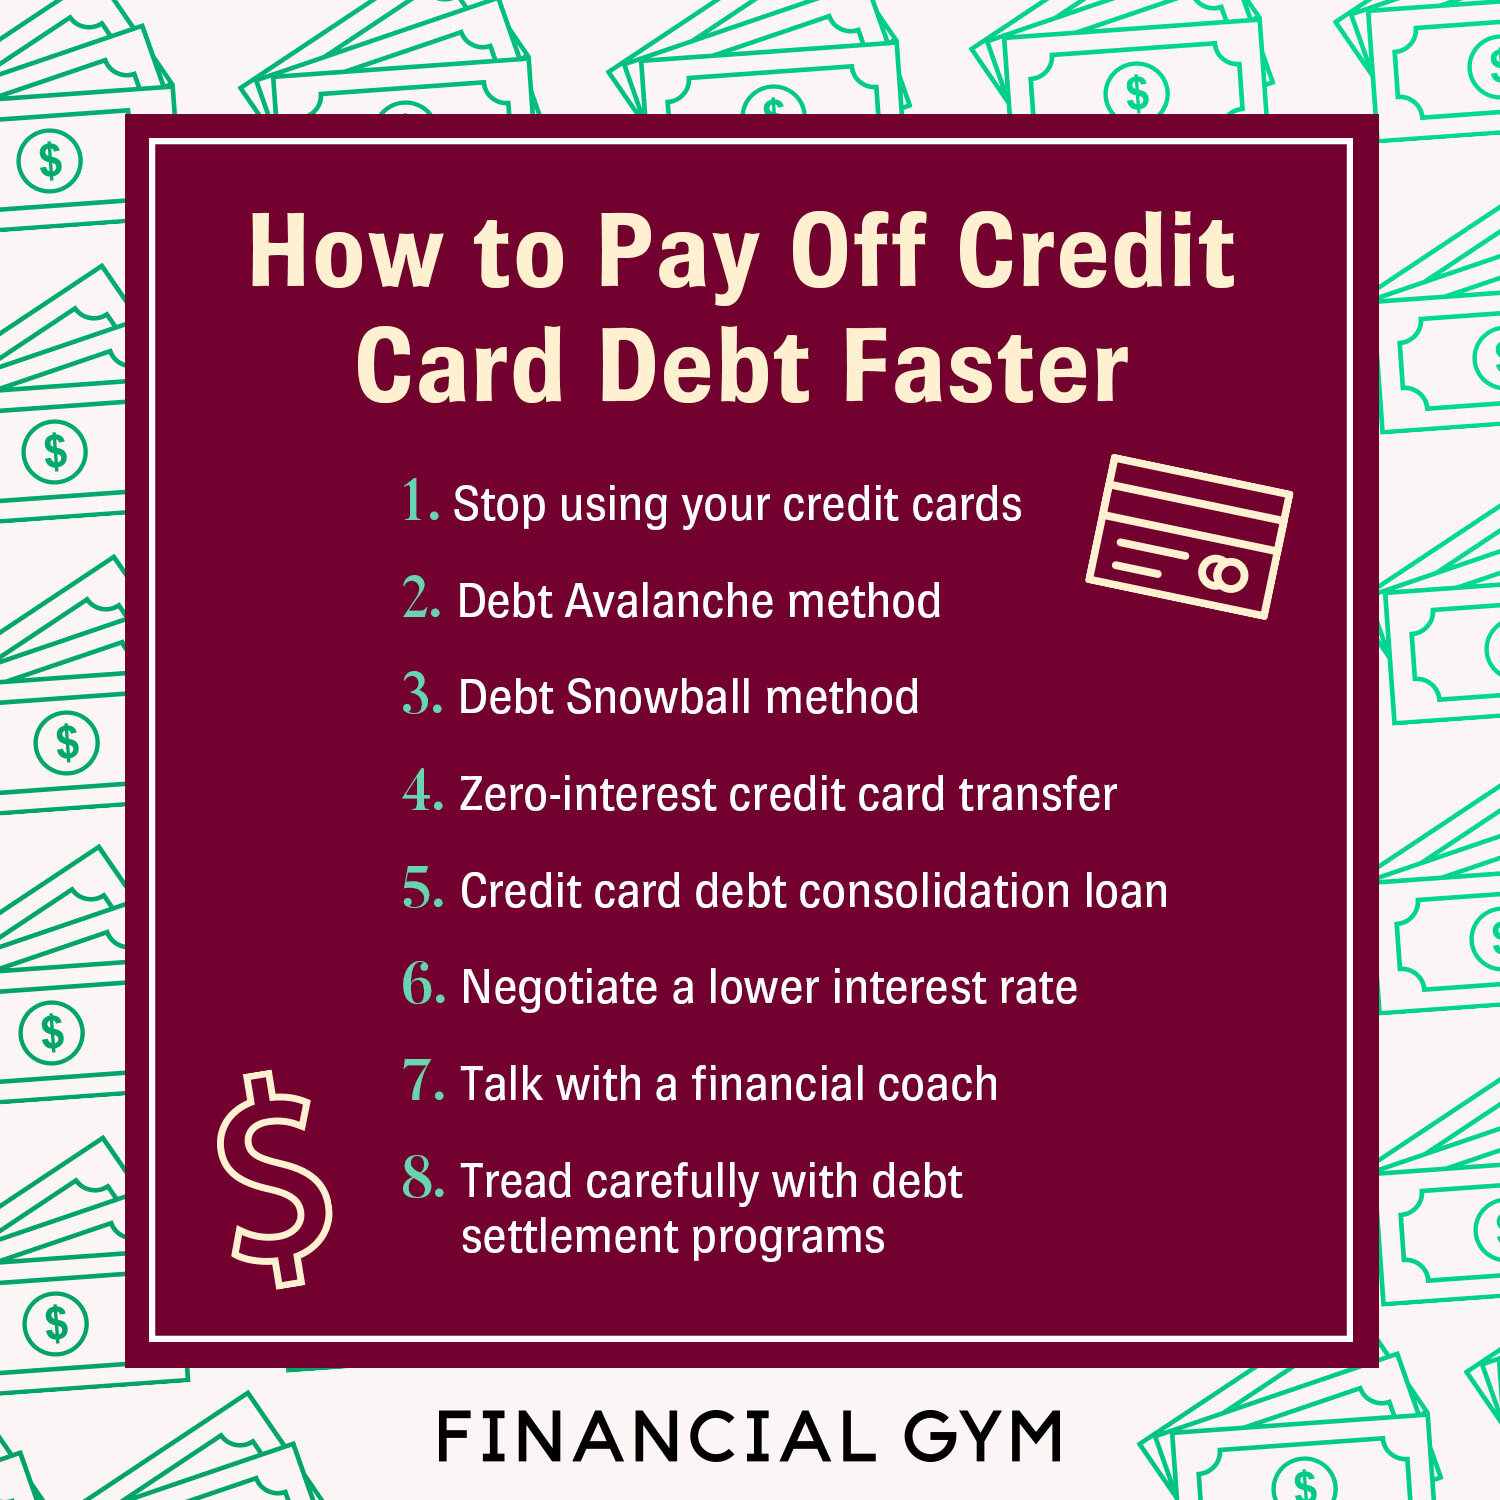
Navigating the labyrinth of credit card debt can feel overwhelming, but understanding strategic repayment methods is the key to regaining financial control. While the most effective approach is often a personalized blend of techniques, several core strategies stand out. This guide explores the most efficient ways to tackle your credit card balances, empowering you to make informed decisions and chart a clear path toward a debt-free future.
The Avalanche Method: Prioritizing Interest
The avalanche method is a mathematically driven approach that focuses on minimizing the total interest paid over the life of your debt. It’s a disciplined strategy that rewards patience and a keen eye for financial detail.
How the Avalanche Method Works
At its core, the avalanche method involves making minimum payments on all your credit cards except for the one with the highest interest rate (APR). All extra funds are then directed towards aggressively paying down this highest-APR card. Once that card is paid off, you roll the entire payment amount (minimum payment plus the extra funds) onto the card with the next highest APR, and so on.
The Mathematical Advantage
The primary benefit of the avalanche method lies in its ability to reduce the overall cost of your debt. By systematically eliminating the most expensive balances first, you prevent interest from accumulating as rapidly. Over time, this can lead to significant savings compared to other methods.
When the Avalanche Method is Ideal
This strategy is best suited for individuals who are highly motivated by financial efficiency and are comfortable with a methodical, data-driven approach. If your primary goal is to save the most money possible on interest, and you can maintain discipline in sticking to the plan, the avalanche method is a powerful tool. It also benefits those with multiple credit cards, where the varying interest rates can create a substantial difference in total repayment cost.
Potential Drawbacks of the Avalanche Method
The psychological impact of the avalanche method can be a drawback for some. Because you are not seeing quick wins with smaller balances, it can feel like a longer and more arduous journey. If you are someone who thrives on immediate visible progress, the avalanche method might feel discouraging in the initial stages.
The Snowball Method: Building Momentum
In contrast to the avalanche method’s focus on interest, the snowball method prioritizes psychological wins. This strategy uses a debt repayment plan that builds on early successes to maintain motivation and momentum.
How the Snowball Method Works
With the snowball method, you list your debts from smallest balance to largest, regardless of interest rate. You make minimum payments on all debts except for the smallest one. All extra funds are then directed towards aggressively paying off this smallest balance. Once that debt is eliminated, you take the entire payment amount (minimum payment plus the extra funds) and add it to the payment for the next smallest debt, creating a larger “snowball” of repayment.
The Power of Early Wins
The psychological advantage of the snowball method is undeniable. By quickly eliminating smaller debts, you achieve tangible victories that can significantly boost morale and reinforce your commitment to the repayment plan. These early successes create a sense of accomplishment and make the journey feel more manageable.
When the Snowball Method is Ideal
This strategy is exceptionally effective for individuals who need constant reinforcement and motivation to stay on track. If you’ve struggled with debt repayment in the past due to a lack of perceived progress, the snowball method can provide the necessary encouragement to keep going. It’s also a great option for those who are new to debt management and want a less intimidating entry point.
Potential Drawbacks of the Snowball Method
The primary drawback of the snowball method is that it can result in paying more interest over time compared to the avalanche method. By not prioritizing the highest-interest debts, you may allow interest to accrue on larger balances for longer periods. For individuals with significant differences in interest rates across their credit cards, this could lead to a higher overall repayment cost.
Debt Consolidation: Simplifying Your Payments
Debt consolidation involves combining multiple credit card debts into a single, new loan or balance. The goal is to simplify payments, potentially lower your interest rate, and create a more manageable repayment structure.

Understanding Debt Consolidation Options
There are several primary avenues for debt consolidation:
- Balance Transfer Credit Cards: These cards offer a promotional period with a 0% or low introductory APR on transferred balances. This allows you to pay down principal without accruing interest for a set duration.
- Key Considerations: Be aware of balance transfer fees (typically 3-5% of the transferred amount) and the APR after the introductory period ends. It’s crucial to have a plan to pay off the balance before the promotional rate expires.
- Debt Consolidation Loans: These are personal loans specifically designed to pay off multiple debts. You receive a lump sum and then make one monthly payment to the lender.
- Key Considerations: Eligibility and interest rates depend on your credit score. Ensure the new loan’s interest rate is lower than the average APR of your current credit cards to realize savings.
- Home Equity Loans or Lines of Credit (HELOCs): If you own a home with equity, you can leverage it to consolidate debt. These loans often have lower interest rates than credit cards.
- Key Considerations: Using your home as collateral carries risk. Failure to repay could result in foreclosure.
Benefits of Debt Consolidation
The primary benefit of debt consolidation is simplification. Managing one monthly payment instead of multiple can reduce stress and the likelihood of missed payments. If you can secure a lower interest rate through consolidation, you can also save money on interest charges and pay off your debt faster.
Risks Associated with Debt Consolidation
It’s crucial to approach debt consolidation with caution. If you transfer a balance to a card with a high regular APR, or if your consolidation loan has a higher interest rate than your current debts, you could end up paying more. Furthermore, some individuals may fall into the trap of running up new balances on their freed-up credit cards after consolidation, negating any progress and exacerbating their debt situation.
Debt Management Plans (DMPs)
A Debt Management Plan (DMP) is a program offered by non-profit credit counseling agencies. Under a DMP, you make one monthly payment to the agency, which then distributes the funds to your creditors.
How Debt Management Plans Work
When you enroll in a DMP, a credit counselor negotiates with your creditors on your behalf to potentially lower interest rates, waive late fees, and establish a manageable repayment schedule. You will then make a single, consolidated payment to the credit counseling agency each month, which they will disburse to your creditors.
Benefits of a DMP
DMPs can offer a structured and supportive way to manage overwhelming debt. They can lead to lower interest rates, which reduces the overall cost of your debt. The single monthly payment simplifies budgeting and reduces the stress of managing multiple creditors. DMPs are also a good option for those who may not qualify for balance transfer cards or consolidation loans due to poor credit.
Considerations for DMPs
While beneficial, DMPs are not without considerations. Enrolling in a DMP may involve a small monthly fee. Some DMPs require you to close your credit card accounts as part of the agreement, which can impact your credit utilization ratio. It’s essential to choose a reputable credit counseling agency and understand all terms and conditions before committing.
The Hybrid Approach: Tailoring Your Strategy
Often, the most effective way to pay off credit card debt is not to rigidly adhere to a single method but to create a personalized hybrid strategy. This involves understanding the strengths and weaknesses of each approach and applying them to your unique financial situation.
Assessing Your Financial Landscape
Begin by thoroughly evaluating your debts: list all credit cards, their balances, interest rates (APRs), and minimum payments. Understand your current income, expenses, and any available extra funds you can allocate towards debt repayment.
Combining Strategies for Maximum Impact
Consider these hybrid scenarios:
- Avalanche with a Snowball Boost: If you have a few small, high-interest debts, you might tackle those first using the snowball method to gain quick wins and free up cash flow. Once those are cleared, shift to the avalanche method for your larger, high-interest balances.
- Consolidation Followed by Avalanche/Snowball: If you can secure a low-interest balance transfer card or a consolidation loan, use it to combine your high-APR debts. Then, apply either the avalanche or snowball method to the new consolidated balance.
- DMP for Stability, then Targeted Payoff: If your debt is significantly overwhelming, a DMP can provide immediate relief and structure. Once your interest rates are reduced and you have a manageable payment plan, you can then reassess and potentially accelerate payments on specific debts within the DMP framework.
The Importance of Discipline and Adaptability
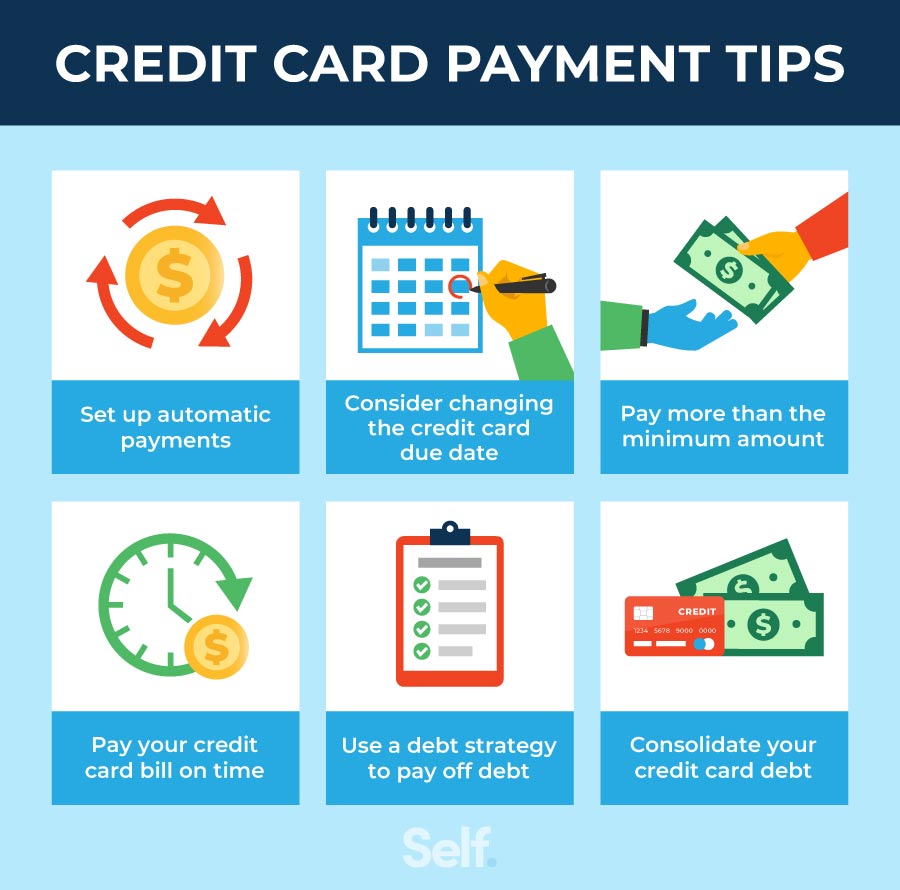
Regardless of the strategy you choose, discipline is paramount. Sticking to your repayment plan, avoiding new debt, and making consistent payments are non-negotiable. Equally important is adaptability. Life circumstances can change, and your debt repayment strategy may need to be adjusted accordingly. Regularly review your progress and be willing to make tweaks to your plan to ensure you remain on the path to financial freedom.
Paying off credit card debt is a journey, not a race. By understanding these core strategies and tailoring them to your individual needs, you can confidently navigate your debt and emerge stronger and more financially secure.