
In the ever-evolving landscape of personal finance, securing the best interest rate for a car loan remains a paramount concern for consumers. While the fundamental principles of creditworthiness and market conditions continue to play a crucial role, the advent of sophisticated technologies and groundbreaking innovations has fundamentally reshaped how these rates are discovered, offered, and managed. Today, the pursuit of an optimal car loan interest rate is less about traditional negotiation and more about leveraging cutting-edge tech and understanding the innovative platforms that drive modern lending.
The Algorithmic Edge in Loan Discovery and Personalization
The quest for the “best” interest rate is increasingly powered by advanced algorithms and artificial intelligence (AI). Traditional lending models often relied on static credit scores and broad demographic data, leading to a “one-size-fits-many” approach that might not capture an individual’s true financial risk or potential. Modern financial technology (Fintech) leverages AI and machine learning (ML) to process vast datasets, offering a more nuanced and personalized assessment.
AI-Driven Credit Scoring and Risk Assessment
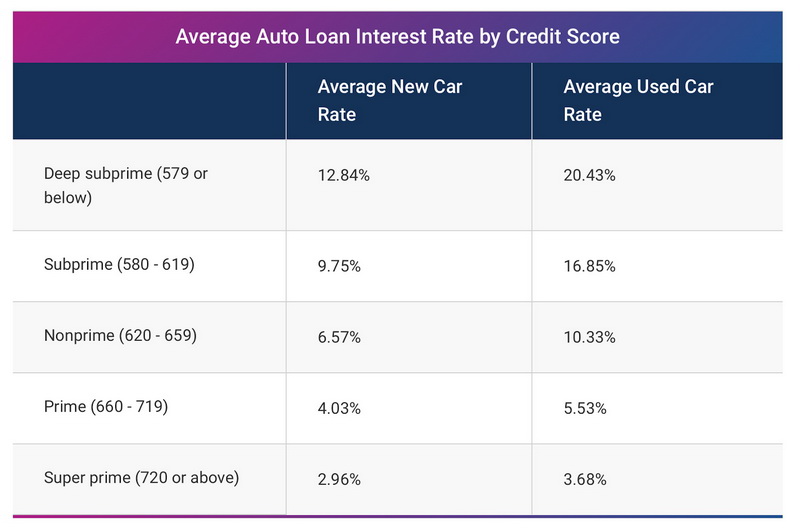
AI-powered platforms can analyze a much broader spectrum of data points than conventional methods, including spending habits, savings patterns, employment stability, and even educational background, all while adhering to privacy regulations. This deeper analytical capability allows lenders to construct more accurate risk profiles, potentially identifying low-risk borrowers who might be overlooked by traditional systems. For the consumer, this translates into the possibility of receiving a more favorable interest rate tailored precisely to their individual financial standing, rather than being grouped into a larger, less precise risk category. The “best” rate, in this context, becomes a hyper-personalized figure derived from a holistic understanding of their financial behavior, not just their credit report.
Predictive Analytics for Market Trends
Beyond individual borrower assessment, AI and ML are also employed to predict market shifts and interest rate fluctuations. Fintech companies use these tools to anticipate economic indicators, central bank policies, and even regional demand for vehicles. This predictive capability allows lenders to adjust their offerings proactively, ensuring they remain competitive while managing their own risk. For the consumer, engaging with platforms that utilize such advanced analytics can mean being presented with optimal rates at opportune times, potentially before a broader market shift might drive rates upwards. This foresight can be a significant advantage in securing a truly “best” rate.
Fintech Platforms: Democratizing Access to Optimal Rates
The rise of dedicated Fintech platforms has revolutionized how consumers shop for car loans. These innovative platforms act as aggregators and facilitators, connecting borrowers with a wide array of lenders and often streamlining the application process through digital means. Their core innovation lies in enhancing transparency, convenience, and competition.
Online Loan Marketplaces and Comparison Tools
Digital marketplaces are perhaps the most visible innovation in car loan acquisition. Websites and apps allow users to input their financial information once and receive multiple loan offers from various lenders almost instantaneously. These platforms utilize sophisticated backend technology to query numerous financial institutions, presenting personalized rates and terms side-by-side. This immediate comparison capability empowers consumers to swiftly identify the most competitive rates without the need for multiple inquiries or visits to different banks or dealerships. The “best” rate is no longer a needle in a haystack but a clear option presented alongside alternatives, fostering an environment of informed decision-making.

Streamlined Digital Application Processes
Another significant innovation is the shift from cumbersome paper applications to fully digital processes. Fintech platforms employ secure online portals, digital identity verification, and e-signature capabilities, drastically reducing the time and effort required to apply for and secure a loan. This efficiency not only enhances the user experience but also allows lenders to process applications more rapidly, often leading to quicker approvals. For consumers, a faster process means less waiting and the ability to finalize a loan efficiently, which can be particularly advantageous in a fast-moving car market or when a favorable rate is time-sensitive.
Blockchain and Decentralized Finance: A Glimpse into the Future of Auto Lending
While still nascent in widespread adoption for car loans, blockchain technology and decentralized finance (DeFi) represent a cutting-edge frontier that could fundamentally alter the landscape of interest rates and lending. These innovations promise unprecedented levels of transparency, security, and potentially, lower costs.
Enhanced Security and Transparency through Distributed Ledgers
Blockchain’s core innovation is its distributed, immutable ledger. In the context of car loans, this could mean a secure and transparent record of a vehicle’s ownership, maintenance history, and lien status, accessible to all authorized parties. This inherent transparency can reduce fraud and streamline the underwriting process, as lenders would have instant, verifiable access to critical information. For borrowers, a more trustworthy and efficient system could translate into reduced administrative costs and, consequently, more competitive interest rates as lenders’ operational risks decrease. The “best” rate here benefits from a foundational layer of digital trust.
Smart Contracts for Automated Loan Management
Smart contracts, self-executing contracts with the terms of the agreement directly written into code, hold immense potential for automating various aspects of a car loan. From automated monthly payments and interest calculations to the automatic release of collateral upon full repayment, smart contracts can eliminate the need for intermediaries and reduce manual processing errors. This automation could lead to significant cost savings for lenders, which can then be passed on to consumers in the form of lower interest rates. Imagine a car loan where every term and condition is executed flawlessly by code, minimizing disputes and maximizing efficiency – this could redefine what the “best” and most reliable interest rate entails.
Innovative Models: Personalized and Usage-Based Lending
Beyond the underlying technology, innovative lending models themselves are emerging, moving away from universal terms towards more personalized and dynamic financing solutions. These approaches are driven by data and a desire to align loan terms more closely with individual behavior and asset utilization.
Usage-Based Lending and Telematics Integration
For certain types of vehicles, particularly those that are part of shared economies or used for specific commercial purposes, telematics data could play a future role in loan assessment. While more common in auto insurance today, the concept of “usage-based lending” could emerge where interest rates are dynamically adjusted based on how the car is driven, its mileage, or even its maintenance schedule. Vehicles equipped with advanced sensors and connectivity could transmit data, allowing lenders to assess real-time risk more accurately. For responsible drivers or those with specific usage patterns, this could unlock highly personalized and favorable interest rates that traditional models could never offer, reflecting a truly bespoke “best” rate.
Peer-to-Peer (P2P) Lending and Crowdfunding
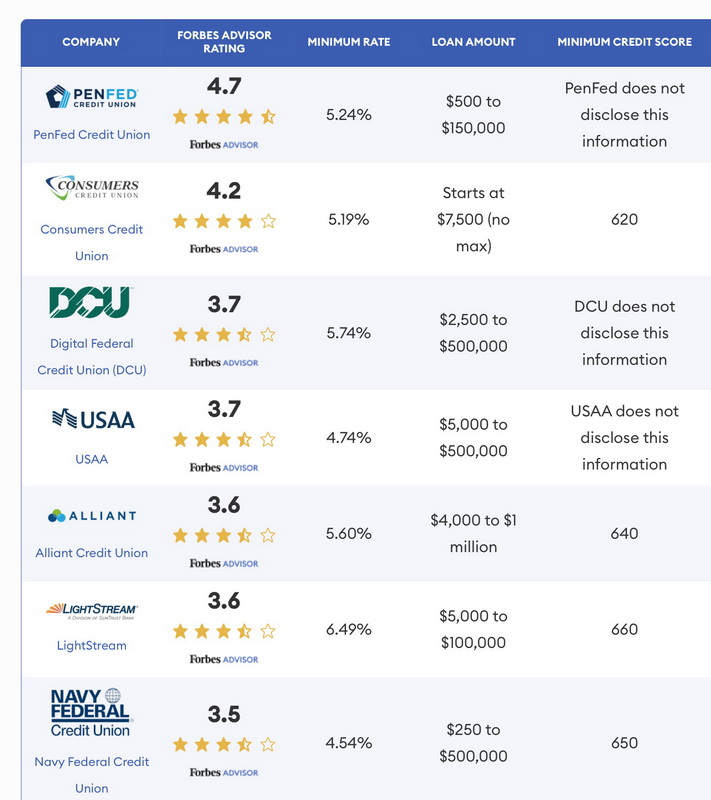
Innovations in financial platforms have also given rise to peer-to-peer lending models, which directly connect individual investors with borrowers, bypassing traditional banks. While P2P platforms for car loans are still developing, they represent a significant innovation in democratizing finance. These platforms often leverage unique algorithms to match borrowers with investors based on a more diverse set of criteria, potentially offering more flexible terms and competitive rates than conventional institutions. For borrowers who might not fit traditional banking profiles, or those seeking niche financing, P2P lending offers an alternative avenue to secure a personalized, potentially “best,” interest rate directly from a community of lenders.
In conclusion, the pursuit of the best interest rate for a car loan is no longer solely about strong credit and market timing. It’s an increasingly technology-driven endeavor, influenced by AI, machine learning, robust Fintech platforms, and even the nascent possibilities of blockchain. As these innovations continue to mature, consumers gain unprecedented tools and opportunities to navigate the complex world of auto financing, empowering them to secure terms that are truly optimized for their individual financial circumstances and aspirations. Understanding and leveraging these technological advancements is key to finding the truly “best” rate in today’s dynamic lending environment.