
The Form 1099-G, officially titled “Certain Government Payments,” plays a crucial role in the financial and tax landscape for individuals and entities receiving specific types of distributions from federal, state, or local governments. While the title might suggest a broad application, its primary function revolves around reporting income that, while received from a government entity, is often taxable and requires disclosure to the Internal Revenue Service (IRS) for accurate tax calculation. Understanding the nuances of the 1099-G is paramount for anyone who has received such payments, ensuring compliance with tax laws and avoiding potential penalties.
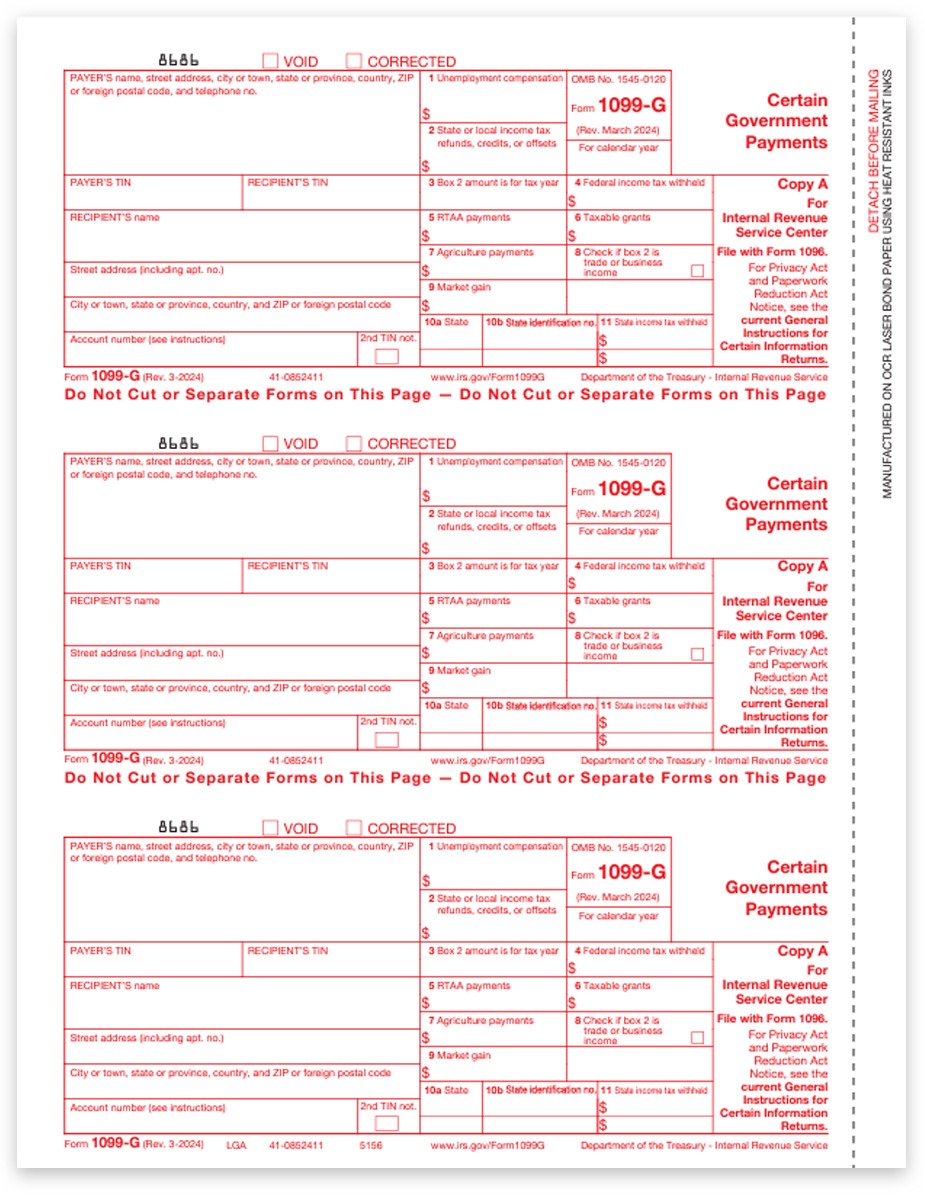
This form acts as an informational return, meaning the government agency issuing the payment sends a copy to both the recipient and the IRS. This parallel reporting mechanism helps the IRS cross-reference reported income, making it more challenging for taxpayers to omit taxable income from their annual returns. The information contained within a 1099-G details the type and amount of government payment received during a specific tax year, typically from January 1st to December 31st. Recipients should expect to receive this form by January 31st of the year following the tax year in which the payments were made.
Types of Payments Reported on Form 1099-G
The scope of payments reported on a 1099-G is defined by specific categories of government disbursements. It’s not a catch-all for every government handout; rather, it focuses on payments that are generally considered income. The most common and significant categories include:
Unemployment Compensation
Perhaps the most widely recognized use of the 1099-G form is for reporting unemployment compensation benefits. When individuals are laid off or lose their jobs through no fault of their own, they may be eligible for unemployment benefits provided by state governments, often supplemented by federal programs. These benefits are generally considered taxable income by the IRS. The state agency that administers unemployment claims will issue a 1099-G form to each recipient, detailing the total amount of unemployment compensation received during the tax year. This includes regular unemployment benefits, as well as any extensions or special pandemic-related unemployment assistance that may have been in place. It’s important for recipients to note that even if they did not receive a 1099-G by mail, they are still responsible for reporting their unemployment income if they received it. Many state unemployment agencies provide online portals where recipients can access their tax information, including their 1099-G.
State and Local Income Tax Refunds, Credits, or Offsets
Another significant category reported on the 1099-G involves refunds, credits, or offsets related to state and local income taxes. If a taxpayer overpaid their state or local income taxes in a prior year and receives a refund in the current tax year, this refund may be taxable. The taxability of a state or local income tax refund hinges on whether the taxpayer itemized deductions on their federal tax return in the year they paid the taxes.
- Itemizers: If you itemized deductions on Schedule A of your federal Form 1040 in the tax year for which you are receiving the refund, and you deducted the state and local income taxes you paid, then the refund you receive in the current tax year is generally taxable. The 1099-G will report the amount of this refund.
- Standard Deduction Users: If you took the standard deduction instead of itemizing your deductions in the prior tax year, your state and local income tax payments were not deducted on your federal return. Therefore, any refund you receive in the current tax year is generally not taxable and will not be reported as taxable income on your 1099-G. However, the refund amount will still be reported on the form for informational purposes.
Similarly, if a taxpayer has outstanding state or local tax liabilities and receives a government payment (such as an unemployment benefit or a tax refund), and a portion of that payment is used to offset the outstanding liability, this offset may also be reported on the 1099-G.
Taxable Grants
Certain taxable grants issued by federal, state, or local governments are also reported on the 1099-G. These grants are typically provided for specific purposes, such as economic development, research, or educational initiatives. The nature of the grant will determine its taxability. If the grant is intended to cover ordinary living expenses or is structured in a way that resembles income, it is more likely to be considered taxable and thus reported on the 1099-G. Recipients should carefully review the terms and conditions of any government grant they receive to understand its tax implications.
Distinguishing Taxable vs. Non-Taxable Payments on 1099-G
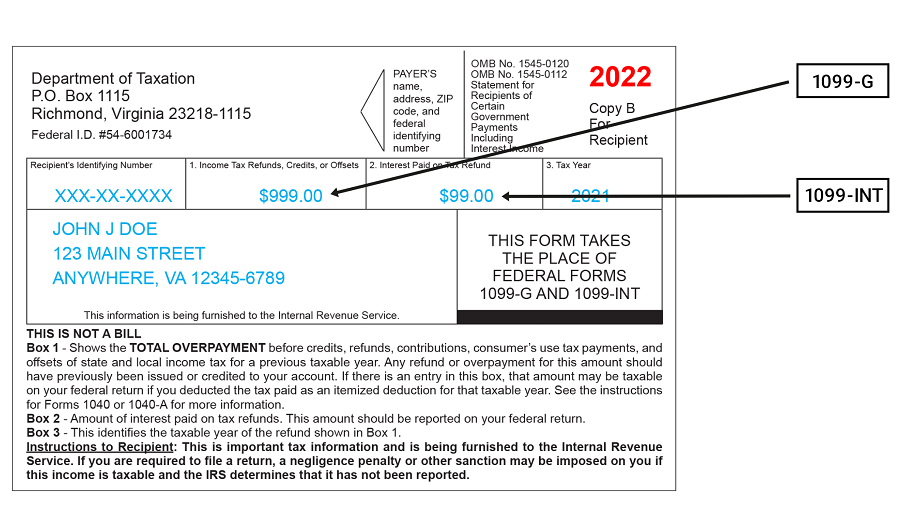
While the 1099-G reports payments from government entities, not all payments listed on the form are necessarily taxable income for every recipient. The form itself often contains specific boxes or codes to indicate the nature of the payment and whether it is considered taxable.
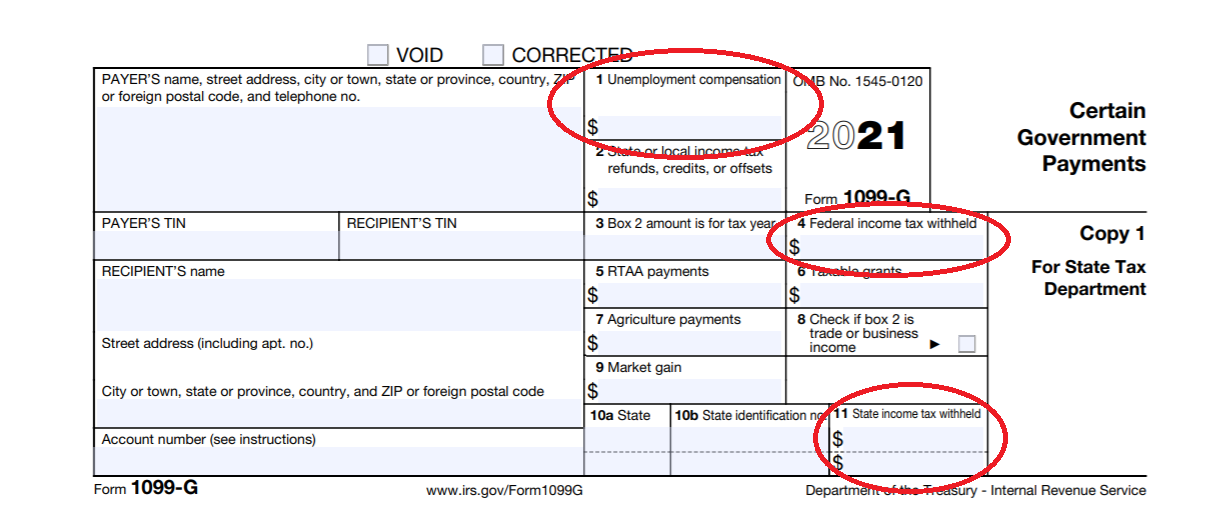
- Box 1: Unemployment Compensation: This box explicitly reports unemployment compensation. As mentioned, this is generally taxable income.
- Box 10: State Income Tax Refunds, Refinds, and Offsets: This box details refunds, credits, or offsets of state income taxes. As discussed, the taxability depends on whether the taxpayer itemized deductions in the prior year.
- Other Boxes: The 1099-G can also include boxes for other government payments, such as taxable grants or agricultural payments. The specific nature of the payment, along with IRS guidance and the recipient’s individual tax situation, will determine its taxability.
It is crucial for recipients to examine the 1099-G carefully upon receipt. If there are any discrepancies or if the recipient believes a reported payment is not taxable, they should contact the issuing government agency immediately to request a corrected form.
The Role of the 1099-G in Tax Preparation
The 1099-G form serves as a vital piece of documentation for accurate tax preparation. When filing your federal income tax return (Form 1040), you will need to report the income detailed on your 1099-G forms.
- Reporting Unemployment Compensation: The amount reported in Box 1 of the 1099-G is typically entered on Schedule 1 (Form 1040), Additional Income and Adjustments to Income, under the line item “Unemployment compensation.” This amount is then carried over to the main Form 1040.
- Reporting State Tax Refunds: For state income tax refunds reported in Box 10, the taxability is determined by whether you itemized deductions in the prior year. If it’s taxable, it is also reported on Schedule 1 (Form 1040). If it’s not taxable, it’s usually not reported as income on your federal return, but you should keep the 1099-G for your records.
- Reporting Other Government Payments: Taxable grants and other government payments will be reported on the appropriate lines of your federal tax return, often on Schedule 1 or directly on Form 1040, depending on the nature of the income.
Tax software and tax professionals will use the information from your 1099-G to accurately populate these sections of your tax return. It is essential to have all your 1099-G forms (and any other income-reporting forms like W-2s, 1099-NECs, 1099-INTs, etc.) readily available when you begin the tax filing process.
Potential Pitfalls and Best Practices
Navigating the 1099-G form can sometimes lead to confusion or errors if not handled carefully. Several pitfalls can arise, and adopting best practices can mitigate these risks.
Common Mistakes
- Ignoring the 1099-G: A common mistake is to overlook or ignore a 1099-G form, especially if the recipient believes the income is not taxable or if they have moved since receiving the payments. This can lead to underreporting income and subsequent penalties from the IRS.
- Misinterpreting Taxability: As highlighted with state tax refunds, the taxability of a payment is not always straightforward. Misinterpreting whether a reported amount is taxable can lead to either overpaying taxes or underreporting income.
- Discrepancies: Sometimes, the amount reported on the 1099-G might not match the recipient’s own records. This could be due to timing differences in reporting, errors by the issuing agency, or incorrect calculations.
- Not Receiving a Form: In some cases, a taxpayer might be entitled to a 1099-G but not receive it by the IRS deadline. This does not absolve them of the responsibility to report the income.
Best Practices
- Keep Records: Maintain detailed records of all government payments received, including dates, amounts, and the purpose of the payment. This will help you verify the information on your 1099-G.
- Review Carefully: Upon receiving a 1099-G, carefully review all the information, paying close attention to the amounts in each box and any accompanying instructions.
- Contact the Issuer Promptly: If you find any errors or believe a reported amount is incorrect or non-taxable, contact the government agency that issued the form immediately. Request a corrected 1099-G.
- Consult a Tax Professional: If you are uncertain about the taxability of any payment reported on a 1099-G, or if you have complex tax situations, consult with a qualified tax professional. They can provide guidance and ensure your tax return is filed accurately.
- Understand State-Specific Rules: While federal tax laws govern the 1099-G, state tax laws can vary regarding the deductibility of state and local income taxes and the taxability of certain state benefits. Familiarize yourself with your state’s specific tax regulations.
- Report All Income: Regardless of whether you receive a 1099-G, you are legally obligated to report all taxable income on your federal tax return. If you received taxable government payments and did not receive a 1099-G, you still need to report that income based on your own records.
In conclusion, the Form 1099-G is a critical reporting document for specific government payments, primarily unemployment compensation and state/local tax refunds. Its purpose is to ensure that these payments are properly accounted for on your tax return, contributing to accurate tax compliance. By understanding the types of payments reported, their potential taxability, and by employing diligent record-keeping and review practices, individuals can navigate the 1099-G with confidence and meet their tax obligations effectively.