
The term “personal liability coverage” within a homeowners insurance policy often brings to mind scenarios like a guest slipping on a wet floor, a dog bite incident, or a child accidentally breaking a neighbor’s window with a baseball. While these traditional examples certainly fall within its scope, the advent of new technologies, particularly the widespread adoption of drones, introduces a complex layer of considerations for property owners and hobbyists alike. For anyone operating an unmanned aerial vehicle (UAV), understanding the nuances of how personal liability coverage in homeowners insurance applies to drone-related incidents is not just insightful, but absolutely critical for financial protection and peace of mind.
The Critical Connection for Drone Enthusiasts and Operators
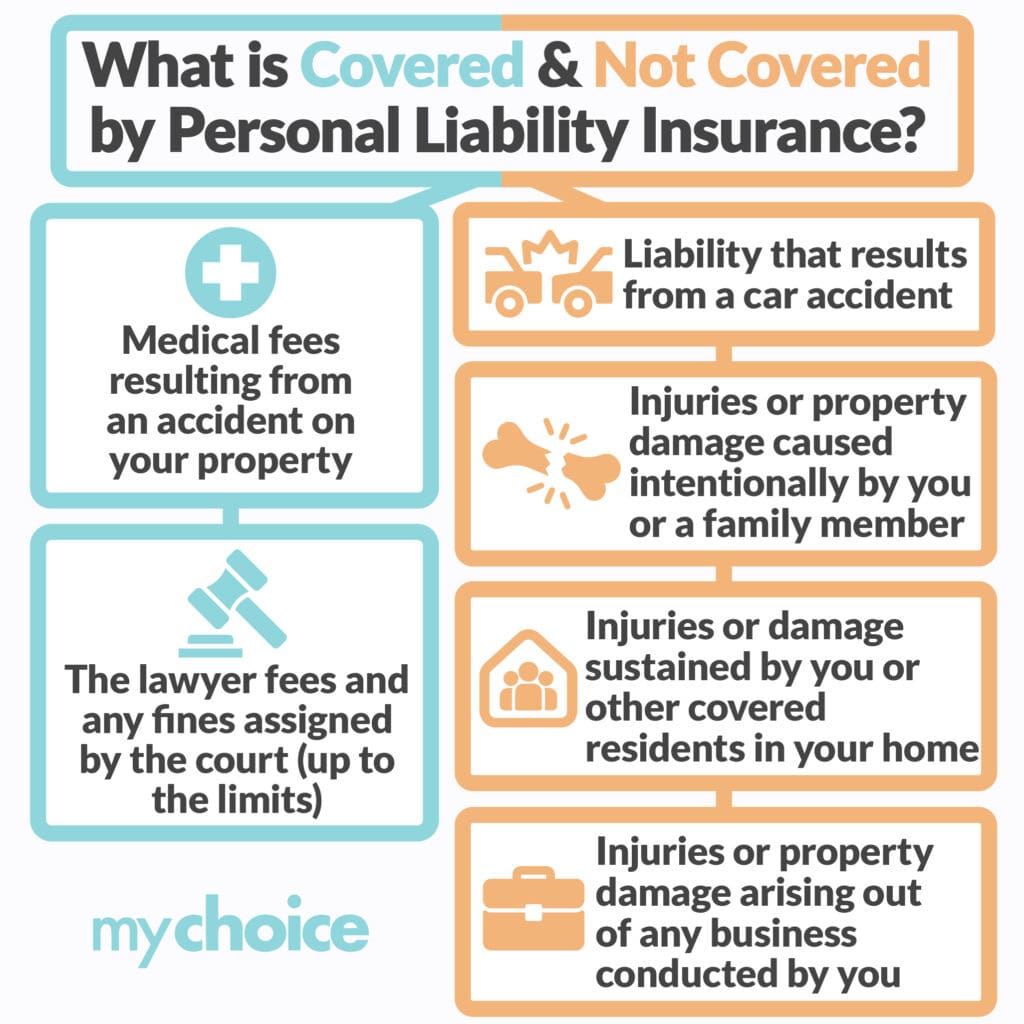
At its core, personal liability coverage in homeowners insurance is designed to protect you financially if you or members of your household are found legally responsible for bodily injury or property damage to another party. This coverage helps pay for legal defense costs, settlements, and judgments up to the policy’s limits. For the drone operator, this foundational protection suddenly becomes paramount.
Imagine a scenario: you are flying your drone recreationally, perhaps capturing stunning aerial footage of a local park. Due to an unexpected gust of wind or a technical malfunction, your drone veers off course. It might crash into a neighbor’s roof, causing significant damage, or worse, fall and injure a bystander. In these situations, your actions—or the actions of your drone—could lead to substantial financial claims against you. Without proper insurance, the costs associated with property repairs, medical bills, legal fees, and potential lawsuits could be crippling.
The growing popularity of drones means that the potential for such incidents, while relatively low on an individual flight, increases collectively. Whether you’re a casual hobbyist, an aspiring aerial photographer, or a professional engaged in commercial drone services, the inherent risks associated with operating an object in shared airspace directly link back to your personal liability. From privacy concerns arising from unintended footage to direct physical damage, the modern drone operator must proactively consider their exposure and how their existing homeowners insurance might—or might not—address it.
Standard Homeowners Policies: A Closer Look at Drone-Related Incidents
Most homeowners insurance policies, typically an HO-3 form, include a personal liability component designed for general, non-business-related incidents. This usually covers events like a visitor being injured on your property, or you accidentally causing damage to someone else’s property away from your home (e.g., your child breaks a window during a playdate). The critical question for drone operators is whether these broad provisions extend to incidents involving UAVs.
The answer, unfortunately, is often complex and varies significantly by insurer and policy specifics, but generally leans towards limited or no coverage for drone-related events. The primary hurdle is often the “aircraft exclusion” clause found in many standard homeowners policies. These clauses typically state that the policy does not cover bodily injury or property damage arising out of the ownership, maintenance, use, loading, or unloading of “aircraft.”
The pivotal point then becomes: Is a drone considered an “aircraft” under the terms of your specific homeowners policy? While the FAA categorizes drones as aircraft, insurance companies may have their own definitions, which can be broad. Many insurers now explicitly interpret drones, especially those over a certain weight threshold (e.g., 250 grams, requiring FAA registration), as falling under this exclusion. This means that if your drone causes damage or injury, your standard homeowners policy might deny the claim outright, leaving you personally responsible for all costs.
Furthermore, if you are using your drone for any commercial purpose—even something as simple as taking photos for a real estate agent for a fee, or using it to assist with your landscaping business—your homeowners policy will almost certainly deny coverage. Standard homeowners policies are strictly for personal, non-business activities, and any incident arising from a commercial enterprise is explicitly excluded under the “business pursuits” clause. This distinction is crucial, as many drone operators blur the lines between hobby and profit, often unknowingly voiding their potential homeowners coverage.
Bridging the Coverage Gap: Beyond Standard Homeowners Insurance
Given the significant limitations of standard homeowners policies when it comes to drones, relying solely on them for protection is a risky gamble. Proactive drone operators must explore supplementary insurance options to ensure comprehensive coverage.
Personal Umbrella Policies (PUPs)
A Personal Umbrella Policy (PUP) provides an additional layer of liability coverage that kicks in after the limits of your underlying policies (like auto or homeowners) are exhausted. It offers broader coverage and higher limits, typically ranging from $1 million to $5 million. While a PUP can be an excellent asset for enhanced protection against various liabilities, its effectiveness for drone incidents hinges on the underlying homeowners policy. If your homeowners policy has an explicit aircraft exclusion that applies to drones, the PUP will generally “follow form” and also exclude drone-related incidents. It’s imperative to review both your homeowners and umbrella policies with an insurance professional to understand their specific exclusions and how they might impact drone operations. Some umbrella policies might offer limited coverage for hobby aircraft, but these provisions are not universal and come with their own specific terms and conditions.
Dedicated Drone Insurance
For most serious drone operators, especially those engaged in commercial activities, dedicated drone insurance is the most robust and reliable solution. These specialized policies are designed specifically for the unique risks associated with UAV operation and offer several key benefits:
- Third-Party Liability: This is the most critical component, covering bodily injury or property damage caused to others by your drone.
- Hull Coverage: Protects the drone itself from damage, loss, or theft. This is especially important for expensive equipment.
- Payload Coverage: Insures specific equipment carried by the drone, such as high-end cameras or sensors.
- Privacy Liability: Covers claims related to invasion of privacy, which can be a significant concern with aerial imaging.
Dedicated drone insurance options range from short-term, on-demand policies (e.g., by the hour or day, often suitable for recreational users or specific projects) to annual commercial policies that provide continuous coverage for businesses. Companies like SkyWatch.AI, Verifly, and others specialize in offering flexible and tailored drone insurance solutions. For any drone activity beyond purely recreational, non-risky flights, investing in dedicated drone insurance is a non-negotiable step.
Homeowners Endorsements or Riders
In some rare instances, a homeowners insurer might offer a specific endorsement or rider that can be added to your policy to provide limited coverage for hobby aircraft. These endorsements are not common, and when available, they often come with strict limitations on drone weight, maximum liability limits, and may still exclude commercial use. Always discuss your drone activities openly and honestly with your insurance agent to determine if such an option exists and if it adequately covers your specific risks. Never assume; always verify with explicit policy language.
Proactive Measures and Informed Drone Operation
Beyond securing appropriate insurance, responsible drone operation involves a commitment to safety, compliance, and ongoing vigilance. These measures not only reduce the likelihood of an incident but can also support your position in the event of an insurance claim.
Regulatory Compliance
Adhering to local, state, and federal regulations is paramount. For recreational flyers in the U.S., this includes passing the FAA’s TRUST aeronautical knowledge and safety test and registering drones weighing over 250 grams. Commercial operators must obtain a Part 107 remote pilot certificate. Always respect no-fly zones, altitude limits, and maintain visual line of sight (VLOS) with your drone. Non-compliance can lead to fines and, critically, may invalidate your insurance coverage if an incident occurs while you are operating unlawfully.
Mitigating Risks
Prior to each flight, conduct thorough pre-flight checks, including battery levels, propeller integrity, GPS signal, and clear flight paths. Avoid flying in adverse weather conditions, over crowds, or near sensitive areas where privacy might be a concern. Practicing safe operating procedures, such as maintaining a safe distance from people and property, is your first line of defense against liability claims.
Documentation
Keeping detailed records can be invaluable. This includes proof of drone purchase and registration, flight logs, maintenance records, and any relevant certifications or authorizations. In the event of an incident, this documentation can help demonstrate responsible operation and adherence to regulations.

Ongoing Review
The landscape of drone technology and regulation is constantly evolving, and so too is the insurance market. It is advisable to regularly review your insurance policies and discuss your drone activities with your insurance agent. As your skills advance, your drone collection grows, or your usage shifts from purely recreational to potentially commercial, your insurance needs will change accordingly. A proactive approach to understanding and securing your personal liability coverage ensures that your passion for drones remains a source of enjoyment, not a financial burden.