
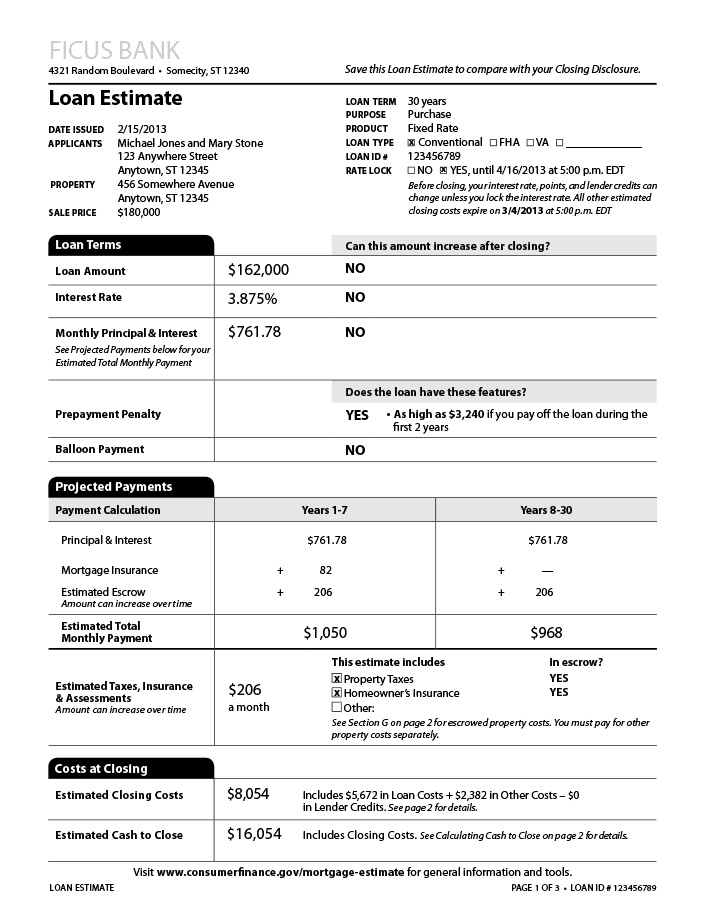
The mortgage process can often feel like navigating a labyrinth of complex terminology and paperwork. Among the most crucial documents a borrower will encounter is the Loan Estimate (LE). This standardized form, mandated by the Consumer Financial Protection Bureau (CFPB) for most residential mortgage applications, serves as a clear and concise snapshot of the proposed loan terms and estimated costs. Understanding the Loan Estimate is paramount for making informed decisions and avoiding unexpected financial burdens. It is not a guarantee of final loan terms, but rather a detailed projection designed to empower consumers with the information they need to compare offers and understand their financial obligations.
Understanding the Loan Estimate: A Foundation for Informed Borrowing
The Loan Estimate is designed to simplify the often-intimidating world of mortgage lending. Its primary purpose is to provide borrowers with a transparent and standardized way to compare loan offers from different lenders. By presenting key information in a consistent format, the LE allows consumers to easily identify differences in interest rates, monthly payments, and closing costs. This standardization is a significant improvement over previous disclosure practices, which often led to confusion and a lack of comparability.
Key Components of the Loan Estimate
The Loan Estimate is divided into several sections, each detailing a specific aspect of the proposed mortgage. Familiarizing oneself with these sections is essential for a comprehensive understanding.
Section A: Loan Terms
This section outlines the fundamental characteristics of the loan itself.
- Loan Amount: This is the principal amount you are borrowing. It’s crucial to ensure this aligns with your purchase price or refinance needs, minus your down payment.
- Interest Rate: This is the annual percentage rate you will pay on the borrowed amount. A lower interest rate generally translates to lower monthly payments and less interest paid over the life of the loan.
- Monthly Principal & Interest (P&I): This figure represents the portion of your monthly payment that goes towards repaying the loan’s principal and the interest accrued.
- Loan Term: This specifies the duration of the loan, typically in years (e.g., 15-year, 30-year fixed).
- Amortization: This describes how your loan will be paid down over time. Most standard mortgages are fully amortizing, meaning that with each payment, a portion goes towards principal and a portion towards interest, gradually reducing the outstanding balance until it reaches zero at the end of the loan term.
- Prepayment Penalties: This indicates whether there are any penalties for paying off your loan early. While not always present, understanding this clause is important for those who may plan to refinance or sell their home in the near future.
- Balloon Payment: This identifies if your loan has a balloon payment, which is a large lump sum payment due at the end of the loan term. These are less common in traditional residential mortgages but are important to note if present.
Section B: Projected Payments
This section provides a clear picture of your anticipated monthly housing expenses.
- Estimated Monthly Payment (P&I): This reiterates the monthly principal and interest payment calculated in Section A.
- Estimated Taxes & Insurance: This is a crucial component as it includes projected amounts for property taxes and homeowners insurance. These are often escrowed, meaning the lender collects these funds monthly and pays them on your behalf when they are due.
- Estimated Mortgage Insurance Premium (MIP) or Private Mortgage Insurance (PMI): If your down payment is less than 20%, you will likely be required to pay for mortgage insurance. This protects the lender in case you default on the loan. The LE will show the estimated monthly cost of this insurance.
- Estimated Other: This catch-all category may include other recurring housing-related costs not covered elsewhere, such as homeowner association (HOA) dues.
- Total Estimated Monthly Payment: This sums up all the individual components to give you a comprehensive view of your expected monthly housing obligation.
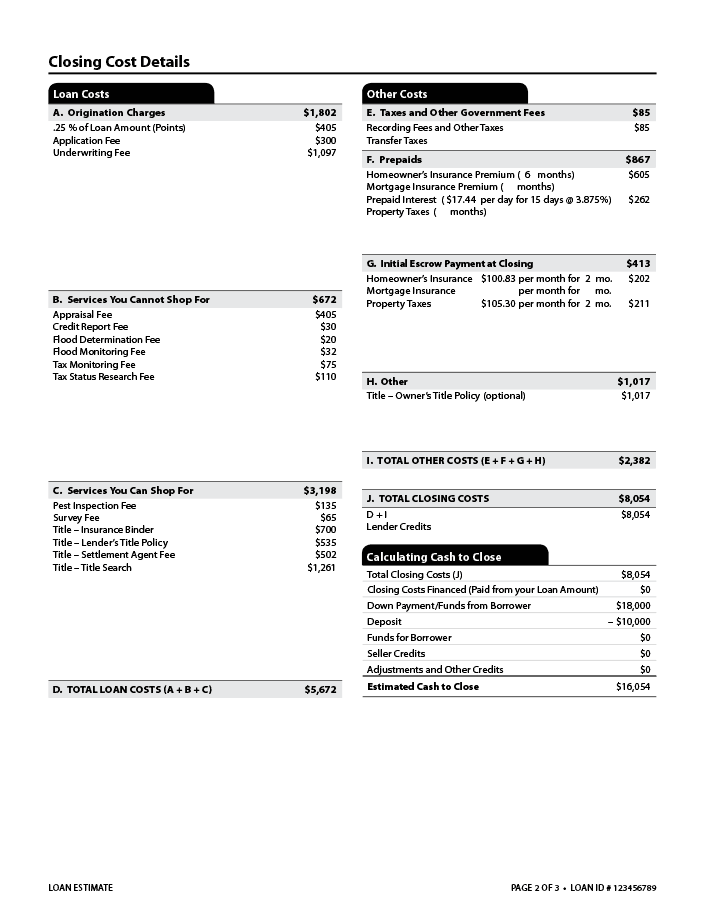
Section C: Estimated Cash to Close
This section is arguably the most critical for understanding the upfront costs associated with obtaining the mortgage.
- Total Estimated Cash to Close: This is the grand total of all the money you’ll need to bring to the closing table. It’s a compilation of various fees and expenses, and it’s essential to scrutinize this figure carefully.
- Loan Costs: This sub-section details the fees charged by the lender and third-party service providers for originating and processing your loan. These can be further broken down into:
- Origination Charges: This includes lender fees for processing the loan, such as origination fees, discount points, and application fees.
- Services You Cannot Shop For: These are services where the lender selects the provider, and you are generally obligated to use them. Examples include credit report fees, appraisal fees, and flood determination fees. The LE will list the cost for each of these services.
- Services You Can Shop For: These are services where you have the option to choose your own provider, potentially saving money. Common examples include title insurance, title search, settlement agent fees, and pest inspections. The LE will list estimated costs for these services, and you are encouraged to compare prices from different providers.
- Other Costs: This section encompasses expenses beyond the direct loan costs.
- Prepaid Items: These are costs you pay in advance, such as prepaid interest from the closing date to the end of the month, homeowners insurance premiums, and property taxes.
- Initial $text{P}+text{I}+$ (Principal and Interest) Payment: This indicates the first principal and interest payment you’ll make after closing.
- Reserves: This refers to amounts held by the lender in an escrow account to cover future property taxes and homeowners insurance premiums. It typically includes a certain number of months’ worth of these payments.
- Down Payment and Other Credits: This section clearly shows the amount of your down payment and any other credits you may receive from the seller or lender. The difference between the “Total Estimated Cash to Close” and these credits will be the net amount you need to pay.
The Importance of the Loan Estimate in Comparison and Negotiation
The Loan Estimate is not just a formality; it’s a powerful tool for consumers. Its standardized format is specifically designed to facilitate comparison shopping. When you receive Loan Estimates from multiple lenders, you can lay them side-by-side and immediately identify key differences.
Comparing Lender Offers
When comparing Loan Estimates, pay close attention to:
- Interest Rate: Even a small difference in interest rate can lead to significant savings over the life of a 30-year mortgage.
- Annual Percentage Rate (APR): The APR provides a more comprehensive picture of the loan’s cost by factoring in not only the interest rate but also many of the fees associated with the loan. A lower APR generally indicates a less expensive loan.
- Closing Costs: Carefully examine the “Estimated Cash to Close” and the individual “Loan Costs” and “Other Costs.” Look for significant discrepancies between lenders. If one lender has substantially higher closing costs, inquire about the specific fees contributing to that difference.
- Lender Credits: Some lenders may offer credits to offset closing costs, which can be reflected in the “Down Payment and Other Credits” section. These can effectively lower your upfront cash requirement.
Negotiating Your Mortgage
Armed with multiple Loan Estimates, you gain leverage for negotiation. If you receive a compelling offer from one lender but another offers a slightly better rate or lower fees, you can present the more favorable terms to the other lender and see if they are willing to match or beat them. Lenders are often willing to negotiate, especially in a competitive market, to secure your business.
Understanding Tolerance Levels and the Closing Disclosure
The Loan Estimate is a projection, and some costs may change between the issuance of the LE and the final closing. The CFPB has established “tolerance levels” for certain fees to protect consumers from significant increases.
Tolerance Levels Explained
- Zero Tolerance Fees: These are costs that cannot increase at all from the Loan Estimate to the Closing Disclosure without a valid changed circumstance. Examples include the application fee, credit report fee, and appraisal fee if you choose the lender’s provider.
- 10 Percent Tolerance Fees: These are costs that can increase by a maximum of 10% from the Loan Estimate to the Closing Disclosure. This category typically includes services where you can shop for a provider, such as title insurance and settlement services.
- Unlimited Tolerance Fees: These are costs that can change significantly, with no set tolerance limit. This usually includes prepaid interest, property taxes, and homeowners insurance premiums, as these can fluctuate based on market conditions or your specific choices.
The Role of the Closing Disclosure
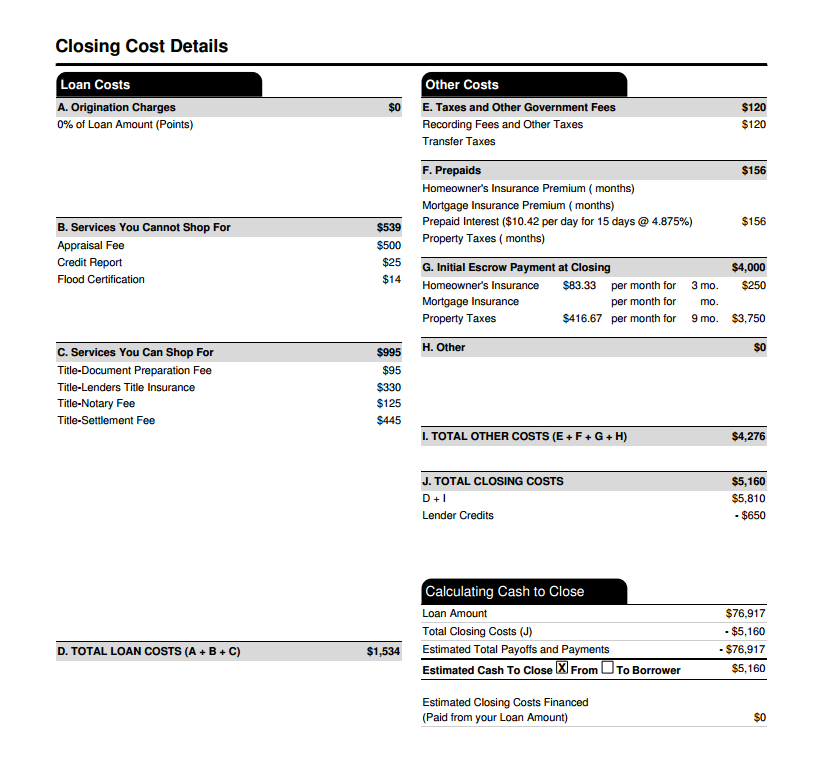
The Closing Disclosure (CD) is the final document that details all the terms and costs of your loan. It is provided to you at least three business days before your scheduled closing. The CD must be compared to your Loan Estimate, and any significant discrepancies should be questioned immediately. This three-day window is crucial for reviewing the CD and ensuring that the final costs and terms align with what was presented in the Loan Estimate and any subsequent revised Loan Estimates. If there are substantial differences or if you are uncomfortable with the final figures, you have the right to address them with your lender before completing the transaction.
Conclusion: Your Roadmap to a Successful Mortgage
The Loan Estimate is more than just a piece of paper; it’s an essential guide that empowers you throughout the mortgage application process. By thoroughly understanding its components, actively comparing offers from different lenders, and diligently reviewing the final Closing Disclosure, you can navigate the complexities of mortgage lending with confidence. This document is your first and most important step towards securing a loan that aligns with your financial goals and ensures a smooth path to homeownership.