
The concept of an Individual Retirement Arrangement (IRA) rollover is a fundamental aspect of long-term financial planning, particularly for individuals transitioning between jobs or seeking to consolidate their retirement savings. At its core, an IRA rollover is the process of moving funds from one retirement account to another without incurring immediate taxes or penalties. This allows individuals to maintain the tax-advantaged status of their retirement savings while potentially gaining more control, flexibility, and a wider range of investment options. Understanding the nuances of IRA rollovers is crucial for ensuring that retirement nest eggs remain secure and continue to grow effectively over time.

Understanding the Fundamentals of IRA Rollovers
An IRA rollover is not a new account, but rather a mechanism for transferring funds from an existing retirement savings plan into an IRA. This can occur in several scenarios, the most common being the transition from an employer-sponsored retirement plan, such as a 401(k), 403(b), or 457(b), to an IRA. It can also involve moving funds between different types of IRAs, such as from a Traditional IRA to another Traditional IRA, or from a Roth IRA to another Roth IRA. The key objective is to preserve the tax-deferred or tax-free growth of the retirement assets.
Types of Retirement Accounts Involved in Rollovers
The most frequent type of rollover involves moving funds from an employer-sponsored plan to an IRA. These employer-sponsored plans are established and maintained by an employer for the benefit of their employees. Upon leaving an employer, individuals often face a decision regarding the fate of their accumulated retirement funds. Instead of leaving the money in a former employer’s plan, which may have limited investment choices or higher fees, or cashing out the funds (which would result in significant taxes and penalties), a rollover to an IRA becomes an attractive option.
Alternatively, individuals may choose to roll over funds from one IRA to another. This is commonly done to consolidate multiple IRAs into a single account for easier management, or to move to an IRA provider that offers better investment options, lower fees, or enhanced customer service. It is important to note that the type of IRA must generally be maintained. For instance, a Traditional IRA rollover typically goes into another Traditional IRA, and a Roth IRA rollover goes into another Roth IRA. Mixing these types without following specific conversion rules can lead to adverse tax consequences.
The Process of an IRA Rollover
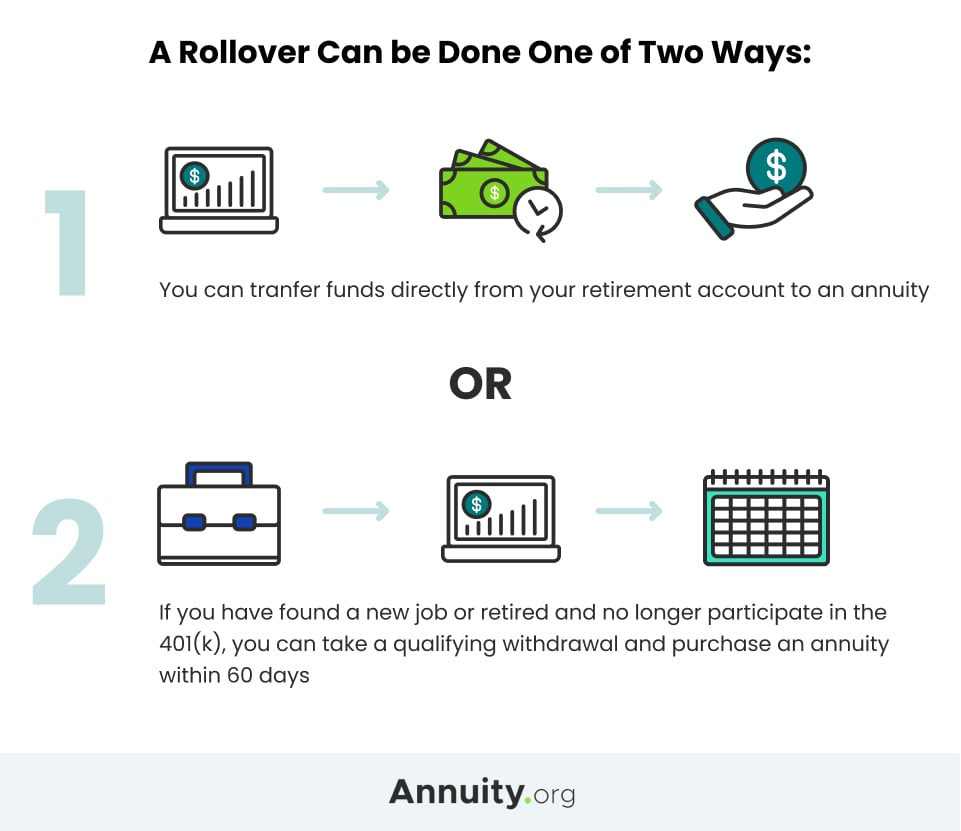
There are two primary methods for executing an IRA rollover: the direct rollover and the indirect rollover. Each method has distinct procedures and implications for the individual involved.
Direct Rollover
A direct rollover is generally considered the preferred method for most individuals. In a direct rollover, the funds are transferred directly from the trustee of the old retirement plan to the trustee of the new IRA. The money never passes through the individual’s hands. This is typically facilitated by the financial institutions involved. The old plan administrator will send a check made out to the new IRA custodian, or initiate an electronic transfer. The advantage of a direct rollover is that it completely avoids the 60-day rollover period requirement and eliminates the risk of accidentally missing the deadline, which would trigger taxes and penalties.
Indirect Rollover
An indirect rollover involves the distribution of funds from the old retirement plan directly to the individual. The individual then has 60 days from the date of distribution to deposit the funds into a new IRA. A critical aspect of the indirect rollover is the mandatory 20% withholding tax that the plan administrator is required to deduct from the distribution. This means that if an individual receives a check for $10,000 from their 401(k), only $8,000 will be handed to them. To complete the rollover in full, the individual must deposit the full $10,000 into their IRA within the 60-day window. This requires them to use funds from other sources to cover the withheld $2,000. If they fail to deposit the full amount within the 60 days, the $2,000 withheld will be considered a taxable distribution, and if the individual is under age 59½, they may also be subject to a 10% early withdrawal penalty on the entire $10,000.
Benefits of an IRA Rollover
The decision to roll over retirement assets into an IRA is driven by a multitude of advantages that can significantly impact an individual’s financial well-being in retirement. These benefits primarily revolve around increased control, investment flexibility, and potential cost savings.
Enhanced Investment Options
One of the most compelling reasons for an IRA rollover is the expanded universe of investment choices. Employer-sponsored plans, while offering a curated selection of investments, often have limitations. IRAs, on the other hand, generally provide access to a far broader array of investment vehicles, including individual stocks, bonds, mutual funds, exchange-traded funds (ETFs), certificates of deposit (CDs), and even alternative investments. This expanded choice allows individuals to tailor their investment portfolio to their specific risk tolerance, financial goals, and time horizon, potentially leading to greater returns.
Greater Control Over Investments
Beyond the sheer number of options, IRAs offer individuals greater direct control over their investment decisions. In an employer-sponsored plan, the investment choices are typically made by the plan fiduciaries, and while employees can select from the available options, they do not have the autonomy to dictate specific investment strategies or select individual securities beyond what the plan permits. With an IRA, the account holder becomes the de facto investment manager, empowered to make all decisions regarding asset allocation, security selection, and rebalancing of the portfolio. This level of autonomy is particularly appealing to individuals who are knowledgeable about investing or who wish to actively manage their retirement assets.
Potential for Lower Fees
Fees associated with retirement plans can significantly erode investment returns over time. Employer-sponsored plans may have administrative fees, record-keeping fees, and investment management fees that can be higher than those found in IRAs, especially with discount brokerage firms. By rolling over assets into an IRA, individuals can often find accounts with lower overall fees, particularly if they opt for low-cost index funds or ETFs. Minimizing these costs can lead to substantial long-term savings and a larger retirement nest egg.
Consolidation of Retirement Assets
For individuals who have held multiple jobs throughout their careers, they may find themselves with several small retirement accounts scattered across different employers. This can be a logistical headache, making it difficult to track performance, manage investments, and ensure that savings are adequately diversified. An IRA rollover allows for the consolidation of these disparate accounts into a single IRA, simplifying administration, making it easier to monitor progress, and providing a clearer picture of overall retirement readiness.
Considerations and Potential Pitfalls
While IRA rollovers offer numerous advantages, it is imperative to approach the process with careful consideration and an awareness of potential pitfalls. Missteps can lead to unintended tax liabilities and penalties, negating the benefits of the rollover.
The 60-Day Rule and Withholding Taxes
As previously discussed, the 60-day rule for indirect rollovers is a critical deadline. Missing this deadline, even by a single day, can have severe tax consequences. The 20% mandatory withholding tax in indirect rollovers also presents a challenge. Individuals must be prepared to cover this amount from other savings to ensure the full amount is rolled over. Failure to do so means the withheld portion is treated as a taxable distribution.
Direct vs. Indirect Rollover Choice
The choice between a direct and indirect rollover is a significant one. While direct rollovers bypass the 60-day rule and the withholding tax issue, indirect rollovers require more active management by the individual. For those who are confident in their ability to meet the 60-day deadline and manage the withholding tax, an indirect rollover might be a viable option. However, for the majority of individuals, the simplicity and security of a direct rollover make it the more prudent choice.
Types of IRAs and Conversions
It is crucial to understand the difference between Traditional and Roth IRAs. A Traditional IRA offers tax-deferred growth, meaning taxes are paid upon withdrawal in retirement. A Roth IRA offers tax-free growth and tax-free withdrawals in retirement, provided certain conditions are met. Rollovers typically involve moving like-for-like accounts (Traditional to Traditional, Roth to Roth). Conversions from Traditional to Roth IRAs are possible, but these trigger an immediate taxable event in the year of conversion, as the pre-tax contributions and earnings in the Traditional IRA are taxed as ordinary income. This is a strategic decision that requires careful tax planning.
Fees and Investment Choices in the New IRA
Before initiating a rollover, it is essential to research and select an IRA provider that offers competitive fees and a suitable range of investment options. Not all IRAs are created equal. Some may have high administrative fees, transaction costs, or limited investment platforms. Choosing wisely upfront can prevent costly mistakes and ensure the new IRA aligns with the individual’s financial objectives. Understanding the fee structure, including advisory fees, account maintenance fees, and trading commissions, is paramount.
Required Minimum Distributions (RMDs)
For individuals who are already taking Required Minimum Distributions (RMDs) from their employer-sponsored plan, or who are approaching the age when RMDs begin (currently age 73, though subject to change by legislation), the timing of a rollover needs careful consideration. RMD rules also apply to IRAs, and failing to take them can result in significant penalties. It is advisable to consult with a financial advisor or tax professional to understand how RMDs will be affected by a rollover.
Rolling Over into Different Account Types
While the most common IRA rollover involves moving funds from an employer-sponsored plan into a Traditional or Roth IRA, there are other variations and considerations to be aware of.
Inherited IRAs
When an individual inherits an IRA from a deceased spouse or other beneficiary, specific rules apply to how those funds can be managed. A surviving spouse typically has the option to treat the inherited IRA as their own, which can allow for continued tax-deferred growth and the ability to delay RMDs until they themselves reach the age of RMD eligibility. Non-spouse beneficiaries have more stringent rules, often requiring distributions within a 10-year period under current legislation. Rollovers into an inherited IRA must adhere to these specific beneficiary distribution rules.
Self-Directed IRAs (SDIRAs)
For individuals seeking an even broader range of investment possibilities, a Self-Directed IRA (SDIRA) may be an option. SDIRAs allow for investments in alternative assets such as real estate, precious metals, private equity, and cryptocurrency, beyond traditional stocks and bonds. While this offers significant flexibility, it also comes with a higher degree of complexity and responsibility. The administrator of an SDIRA typically only handles the administrative and custodial duties, with the account holder making all investment decisions. Due diligence and a thorough understanding of prohibited transactions and IRS regulations are critical when considering an SDIRA.

Conclusion: Strategic Retirement Planning Through Rollovers
The IRA rollover is a powerful financial tool that empowers individuals to take greater control of their retirement savings. By understanding the mechanics of direct and indirect rollovers, the benefits of enhanced investment options, and the potential pitfalls, individuals can make informed decisions that safeguard and grow their retirement nest egg. Whether moving funds from a former employer’s plan or consolidating existing IRAs, a well-executed rollover is a cornerstone of sound retirement planning, ensuring that financial goals are met and a secure future is secured. Consulting with a qualified financial advisor or tax professional is always recommended to navigate the complexities of IRA rollovers and to ensure compliance with all relevant regulations.