
The W-2 form, officially known as the Wage and Tax Statement, is a crucial document issued annually by employers to employees and the Internal Revenue Service (IRS). It details the wages earned and the taxes withheld from an employee’s paycheck throughout the year. While most employees are familiar with the primary boxes that report their gross pay, federal income tax, Social Security tax, and Medicare tax, there are several other boxes designed to report various types of compensation and deductions. Box 12 of the W-2 is a particularly important and sometimes complex section, as it’s used to report a wide array of specific items that can impact an employee’s tax liability. Among the many codes that can appear in Box 12, “DD” is one that frequently prompts questions.
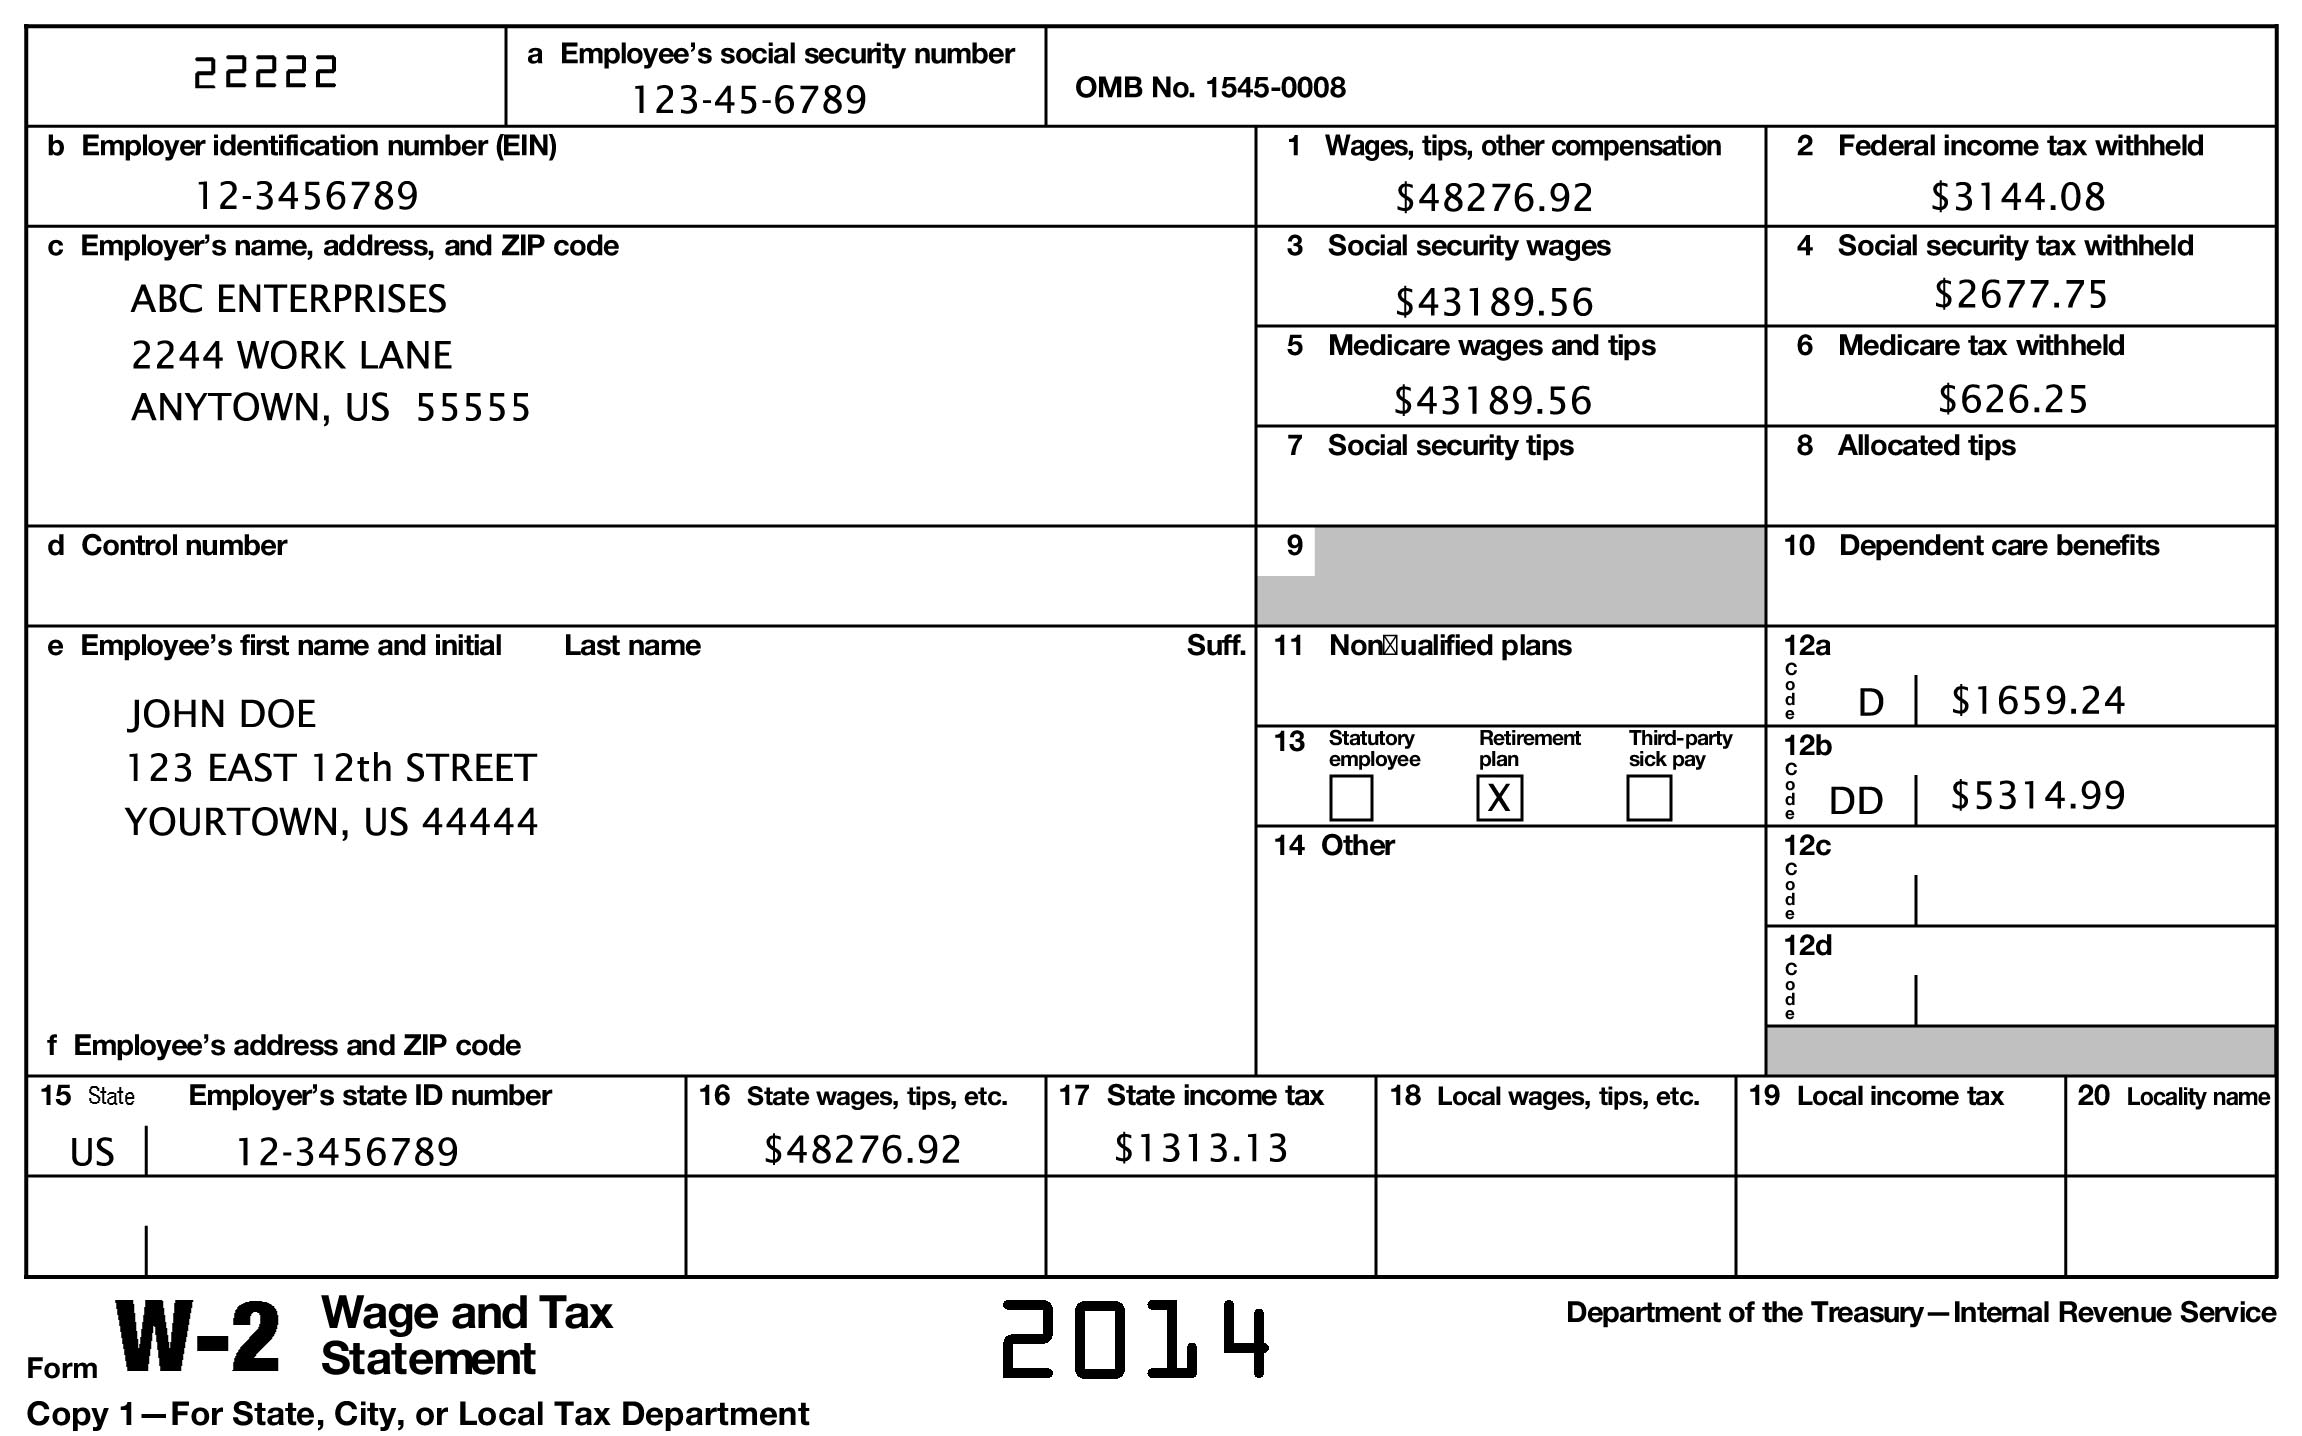
Understanding the “DD” code requires delving into the specifics of employer-provided health coverage and its tax implications. This section is not about a direct deduction from an employee’s pay in the traditional sense, but rather a reporting mechanism for the cost of that coverage.
Understanding Box 12 Codes
Box 12 of the W-2 form serves as a repository for a variety of codes that represent specific types of compensation, benefits, or withholding amounts that do not fit neatly into the main boxes of the form. Each code is paired with a dollar amount, providing a detailed breakdown of an employee’s earnings and benefits. The IRS assigns these codes to ensure accurate reporting and to help taxpayers understand their tax obligations. Some of the most common codes include:
- Code A: Uncollected Social Security or Medicare tax on tips.
- Code B: Social Security tax on tips.
- Code C: Taxable cost of group-term life insurance over $50,000.
- Code D: Elective deferrals to a Section 401(k) cash or deferred arrangement.
- Code E: Elective deferrals under a Section 403(b) salary reduction agreement.
- Code F: Elective deferrals under a Section 408(k)(6) salary reduction simplified employee pension (SARSEP) plan.
- Code G: Elective deferrals and employer contributions to a Section 457(b) deferred compensation plan.
- Code H: Elective deferrals to a Section 501(c)(18)(D) tax-exempt organization plan.
- Code J: Health Savings Account (HSA) contributions made by the employee through payroll deduction.
- Code P: Excludable moving expense reimbursements paid directly to the employee.
- Code S: Employee stock options.
- Code W: Employer contributions to a Section 401(k) cash or deferred arrangement.
- Code EE: Thorne-a-thon Savings Plan.
- Code FF: Archer MSA contributions by the employee.
The “DD” code, however, stands apart from many of these as it doesn’t represent a taxable event for the employee in the same way. Its purpose is primarily informational.
The Meaning of Code DD: Cost of Employer-Sponsored Health Coverage
The “DD” code in Box 12 of your W-2 form indicates the total cost of employer-sponsored health coverage. This amount includes both the portion paid by your employer and the portion paid by you through payroll deductions (pre-tax or after-tax). It’s crucial to understand that reporting this amount in Box 12 is generally for informational purposes only and is not typically considered taxable income to the employee.
The Affordable Care Act (ACA) mandated the reporting of this cost starting with the 2012 tax year for employers with 250 or more employees. The intention behind this reporting was to provide employees with a clearer picture of the value of the health benefits their employer provides. For many employees, the cost of health insurance premiums can be a significant portion of their compensation package, and seeing this figure on their W-2 can offer a better understanding of their total compensation.
What Constitutes “Employer-Sponsored Health Coverage”?
The “Cost of Employer-Sponsored Health Coverage” reported under code DD encompasses a broad range of health benefits provided by your employer. This typically includes:
- Medical Insurance: Premiums for health insurance plans offered by your employer.
- Dental Insurance: Premiums for dental insurance plans.
- Vision Insurance: Premiums for vision insurance plans.
- Health Savings Accounts (HSAs) and Health Reimbursement Arrangements (HRAs): Employer contributions to these accounts are often included in this cost.
- Prescription Drug Coverage: Premiums associated with prescription drug plans.
It’s important to note that the amount reported under DD does not necessarily represent the actual amount you paid out-of-pocket for healthcare services. Instead, it reflects the overall premium cost of the coverage you received through your employer.
Why is DD Informational and Not Taxable?
The reason the cost of employer-sponsored health coverage is generally not taxed is due to established tax laws that favor employer-provided health benefits. For most employees, the premiums for employer-sponsored health insurance that are paid on a pre-tax basis are excludable from their gross income. This means that these contributions reduce your taxable income for the year.
The “DD” code serves to highlight this benefit. By reporting the total cost, the IRS and the employee can see the value of this significant employee benefit, even though it doesn’t directly add to the employee’s tax liability. It can be a valuable piece of information when comparing job offers or evaluating the total compensation package of a current employer.
When Might DD Amount to Taxable Income?
While typically informational, there are specific circumstances where the amount reported under “DD” might have tax implications. These are exceptions rather than the rule:
- When Coverage is Not Qualified: If the health coverage provided by your employer does not meet certain IRS requirements for qualified health plans, the cost might be considered taxable income. However, most standard employer-sponsored health plans are designed to meet these requirements.
- Employer Contributions to HSAs/HRAs Above Certain Limits: While employer contributions to HSAs and HRAs are often reported under DD, the amounts above specific statutory limits could be considered taxable income if not properly managed or distributed.
- Imputed Income for Group-Term Life Insurance: While group-term life insurance over $50,000 is reported with code C, it’s important to distinguish that the cost of health coverage (DD) is generally not treated this way.
For the vast majority of employees, the figure in Box 12 with the code “DD” will represent a non-taxable benefit.
How to Use the Information from Box 12 DD
The information provided by the “DD” code on your W-2 is primarily for your awareness and to help you understand the full scope of your employment benefits. Here are some practical ways to utilize this information:
1. Understanding Your Total Compensation Package
Your salary is only one part of your overall compensation. Benefits, such as health insurance, represent a substantial portion of the value an employer provides. The “DD” code quantifies this value, allowing you to see the true cost of the health coverage you receive. This can be particularly useful when:
- Negotiating Salary and Benefits: Understanding the monetary value of your health benefits can strengthen your position when discussing compensation.
- Evaluating Job Offers: When comparing offers from different employers, the “DD” figure can help you assess which package is more financially beneficial overall.
- Budgeting and Financial Planning: Knowing the approximate cost of your employer-provided health coverage can aid in personal financial planning, especially if you anticipate needing to cover the full cost of insurance in the future (e.g., if you leave your employer).
2. Comparing Health Insurance Costs Over Time
If you’ve been with the same employer for several years, reviewing the “DD” amounts on past W-2 forms can reveal trends in the cost of your health coverage. This can help you understand how premiums have changed and potentially identify situations where your share of the cost has increased disproportionately.
3. Estimating Future Healthcare Costs
While the “DD” code reports the premium cost and not direct healthcare expenses, it provides a baseline for understanding the cost of health coverage. If you anticipate a future scenario where you might have to purchase health insurance on your own, such as during a period of unemployment or if you opt for COBRA coverage, the “DD” amount can serve as a starting point for estimating those future expenses.
4. Informing Your Tax Preparer
While the “DD” amount is usually non-taxable, it’s still a piece of information your tax preparer will want to see. They can confirm its non-taxable status and ensure it’s correctly interpreted within the context of your entire tax return. They may also use this information to verify that your employer has correctly classified and reported your benefits.
Distinguishing DD from Other Box 12 Codes
It’s essential to differentiate the “DD” code from other codes in Box 12, especially those that do represent taxable income or deductions.
- Codes D, E, F, G, H: These codes relate to elective deferrals to retirement plans like 401(k)s, 403(b)s, SARSEPs, 457(b)s, and 501(c)(18)(D) plans. These amounts are typically pre-tax and reduce your taxable income for the year, but they represent contributions to your retirement savings, not the cost of health coverage.
- Code J: This code reports HSA contributions made by the employee through payroll deduction. While HSAs are related to healthcare, Code J specifically details your contributions, whereas DD details the total cost of employer-sponsored coverage.
- Code P: This code represents excludable moving expense reimbursements. This is a reimbursement for relocation costs and is distinct from health coverage costs.
- Code S: This code signifies employee stock options. This relates to equity compensation and has no bearing on health benefits.
- Code W: This code indicates employer contributions to a Section 401(k) cash or deferred arrangement. This is an employer contribution to your retirement, not a health benefit cost.
The key distinction for “DD” is its informational nature concerning the cost of health insurance, which is generally a tax-advantaged benefit.
Conclusion
The “DD” code in Box 12 of your W-2 form is a valuable piece of information for understanding the financial aspect of your employer-provided health coverage. While it typically does not affect your tax liability directly, it provides transparency into the total cost of your benefits package. By understanding what this code represents, you can better assess your overall compensation, make informed financial decisions, and engage in more productive conversations about your benefits with your employer and tax professional. Always review your W-2 carefully and consult with a tax advisor if you have any specific questions or concerns about the codes and amounts reported.