
Dark pool trading represents a fascinating and often controversial innovation within the modern financial landscape, operating at the intersection of sophisticated technology and market structure. At its core, a dark pool is a privately operated electronic trading system or alternative trading system (ATS) that allows institutional investors to execute large-block trades without the public display of their orders. Unlike traditional “lit” exchanges, where bids and offers are openly visible before execution, dark pools maintain an opaque order book, revealing trade details only after the transaction is completed. This characteristic opacity is the origin of the term “dark pool.”
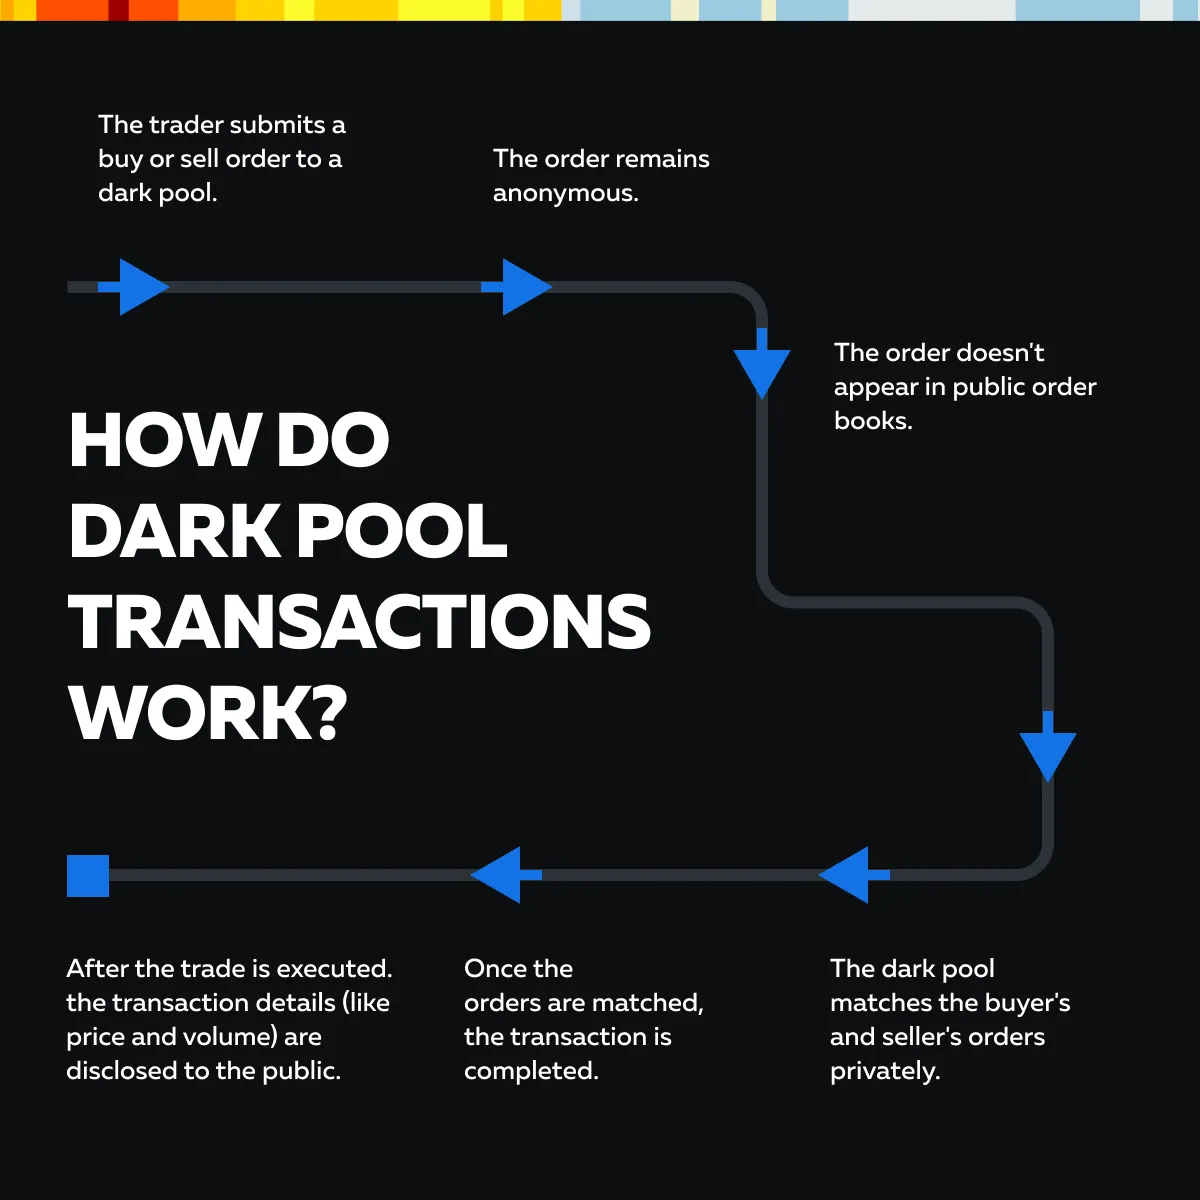
The advent of dark pools is deeply rooted in the technological advancements that transformed financial markets from manual outcry systems to highly automated, electronic platforms. As markets became more fragmented and trading speeds accelerated, institutional investors faced a growing challenge: executing significant orders without inadvertently signaling their intentions to the broader market. Such signals could lead to adverse price movements, a phenomenon known as market impact or information leakage, where high-frequency traders (HFTs) or other sophisticated participants could front-run large orders, causing the institutional investor to buy at higher prices or sell at lower prices. Dark pools emerged as a technological solution to mitigate this risk, offering a discrete environment for major players to find liquidity and execute trades with minimal footprint.
The Genesis of Off-Exchange Trading
The proliferation of dark pools began to accelerate in the early 21st century, particularly following regulatory changes like Regulation NMS (National Market System) in the U.S. and MiFID (Markets in Financial Instruments Directive) in Europe, which aimed to promote competition among trading venues. These regulations inadvertently fostered a more fragmented market structure, creating fertile ground for off-exchange venues. Prior to this, large block trades often occurred via “upstairs trading” desks at investment banks, which essentially served a similar function but lacked the electronic automation and scale of modern dark pools.
The technological shift from physical trading floors to electronic networks created both opportunities and challenges. While electronic trading brought efficiency and speed, it also heightened the risk of information leakage for large orders in transparent markets. Institutional investors, managing vast sums of capital, needed a mechanism to buy or sell millions of shares without immediately influencing the visible market price against their own interests. For instance, a pension fund looking to sell a substantial block of shares in a particular company might find that advertising its intent on a public exchange would cause the stock price to drop prematurely, leading to a less favorable execution. Dark pools offered an environment where such large orders could be matched with minimal market impact, by ensuring that the existence of an order is only known to the matching engine until execution.
The fundamental distinction lies in the pre-trade transparency. On a lit exchange, anyone can see the best bid and offer, as well as the depth of the order book. In a dark pool, this information is not publicly displayed. Only the dark pool operator and the participants whose orders are matched know the details prior to execution. This lack of pre-trade transparency is the defining characteristic that separates dark pools from traditional exchanges and alternative trading systems that choose to display their order books.
Technological Backbone and Algorithmic Execution
The operation of a dark pool is inherently dependent on cutting-edge technology. These systems require robust, low-latency infrastructure capable of processing vast numbers of orders and matching them efficiently. High-speed data networks, powerful servers, and sophisticated matching engines form the technological backbone, ensuring rapid and precise trade execution. The innovation in this domain centers around the algorithms that govern order matching, liquidity aggregation, and even the protection mechanisms against predatory trading strategies.
Modern dark pools employ complex algorithms to determine how orders are matched, often incorporating various rules designed to prioritize certain types of liquidity or protect participants. For example, some dark pools might prioritize price-time, while others might focus on larger orders or specific participant types. The sheer computational power and algorithmic sophistication involved place dark pools firmly within the realm of “Tech & Innovation.” Many dark pools also leverage advanced analytical techniques, potentially including machine learning algorithms, to forecast liquidity, detect unusual trading patterns, or optimize their matching processes, further solidifying their status as technologically advanced trading venues.
High-Frequency Trading (HFT) and Dark Pools
Paradoxically, while dark pools were partly conceived to shield institutional orders from aggressive high-frequency trading (HFT) strategies, HFT firms themselves are significant participants in many dark pools. HFTs utilize their own highly sophisticated algorithms and ultra-low-latency connections to detect and capitalize on available liquidity, even within opaque venues. They deploy complex strategies to probe dark pools for potential large orders, using statistical arbitrage, market making, and order book analysis.
The relationship between HFT and dark pools creates a continuous technological arms race. Institutions investing in dark pools seek to protect their orders from HFT predatory tactics, while HFTs continually refine their algorithms to find an edge. This dynamic drives further innovation in matching engine design, anti-gaming algorithms, and order routing strategies, pushing the boundaries of what is possible in electronic trading.

Smart Order Routing and Liquidity Aggregation
For many participants, especially large broker-dealers, dark pools are not standalone trading venues but rather integral components of a larger, technologically integrated market microstructure. Broker-dealers employ “smart order routers” (SORs) – highly complex algorithms that automatically determine the optimal venue for an order’s execution. These SORs scan a multitude of trading destinations, including lit exchanges, other ATSs, and various dark pools, to find the best possible price and liquidity for their clients.
The technology behind smart order routing is incredibly advanced. It involves real-time data analysis, predictive modeling of liquidity, and rapid decision-making across dozens or even hundreds of potential venues. Dark pools contribute to this ecosystem by offering alternative liquidity sources that SORs can tap into, especially for larger orders. The aggregation of liquidity, whether from a single dark pool or across multiple dark and lit venues, is a testament to the seamless integration and technological sophistication that characterizes modern financial markets. This aggregation aims to ensure that even the largest orders can be filled efficiently without causing undue market disruption.
Regulatory Landscape and Transparency Concerns
The innovative nature of dark pools, particularly their lack of pre-trade transparency, has presented significant challenges for regulators globally. While dark pools aim to solve a legitimate market problem for institutional investors, their opaque operations raise questions about fairness, market integrity, and the overall efficiency of price discovery. In the U.S., dark pools operate under the SEC’s Regulation ATS (Alternative Trading Systems), which mandates certain reporting requirements but allows for the non-display of orders.
The regulatory challenge lies in balancing the benefits of dark pools—such as reduced market impact for large trades and potentially lower transaction costs—with the potential drawbacks related to transparency. Regulators worldwide have grappled with how to oversee these venues, ensure equitable access, and prevent potential abuses or conflicts of interest. The ongoing debate often centers on whether dark pools detract from the integrity of public price formation or enhance overall market stability by absorbing large, disruptive trades away from lit markets.
Market Fragmentation and Price Discovery
One of the most persistent criticisms leveled against dark pools is their alleged contribution to market fragmentation and the potential hindrance to efficient price discovery. When a significant portion of trading volume occurs away from public exchanges, it raises concerns that the prices observed on lit markets may not fully reflect the true supply and demand dynamics. If the best prices are hidden within dark pools, traditional exchanges may not provide the most accurate or comprehensive price signals.
However, proponents argue that dark pools actually contribute positively to price discovery by preventing large block trades from immediately distorting prices on public exchanges. By allowing institutions to execute trades discreetly, dark pools absorb potential price pressure that would otherwise manifest on lit markets, leading to temporary but significant price dislocations. In this view, dark pools act as a crucial ‘shock absorber,’ maintaining overall market stability and preventing large orders from creating artificial volatility. This ongoing debate underscores the complex interplay between innovation in trading technology and its systemic impact on market quality.
Advantages and Criticisms in Modern Markets
Dark pools represent a double-edged sword in modern financial markets, offering significant advantages for certain participants while simultaneously drawing sharp criticism from others.
Advantages:
- Minimizing Market Impact: The primary benefit is the ability for institutional investors to execute large block trades without causing significant price movements against their own interests. This directly addresses the problem of information leakage.
- Reduced Transaction Costs: For some institutional participants, trading in dark pools can lead to lower effective transaction costs compared to routing through lit exchanges, particularly when avoiding adverse market impact.
- Protection from Front-Running: By keeping orders undisclosed, dark pools offer a degree of protection against high-frequency traders or other market participants who might exploit knowledge of upcoming large orders.
- Alternative Liquidity: They provide an additional source of liquidity, complementing traditional exchanges and offering more options for execution.

Criticisms:
- Lack of Transparency: The most significant criticism is the inherent opacity. The absence of pre-trade transparency means that the broader market, especially retail investors, cannot see bids and offers, raising concerns about fairness and equal access to information.
- Conflicts of Interest: Many dark pools are operated by large broker-dealers who also route client orders to them. This can create potential conflicts of interest, as the broker-dealer might prioritize sending orders to its own dark pool over other venues, even if better prices exist elsewhere.
- Fairness Concerns for Retail Investors: Retail investors typically do not have direct access to dark pools and must rely on their brokers to route orders. This creates a two-tiered market where institutional investors benefit from opaque trading, while retail investors are confined to public, transparent markets.
- “Toxic Liquidity”: A concern exists that dark pools might attract “toxic liquidity”—informed trades executed by sophisticated players—while leaving less informed or smaller orders to be processed on lit exchanges. This could potentially degrade the quality of public market pricing.
- Regulatory Scrutiny: The opacity makes dark pools difficult to regulate and monitor effectively, raising challenges for market surveillance and ensuring compliance with best execution obligations.
The ongoing evolution of dark pools, driven by continuous technological innovation, sophisticated algorithms, and evolving regulatory pressures, ensures their place as a central topic in discussions about market structure, fairness, and the future of electronic trading. As financial technology advances, the debate over the optimal balance between transparency and execution efficiency will undoubtedly continue to shape how these innovative trading venues operate.