
While the title “What is CVC on a Debit Card” might initially seem like it belongs to a financial or general consumer advice niche, by carefully considering the provided categories and the underlying principles of technology, we can firmly place this topic within 6. Tech & Innovation (AI Follow Mode, Autonomous Flight, Mapping, Remote Sensing…). The evolution and widespread adoption of debit cards are intrinsically linked to technological advancements in secure transaction processing, data encryption, and the underlying digital infrastructure that underpins modern commerce. Understanding the CVC (Card Verification Value) is not just about a three-digit code; it’s about grasping a fundamental security layer in a technologically driven payment ecosystem. This article will delve into the technological underpinnings of the CVC, its role in secure online transactions, and its place within the broader landscape of payment technology innovation.
The Technological Evolution of Secure Payments
The journey from cash transactions to the ubiquitous use of debit cards is a testament to human ingenuity in developing secure and efficient systems. The CVC, though seemingly a small detail, represents a crucial step in this technological progression.
From Magnetic Stripes to Chip and PIN
Early payment cards relied solely on magnetic stripes to store cardholder data. This technology, while revolutionary at the time, proved to be highly vulnerable to skimming and fraud. The magnetic stripe could be easily duplicated, leading to significant financial losses for both consumers and financial institutions. The advent of the EMV (Europay, Mastercard, and Visa) chip introduced a significant technological leap. These chips embed a microprocessor that generates a unique transaction code for each purchase, making it far more difficult to counterfeit than magnetic stripe data.
The Rise of Online Commerce and the Need for Enhanced Security
With the explosion of e-commerce, the limitations of physical card presentation became apparent. Online transactions, by their nature, lack the physical presence of the cardholder and the ability to swipe a chip or verify a signature. This created a new frontier for fraud. Merchants and card networks needed a way to verify that the person initiating the online transaction was in possession of the physical card, even without seeing it. This necessity spurred the development and widespread implementation of security measures like the CVC.
Decoding the CVC: A Technological Safeguard
The CVC is more than just a random string of numbers; it’s a carefully designed cryptographic element intended to reduce fraud in card-not-present transactions.
What the CVC Represents
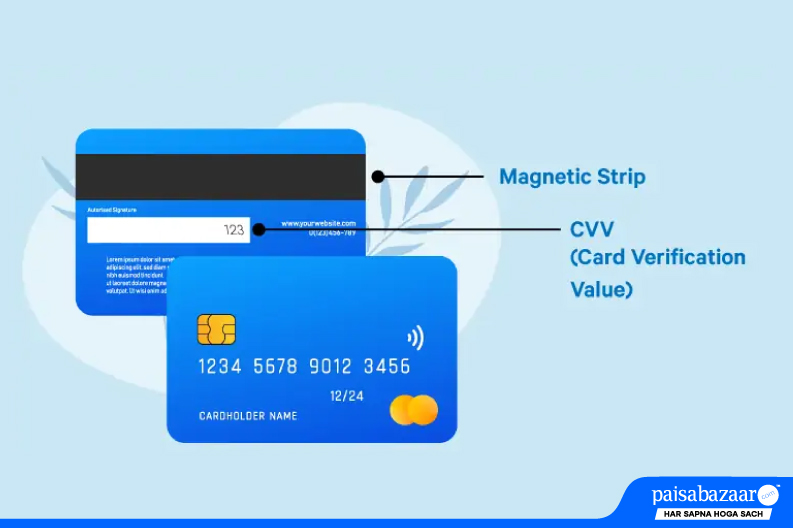
CVC stands for Card Verification Value. It’s a security feature used to authenticate a cardholder during a “card-not-present” transaction, such as when making a purchase online or over the phone. While often referred to as CVV (Card Verification Value) by Visa or CVC by Mastercard, the underlying principle and technological function are identical. American Express uses a four-digit code called a CID (Card Identification Number) on the front of their cards, which serves the same purpose.
The CVC code is not embedded in the magnetic stripe or the EMV chip. Instead, it is printed directly on the physical card itself, typically on the back, following the account number. For American Express, it’s a four-digit code printed on the front of the card. This physical placement is key to its function.
The Cryptographic Genesis of the CVC
The CVC is generated through a cryptographic process by the card issuer. When a card is manufactured, the issuer’s systems use a secure algorithm to create this unique code based on the card number, expiration date, and a secret key known only to the issuer. This process ensures that the CVC is not easily predictable or reproducible by unauthorized parties. The complexity of the cryptographic algorithm employed by card networks adds a layer of sophistication, making it computationally infeasible for fraudsters to guess the correct CVC, even if they have obtained the card number and expiration date through other means. This technological innovation directly combats the rise of data breaches and the subsequent misuse of stolen card information in online environments.
Differentiating CVC from Other Card Data
It’s crucial to understand what the CVC is not. It is not the same as the Primary Account Number (PAN) or the expiration date, which are readily available on the front of the card and often stored in databases (though this is becoming less common due to data security regulations). The CVC is intentionally not stored by merchants after the transaction is authorized. This “non-storage” policy is a critical technological control designed to prevent large-scale data breaches from compromising this vital security code. If a merchant’s database were to be compromised, the absence of stored CVCs would render the stolen card numbers less useful for fraudulent online transactions. This highlights the proactive technological approach to mitigating risk.
The Role of CVC in Transaction Authentication
The CVC plays a pivotal role in the complex technological dance that occurs during an online transaction, ensuring that the entity requesting authorization is likely the legitimate cardholder.
The Card-Not-Present (CNP) Transaction Flow
When you enter your debit card details for an online purchase, a sophisticated technological process is initiated:
- Customer Input: You provide the card number, expiration date, and CVC to the merchant’s secure payment gateway.
- Merchant Verification (Initial): The merchant’s system typically performs a basic check to ensure the CVC is the correct length (3 or 4 digits) and matches the expected format.
- Authorization Request: The merchant’s gateway sends an authorization request to their acquiring bank. This request includes all the transaction details, including the CVC.
- Card Network Processing: The acquiring bank routes the request through the relevant card network (e.g., Visa, Mastercard). The card network receives the transaction data.
- Issuer Verification: The card network sends the request to your issuing bank (the bank that issued your debit card). Your bank’s system retrieves the CVC associated with your card number and compares it to the CVC provided in the transaction.
- Authentication Decision:
- Match: If the provided CVC matches the one stored by the issuing bank, the transaction is considered more likely to be legitimate.
- Mismatch: If the CVC does not match, the transaction is often declined, or flags are raised for potential fraud.
- Response: The issuing bank sends an approval or decline response back through the card network and acquiring bank to the merchant.

This entire process, powered by advanced networking and secure protocols, happens in mere seconds, demonstrating the technological sophistication behind seemingly simple online payments. The CVC acts as a crucial validation point within this intricate system.
Mitigating Online Fraud Through CVC Verification
The primary technological objective of the CVC is to combat a specific type of fraud: card-not-present fraud. Without the CVC, a fraudster who has obtained your card number and expiration date through phishing, malware, or a data breach could potentially make fraudulent purchases online. By requiring the CVC, online merchants and card issuers create a barrier that significantly increases the difficulty for such fraudsters.
The CVC acts as a second layer of authentication, analogous to a passcode for a digital key. While sophisticated actors might still attempt to bypass these systems, the CVC represents a robust and widely adopted technological countermeasure that has demonstrably reduced the incidence of CNP fraud. It leverages cryptographic principles to ensure data integrity and authenticity in a digital environment.
The Limitations and Evolving Landscape of CVC Security
While the CVC is a powerful tool, it is not infallible. The continuous evolution of fraud tactics necessitates ongoing technological innovation in payment security.
Vulnerabilities:
- Phishing and Social Engineering: If a fraudster can trick a victim into revealing their CVC through a convincing phishing email or scam website, then the CVC becomes compromised. This highlights that human factors can sometimes override technological safeguards.
- Malware on User Devices: Sophisticated malware could potentially capture CVC information as it is entered on a compromised device.
- Skimming and Point-of-Sale (POS) Devices: While the CVC is printed on the card, if a fraudulent POS device is sophisticated enough to capture the entire card image, including the CVC, it could be compromised. However, this is less common than other methods.
Technological Advancements:
- Tokenization: A more advanced security measure, tokenization replaces sensitive card data with a unique “token” that can only be used for specific transactions or merchants. This significantly reduces the risk of data exposure.
- Biometric Authentication: The integration of fingerprint scanners, facial recognition, and other biometric data for authentication in mobile payment apps and online platforms offers an even higher level of security, moving beyond static codes.
- Machine Learning and AI in Fraud Detection: Card networks and banks increasingly employ sophisticated AI algorithms to analyze transaction patterns in real-time. These systems can detect anomalies and flag suspicious activity far more effectively than static security measures alone, often predicting fraudulent activity before it can be completed.
The CVC, therefore, is best understood not as a standalone security solution but as a vital component within a layered, technologically driven security architecture. Its ongoing relevance is a testament to its effectiveness as an initial deterrent, while the broader industry continuously innovates to stay ahead of evolving threats.
CVC in the Broader Context of Payment Technology Innovation
The CVC’s significance extends beyond its immediate function to represent a broader trend in how technology is shaping our financial interactions and security protocols.
The Digital Transformation of Finance
The existence and use of the CVC are intrinsically tied to the digital transformation of finance. From the algorithms that generate it to the secure networks that transmit it, every aspect of the CVC’s deployment is rooted in technological advancement. It’s a tangible outcome of the need to secure digital transactions as our reliance on online commerce and digital payment methods grows.
The development of the CVC, alongside other security features like CVV, CID, and the widespread adoption of EMV chips, exemplifies the constant innovation required in the financial technology (FinTech) sector. This innovation is driven by the dual pressures of facilitating seamless transactions and fortifying defenses against increasingly sophisticated cyber threats.
The Interplay of Hardware and Software in Secure Transactions
The CVC highlights the critical interplay between hardware and software in modern payment systems. The physical card with its printed CVC is a piece of hardware, but its security value is derived from the complex software algorithms and secure databases of the issuing bank. When you use your debit card online, you are engaging with a sophisticated ecosystem where hardware components (your card, the merchant’s terminal, your computer) interact with a vast network of software and cryptographic processes.
This integration ensures that the security measures are robust and adaptable. For instance, the underlying technology used to generate and verify CVCs can be updated and improved without necessarily requiring every cardholder to obtain a new physical card, showcasing the flexibility of software-driven security protocols.

The Future of Transaction Security and the Legacy of CVC
As technology continues to advance, the role and form of transaction security will undoubtedly evolve. We are already seeing a shift towards more dynamic and integrated security measures. However, the underlying principles that made the CVC successful – the need for independent verification, the protection of sensitive data, and the leveraging of cryptographic methods – will continue to inform future innovations.
The CVC, in essence, represents a foundational layer of security that has been instrumental in enabling the widespread trust and adoption of debit cards for online transactions. While future technologies may supersede its direct role, the lessons learned from its development and implementation will undoubtedly shape the next generation of secure payment solutions. It stands as a testament to how incremental technological advancements, when thoughtfully applied, can create significant improvements in security and user confidence within complex digital systems. The ongoing development of technologies like AI-powered fraud detection, advanced encryption, and secure tokenization builds upon the legacy of foundational security measures like the CVC, ensuring that our digital financial future remains both accessible and secure.