
The Dynamic Landscape of Mortgage Rates: A Digital Perspective
The question of “what is current mortgage rates” is more complex than a simple numerical answer; it’s a reflection of an intricate interplay of global economic forces, central bank policies, and increasingly, technological advancements. In the digital age, understanding these rates requires appreciating how technology shapes their formation, accessibility, and the very mechanisms through which they are determined. Far from static figures, current mortgage rates are fluid, influenced by a rapidly evolving ecosystem of data analytics, artificial intelligence, and innovative financial tools designed to streamline and, theoretically, optimize the lending process.
Economic Drivers and Algorithmic Forecasting
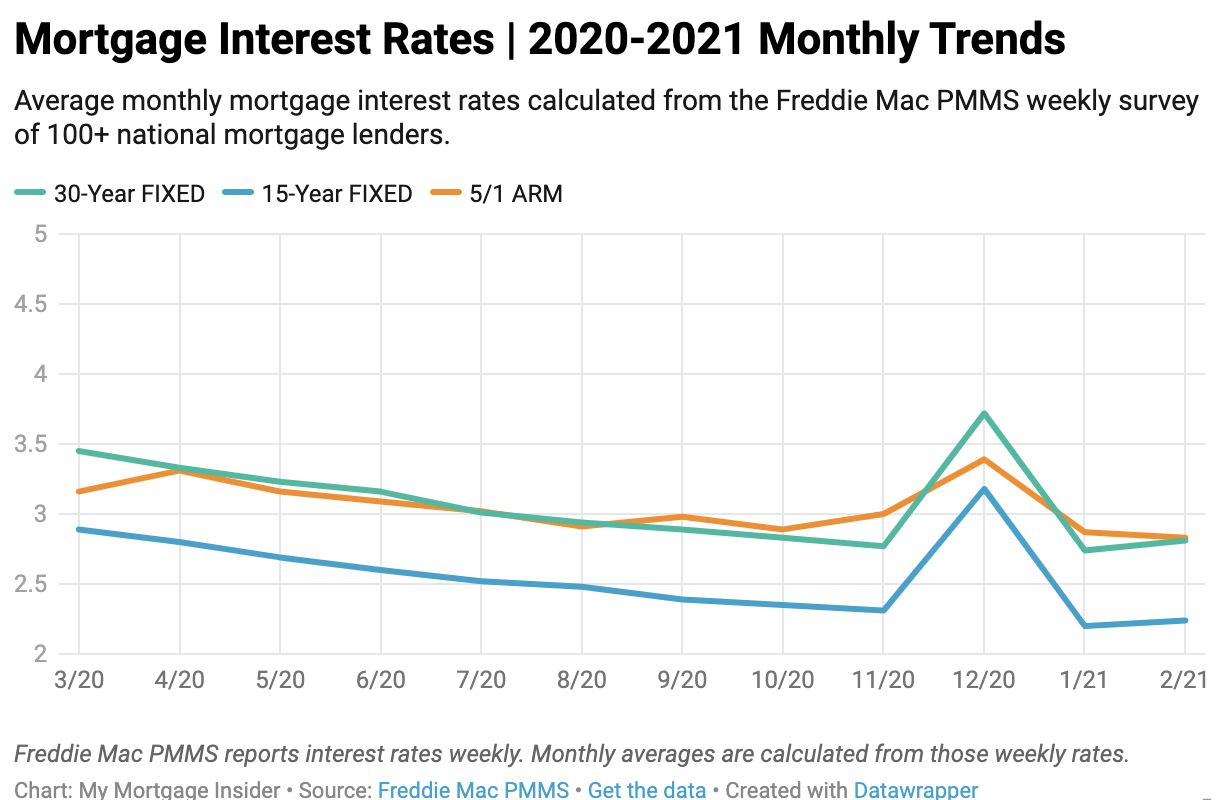
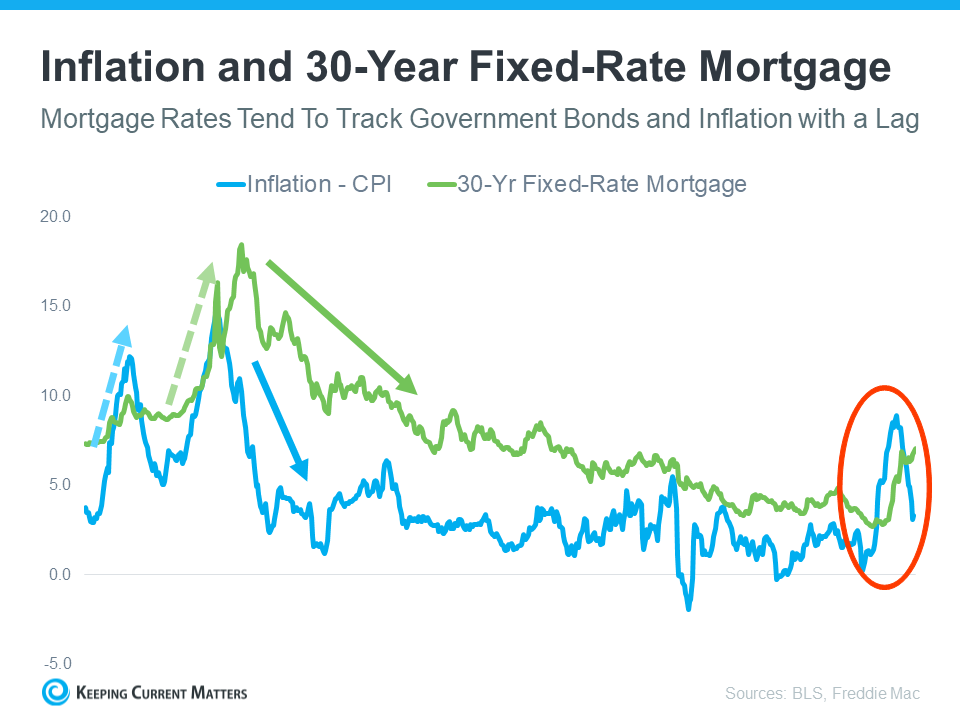
Traditionally, mortgage rates have been anchored to broader economic indicators such as inflation, employment figures, GDP growth, and the monetary policy decisions of central banks like the Federal Reserve. When central banks adjust benchmark interest rates, it directly impacts the cost of borrowing for lenders, which is then passed on to consumers in the form of mortgage rates. However, the speed and sophistication with which these economic signals are now processed and interpreted have been revolutionized by technology. High-frequency trading algorithms and advanced econometric models ingest vast datasets, allowing for near-instantaneous reactions to market shifts. Lenders no longer solely rely on human analysis but leverage AI-powered forecasting tools that predict market movements, bond yields, and consumer behavior with unprecedented precision. This means that a slight whisper of an economic change can ripple through the market and affect mortgage rates almost immediately, requiring borrowers to stay exceptionally agile and informed.
The Role of AI and Machine Learning in Rate Setting
The “current” in current mortgage rates is increasingly defined by real-time algorithmic processing. AI and machine learning (ML) models are employed by major financial institutions to set and adjust rates with a granularity and responsiveness previously unimaginable. These algorithms analyze not only macroeconomic data but also microeconomic factors, competitive offerings, individual borrower risk profiles, and even geospatial data related to property values. By processing millions of data points, AI can identify patterns and correlations that human analysts might miss, leading to dynamic pricing strategies. For borrowers, this means rates are often highly personalized, reflecting a nuanced assessment of their creditworthiness and the perceived risk of their specific loan application. While this can lead to more competitive rates for lower-risk applicants, it also demands transparency and robust regulatory oversight to ensure fairness and prevent bias in algorithmic decision-making. The innovation here lies in the capacity for continuous learning and adaptation, allowing mortgage offerings to perpetually optimize for market conditions and lender profitability.
Innovation in Mortgage Product Design and Delivery
Beyond the calculation of rates, technological innovation is transforming the very architecture of mortgage products and how they are delivered to consumers. The industry is moving away from a one-size-fits-all approach, utilizing digital platforms to offer bespoke solutions and enhance the borrower experience.
Fintech Platforms and Personalized Rate Discovery
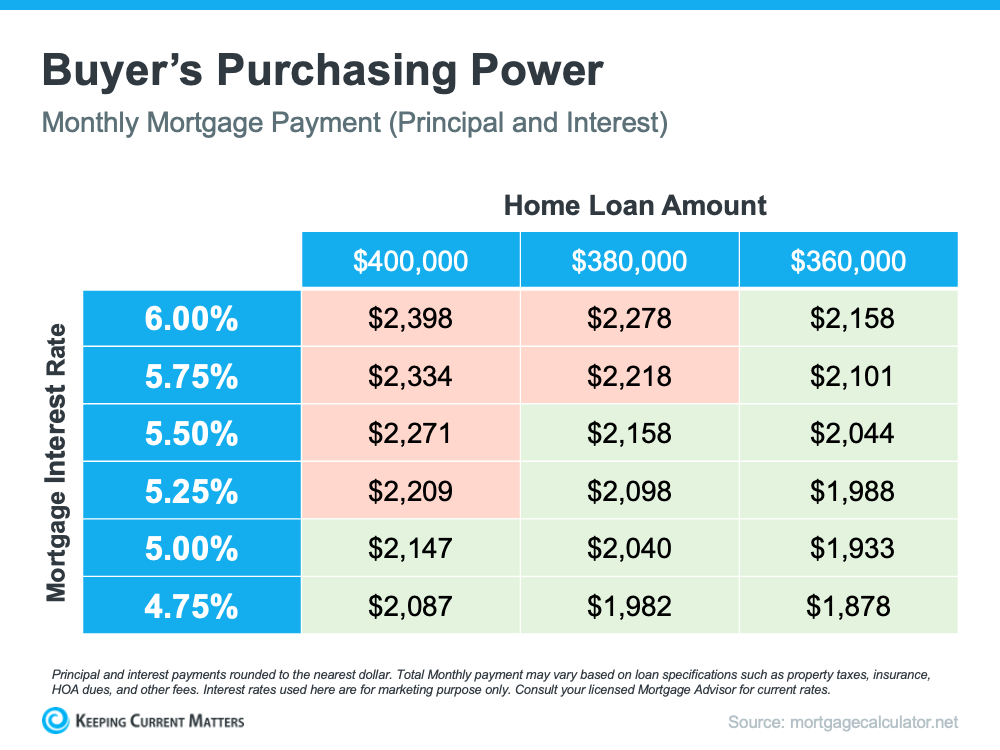
Fintech platforms have emerged as powerful disruptors in the mortgage market. These platforms aggregate offers from multiple lenders, providing borrowers with a transparent, consolidated view of available rates and terms. Through intuitive interfaces and personalized dashboards, prospective homeowners can compare complex loan products, understand the nuances of adjustable-rate versus fixed-rate mortgages, and even simulate different payment scenarios. The innovation here is not just in comparison but in guided discovery. Many platforms use AI-driven recommendations based on a borrower’s financial profile, goals, and risk tolerance, helping them navigate what can often be an overwhelming decision-making process. This democratization of information and personalized guidance is fundamentally shifting power dynamics, empowering consumers to make more informed choices about their mortgage. Furthermore, the efficiency gains from digital application processes, automated document verification, and e-signatures significantly reduce the time and effort traditionally associated with obtaining a mortgage, often speeding up approval times from weeks to days, or even hours.
Blockchain for Transparency and Efficiency
While still in nascent stages for mainstream mortgage applications, blockchain technology holds immense promise for further enhancing transparency and efficiency in the lending ecosystem. Imagine a future where property titles, loan agreements, and payment histories are recorded on an immutable, distributed ledger. This could drastically reduce fraud, eliminate the need for costly intermediaries in title transfers, and simplify the entire loan origination and servicing process. For mortgage rates, blockchain could foster a more liquid and efficient secondary mortgage market, potentially reducing costs for lenders and, in turn, leading to more competitive rates for borrowers. The innovation lies in its potential to create a single, verifiable source of truth for all transactional data, stripping away layers of complexity and improving trust among all parties involved, from the initial application to loan securitization.
Data, Valuation, and Risk Assessment in the Digital Age
The foundation of any mortgage rate is the assessment of risk—the likelihood that a borrower will repay the loan and the value of the underlying asset. Technology is dramatically reshaping how this risk is evaluated, offering more precise and dynamic appraisal methods.
Remote Sensing and Predictive Analytics in Property Appraisal
Traditional property appraisals have been time-consuming and subjective. Today, remote sensing technologies, often leveraging aerial data (though not necessarily from drones in the consumer mortgage context, but satellite or advanced mapping data), combined with sophisticated predictive analytics, are transforming this field. Algorithms analyze vast datasets including historical sales prices, neighborhood amenities, zoning regulations, and even environmental factors. This data, sometimes supplemented by high-resolution imagery and 3D modeling, provides a more comprehensive and objective valuation of a property. For lenders, this means a more accurate assessment of collateral risk, which can influence the loan-to-value ratio and, consequently, the interest rate offered. The innovation here is the shift from sporadic, manual appraisals to continuous, data-driven valuation models that can react to market changes in real-time, providing a clearer picture of an asset’s worth.
Digital Accessibility and Financial Inclusion
Technological innovation in mortgages isn’t just about efficiency for lenders or better rates for prime borrowers; it’s also about expanding access. Digital platforms can reach underserved communities more effectively, offering financial education and simplified application processes. AI-powered underwriting models can potentially analyze a wider array of data points beyond traditional credit scores (e.g., rent payment history, utility bills), providing a more holistic view of a borrower’s financial reliability. This can open doors for individuals with thin credit files or non-traditional income streams, fostering greater financial inclusion. The “current mortgage rates” in this context represent an opportunity for a broader segment of the population to access homeownership, fueled by innovations that transcend conventional barriers.
Navigating the Future: Technology’s Impact on Borrowers and Lenders
Understanding current mortgage rates today means recognizing that they are products of a deeply interconnected digital ecosystem. For borrowers, leveraging fintech tools, staying informed about market trends, and understanding how their digital footprint might influence their loan offers are crucial. For lenders, continuous innovation in data science, AI, and platform development is paramount to staying competitive and managing risk effectively. The future of mortgage rates will undoubtedly be characterized by even greater personalization, real-time adjustments, and a progressively seamless digital experience, fundamentally altering how we perceive and engage with home financing.