
The Core of Dwelling Protection in a Technologically Evolving World
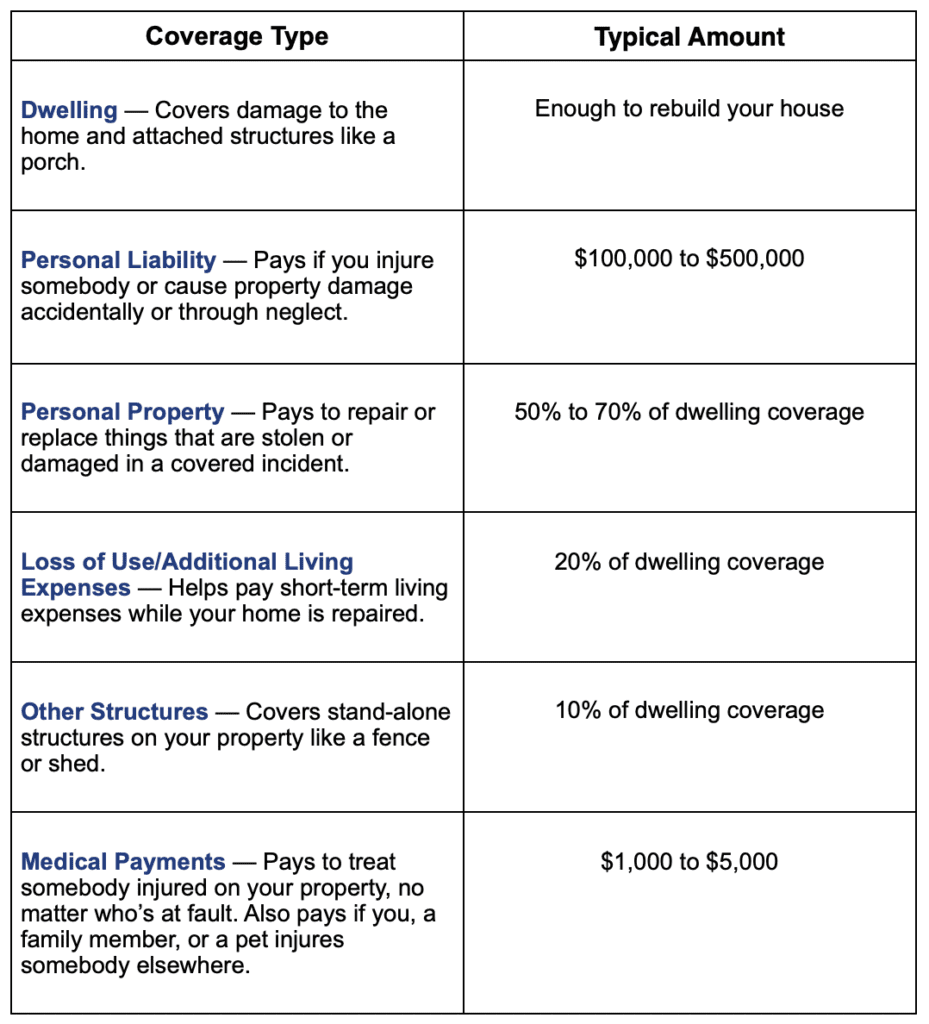
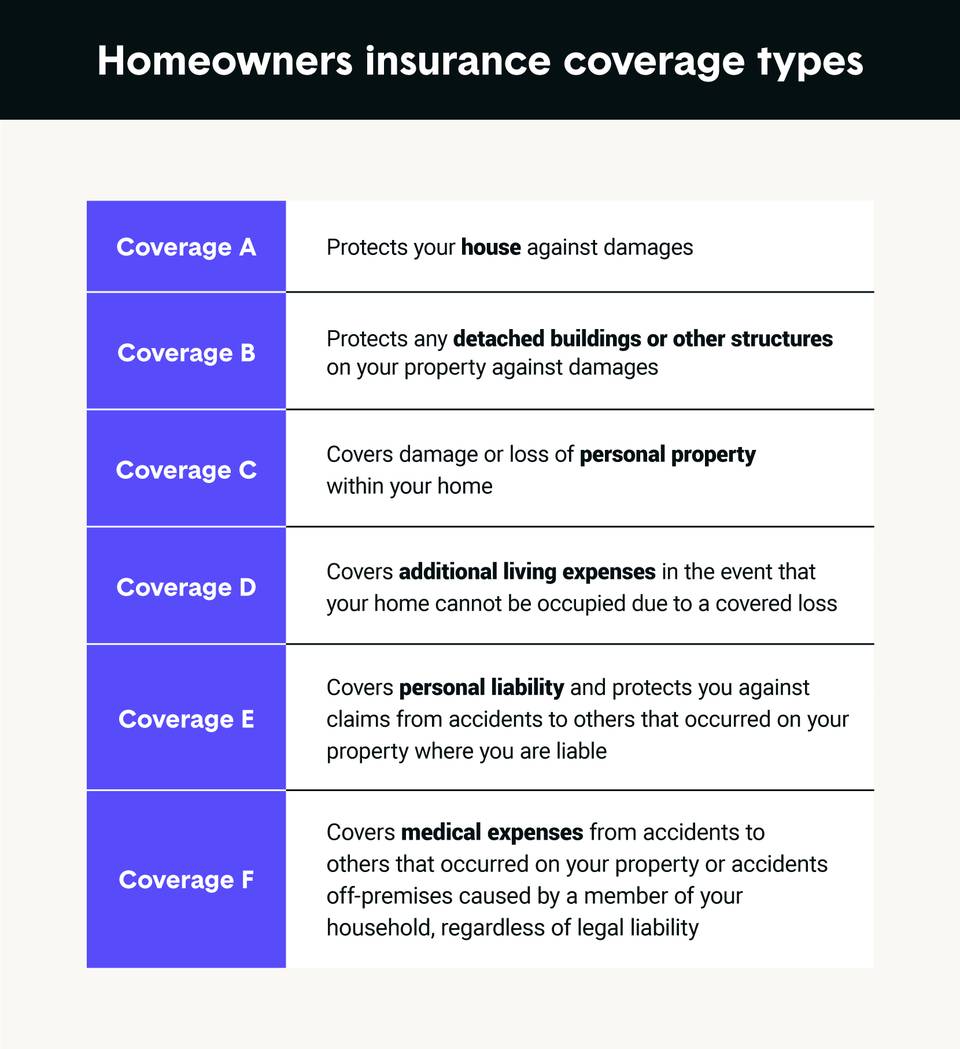
Coverage A on a homeowners policy stands as the bedrock of property insurance, specifically designed to protect the physical structure of your home. Traditionally, this section of your policy outlines the financial safeguard for the main dwelling, including attached garages, decks, and other structures permanently affixed to the home. It’s the portion of your insurance that steps in to rebuild or repair your house in the event of covered perils such as fire, windstorms, or vandalism. However, as our homes evolve into sophisticated ecosystems of smart technology and innovative design, the fundamental principles of Coverage A are being challenged and redefined within the broader landscape of Tech & Innovation.
Today’s homes are far more than just brick and mortar. They are integrated networks of sensors, automated systems, advanced materials, and increasingly, points of interaction with external technologies like drones. From voice-activated lighting and climate control to AI-powered security systems and energy-efficient building envelopes, modern residences are becoming central hubs for technological advancement. This rapid integration of “Tech & Innovation” necessitates a deeper understanding of how traditional insurance frameworks, particularly Coverage A, adapt to these changes. Insuring a smart home with a self-regulating environment, or a dwelling constructed from novel composite materials, demands a re-evaluation of valuation, risk assessment, and repair methodologies that go beyond conventional estimates. The imperative is not merely to define Coverage A, but to understand its resilience and flexibility in a world where the very definition of “dwelling” is in constant flux due to technological progress.
Defining “Dwelling” in the Era of Smart Homes and IoT
The traditional definition of a dwelling under Coverage A centered on tangible, static structural elements. However, the advent of smart homes and the Internet of Things (IoT) blurs these lines. Is an integrated smart thermostat, a connected lighting system, or an in-wall tablet controller considered part of the “dwelling” structure, or personal property? Generally, if these systems are permanently installed and designed to be integral to the home’s functioning, they fall under Coverage A. Yet, the rapid obsolescence of technology, proprietary systems, and the complex interplay between hardware and software introduce new complexities. Insurers must distinguish between the physical components covered by Coverage A and the data or software aspects, which may fall under different policy sections or require specialized endorsements. This distinction is crucial for accurately valuing the insured property and ensuring adequate coverage for the sophisticated systems that define a modern home.
The Challenge of Insuring Innovative Building Materials and Structures
Technological innovation isn’t limited to smart home gadgets; it extends to the very materials and methods used in construction. Advanced composites, 3D-printed components, self-healing concrete, and energy-generating facades are transforming residential architecture. While these materials offer benefits like enhanced durability, sustainability, or structural integrity, they pose unique challenges for Coverage A. Traditional insurance actuarial tables are built on decades of data for conventional construction materials. Assessing the risk profile, repair costs, and replacement value of a home constructed with experimental or proprietary materials requires new data and evaluation models. Furthermore, the specialized skills and equipment needed for repairing or rebuilding such structures can significantly impact claims costs and timelines, pressing insurers to innovate their own assessment tools to keep pace with construction technology.
Assessing Risk for Tech-Integrated Properties and Drone Interactions
The integration of advanced technology into homes fundamentally alters their risk profile, directly impacting Coverage A. Automated systems, while enhancing convenience and efficiency, can also introduce new vulnerabilities, such as cyber threats or system malfunctions. For instance, a sophisticated HVAC system that relies on AI to optimize climate control might be more complex to repair after a power surge than a traditional unit, directly affecting dwelling repair costs. Beyond internal systems, the increasing presence of drone technology presents a unique layer of consideration for homeowners and their Coverage A. Drones are now routinely used for roof inspections, property surveillance, and even package delivery, creating both efficiencies and potential new risks for the dwelling itself.
Consider a home designed with a dedicated drone landing pad on its roof or an integrated charging station within its structure. These additions are explicit forms of “Tech & Innovation” directly impacting the dwelling. If such a feature is damaged by a heavy storm or suffers a malfunction, Coverage A would be called upon. The complexities arise in distinguishing what constitutes a “fixture” versus an “accessory,” especially for drone-related installations that might be semi-permanent or modular. As autonomous aerial vehicles become more prevalent, the potential for incidental damage to the dwelling from an errant drone (whether owned by the homeowner or a third party) also becomes a consideration, highlighting the need for insurers to update their risk models to include this burgeoning aspect of modern living.
Drone Technology for Property Surveillance and Maintenance – Coverage Implications
Drones have revolutionized property management, offering quick, detailed aerial inspections for roofs, gutters, and structural integrity. Homeowners and maintenance companies increasingly leverage these tools for proactive upkeep. However, the use of drone technology also brings new dimensions to Coverage A. If a drone being operated for a routine inspection crashes into the insured dwelling, damaging the roof or exterior, how is this handled? Typically, such damage would fall under Coverage A. The nuance lies in the circumstances: was the drone operated by the homeowner, a contractor, or a third-party service? The liability aspect might shift, but the dwelling damage itself remains a Coverage A concern. Furthermore, as drones become more integrated into smart home security systems, operating autonomously to patrol perimeters, their physical presence as part of an overall “dwelling security system” needs to be understood in the context of dwelling coverage if they suffer damage while performing their duties or cause damage themselves.
Structural Modifications for Aerial Vehicle Integration: A Coverage A Perspective

The future envisions homes equipped with specialized features for aerial vehicles, such as small drone hangars, launch platforms, or delivery ports. These structural modifications, directly facilitating drone interaction, become an integral part of the dwelling. When a homeowner invests in building a dedicated, structurally integrated drone port, this addition significantly impacts the home’s value and structural footprint. Coverage A would need to encompass the full replacement cost of such specialized components. Questions then arise about the unique risks associated with these integrations: potential fire hazards from charging stations, structural stress from repeated drone landings, or even niche liabilities. Insurers are tasked with understanding these novel structural elements, their unique failure modes, and their overall contribution to the dwelling’s insurable value, pushing the boundaries of traditional property assessment.
Navigating Exclusions and Endorsements for Advanced Home Systems
While Coverage A aims to protect the dwelling, standard homeowners policies contain exclusions that could leave technologically advanced homes vulnerable. For instance, damage resulting from war, nuclear hazard, or government action is typically excluded. More relevant to “Tech & Innovation,” issues related to cyber risks, data breaches, or loss of functionality due to software glitches might not be explicitly covered under a standard Coverage A, which focuses on physical damage. As homes become more interconnected, the distinction between physical damage and system failures due to non-physical causes becomes critical. A smart home’s climate control system failing due to a cyberattack might not be covered if the policy only addresses physical damage to the unit.
To address these gaps, specific endorsements become vital. Homeowners with high-value smart home systems, integrated solar panels, geothermal heating, or even experimental energy solutions might need to add endorsements to their policy to ensure these particular innovations are adequately covered under Coverage A. These endorsements can broaden coverage, remove certain exclusions, or provide higher limits for specialized equipment. For example, a “Service Line Coverage” endorsement might extend to smart utility connections buried underground, while a “Home Systems Protection” endorsement could cover mechanical or electrical breakdowns of advanced home appliances and integrated smart tech that would otherwise be excluded. Navigating these complexities requires homeowners to actively engage with their insurers to tailor their Coverage A to their unique, tech-forward dwelling.
Cyber Risks and Data Breaches: Beyond Traditional Dwelling Coverage
The proliferation of IoT devices and integrated smart home systems exposes the dwelling to new types of risks that go beyond traditional physical damage. Cyberattacks targeting smart locks, security cameras, or even an entire home network can compromise safety and privacy. While physical damage to hardware resulting from such an attack might fall under Coverage A (e.g., a smart lock rendered physically unusable), the broader implications like data theft, privacy invasion, or functional impairment of systems without physical damage often do not. These aspects typically require specialized cyber insurance policies or specific endorsements that extend beyond the scope of a standard homeowners policy. This highlights a growing area where the definition of “dwelling protection” must evolve to encompass the digital integrity of the home as much as its physical structure.
Tailoring Coverage A for Autonomous Home Systems and Smart Infrastructure
As homes move towards greater autonomy, with AI managing everything from energy consumption to predictive maintenance, the components enabling this autonomy become part of the dwelling’s infrastructure. Imagine a home with an integrated system that autonomously monitors structural stress, alerts for potential leaks, and even deploys micro-drones for internal air quality checks. These sophisticated, interlinked systems demand a precise understanding of their insurable value and the specific perils they face. Tailoring Coverage A involves meticulously itemizing these autonomous components, understanding their replacement costs, and factoring in the specialized labor required for their repair or restoration. It’s not just about insuring a roof, but the advanced sensor network embedded within that roof, or the smart materials used in its construction, ensuring that the innovative core of the autonomous home is fully protected.
The Future of Home Coverage: AI, Predictive Analytics, and Dynamic Policies
The future of Coverage A will undoubtedly be shaped by “Tech & Innovation,” not just in the homes being insured, but in the insurance industry itself. Artificial intelligence, machine learning, and predictive analytics are poised to revolutionize how dwelling coverage is underwritten, priced, and managed. Insurers are increasingly utilizing drone imagery for faster, more accurate roof inspections, leveraging IoT data from smart homes for real-time risk assessment, and employing AI algorithms to predict potential perils and facilitate claims processing. This shift towards data-driven, proactive insurance models will lead to more granular and personalized Coverage A policies.
Imagine a dynamic Coverage A policy that adjusts premiums based on real-time data from your smart home’s sensors – detecting a sudden temperature drop that could burst pipes, or alerting to structural stress after an earthquake. This integration of “Tech & Innovation” allows for greater precision in risk evaluation, potentially leading to more equitable pricing and even proactive intervention strategies to mitigate damage before it occurs. The imperative for both homeowners and insurers is to embrace these technological shifts. Homeowners must understand how their advanced properties impact their Coverage A needs, while insurers must continually innovate their products and processes to provide relevant, comprehensive protection for the dwellings of tomorrow.
AI-Driven Risk Assessment for Innovative Home Structures
Artificial intelligence is transforming how insurers assess the risk associated with various dwelling structures. For homes incorporating innovative designs or materials (e.g., modular homes, properties built with sustainable composites, or those with unique architectural features like integrated drone ports), AI can analyze vast datasets, including environmental conditions, material performance, and regional risk factors, to develop more accurate risk profiles. This contrasts sharply with traditional manual assessments that might struggle with non-standard construction. AI can evaluate the durability of novel materials, predict their susceptibility to specific perils, and even factor in the unique stresses introduced by advanced features like a rooftop drone landing pad. This intelligent assessment allows for a more precise valuation for Coverage A, ensuring homeowners of cutting-edge properties receive appropriate and fair coverage.
Proactive Protection: Integrating Smart Home Data with Coverage A
The ultimate integration of “Tech & Innovation” with Coverage A lies in proactive protection. Smart home systems, equipped with an array of sensors, can monitor everything from water leaks and smoke detection to foundation shifts and extreme weather impacts. When this real-time data is seamlessly integrated with insurance systems (with homeowner consent), it opens up possibilities for immediate, preventative action. For example, a smart water sensor detecting a leak could not only alert the homeowner but also automatically trigger a notification to the insurer, potentially initiating a claims process and dispatching a service technician even before significant damage escalates. For Coverage A, this means moving beyond reactive repair to proactive mitigation. Such systems could potentially reduce claim severity, leading to lower premiums for homeowners who adopt them, and fundamentally redefining the relationship between the dwelling, technology, and its insurance protection.