
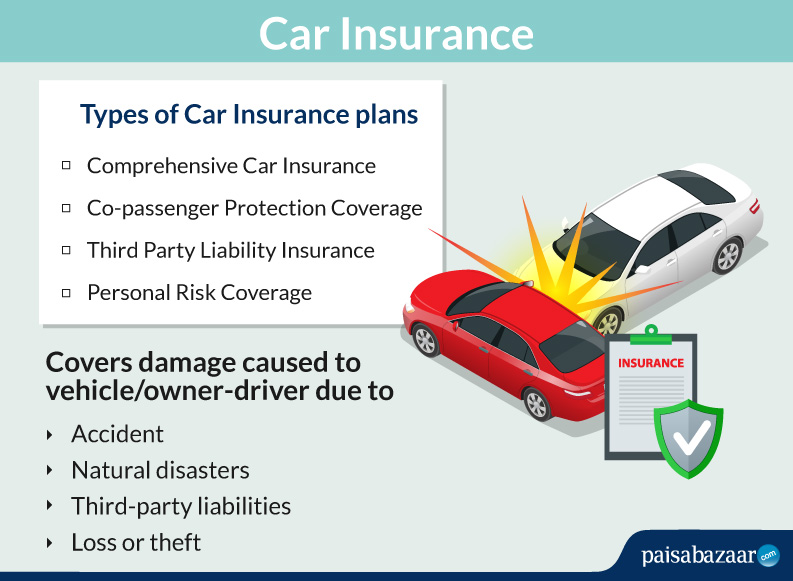
The query “what is car insurance for” prompts a fundamental reflection on risk, responsibility, and protection in the context of advanced technologies. While traditionally associated with terrestrial vehicles, the core principles underpinning automotive insurance—safeguarding against financial loss from accidents, damage, or liability—find compelling parallels and indeed, direct application, in the burgeoning world of unmanned aerial vehicles (UAVs), commonly known as drones. As drones evolve from niche gadgets to ubiquitous tools in consumer, commercial, and industrial sectors, understanding the diverse types of these flying machines, their operational complexities, and inherent risk profiles becomes paramount. Just as a vehicle demands protection for its owner and others, so too do the sophisticated aerial platforms navigating our skies.
The Analogy of Risk and Responsibility in Drone Operations
At its heart, car insurance serves as a financial buffer against the unpredictable. It acknowledges that despite careful driving, accidents can happen, leading to property damage, personal injury, and legal liabilities. This preventative approach to risk management is not unique to the automotive industry; it is a universal necessity wherever complex machinery interacts with public and private spaces. The rapid proliferation of drones across various applications has brought this need for comprehensive protection into sharp focus, mirroring the evolution of automotive safety and regulatory frameworks decades ago.
The Fundamental Purpose of Protection
Whether on the road or in the air, the primary goal of protection, be it through insurance or robust operational protocols, is to mitigate unforeseen consequences. For drones, these consequences can range from minor property damage caused by a recreational quadcopter to significant financial liabilities stemming from a commercial UAV malfunction during a critical infrastructure inspection. The complexity of drone technology, combined with the increasing density of airspace, amplifies the potential for incidents, making proactive risk assessment and robust protective measures indispensable.
From Roadways to Airspaces: A Shared Imperative
The parallels between vehicle operations and drone flights are striking. Both involve complex mechanical systems, human operators (or increasingly, autonomous systems), defined operational environments (roads vs. airspaces), and the potential for interaction with third parties. Just as a driver is responsible for their vehicle’s safe operation and any resulting damage, a drone pilot or operator carries significant responsibility for the safe conduct of their aerial missions. This shared imperative for accountability necessitates mechanisms—analogous to car insurance—that ensure financial solvency and legal compliance in the event of an incident.
Exploring the Spectrum of Drones and Their Associated Liabilities
The world of drones is incredibly diverse, encompassing a wide array of designs, capabilities, and intended uses. Each category of drone presents a unique set of operational challenges and potential liabilities, underscoring the necessity for tailored protective strategies. Understanding these distinctions is crucial for identifying the specific types of “insurance”—or risk mitigation—appropriate for each aerial platform.
Consumer-Grade Quadcopters: Entry Point to Aerial Risks
Consumer quadcopters, often accessible and relatively inexpensive, serve as many individuals’ introduction to drone technology. These devices, characterized by their four rotors and user-friendly controls, are primarily used for recreational flying, casual photography, and short-range exploration. While they may seem innocuous, their widespread use and often unregulated operation introduce a range of potential risks:
- Accidental Damage: Collisions with buildings, trees, or other objects can result in damage to the drone itself, as well as significant property damage to third parties.
- Personal Injury: Though less common with smaller drones, a drone losing control and impacting an individual can cause serious injury, leading to medical expenses and legal claims.
- Privacy Concerns: Equipped with cameras, even basic quadcopters can inadvertently (or intentionally) infringe upon the privacy of others, leading to complaints and potential legal action.
- Airspace Violations: Recreational pilots, unaware of local regulations, may inadvertently fly in restricted airspace, near airports, or above crowds, posing serious safety risks and incurring hefty fines.
For these drones, the “insurance” equivalent often focuses on personal liability coverage, either through homeowners’ policies (if applicable) or specialized drone insurance, protecting the operator from third-party claims.
Professional and Commercial UAVs: High-Value Assets, High-Stakes Operations
Moving beyond recreation, professional and commercial UAVs represent a significant leap in complexity, cost, and operational scope. These sophisticated platforms are deployed for a myriad of critical tasks:
- Industrial Inspection: Examining pipelines, wind turbines, bridges, and power lines.
- Mapping and Surveying: Creating high-resolution topographical maps, 3D models of construction sites, and agricultural land analysis.
- Logistics and Delivery: Pioneering autonomous delivery services for goods, medical supplies, and more.
- Public Safety: Assisting law enforcement, search and rescue, and fire departments with aerial oversight.
The stakes associated with these operations are considerably higher. The drones themselves can cost tens or hundreds of thousands of dollars, making equipment protection a significant concern. More critically, the potential for third-party liability is immense:
- Large-Scale Property Damage: A commercial drone carrying heavy equipment or operating near sensitive infrastructure could cause extensive damage in a crash.
- Business Interruption: A drone malfunction could disrupt critical operations, leading to significant financial losses for businesses.
- Contractual Obligations: Many commercial contracts require specific levels of liability coverage before drone operations can commence.
- Data Breach and Cyber Risks: Commercial drones often collect sensitive data, making them targets for cyberattacks or susceptible to data breaches, which can incur massive regulatory fines and reputational damage.
For commercial operators, robust drone insurance packages, akin to commercial auto insurance, are not just beneficial but often mandatory. These typically include liability coverage, hull coverage (for the drone itself), and specialized riders for data risks, business interruption, and payload insurance.
FPV (First Person View) and Racing Drones: The Thrill and the Tangle
FPV drones, particularly those used for racing or cinematic freestyle flying, offer an immersive flight experience through a pilot’s-eye view transmitted to goggles. These drones are designed for extreme agility and high speeds, often involving complex maneuvers in tight spaces or challenging environments.
- High-Speed Collisions: Racing drones frequently operate at very high speeds, increasing the kinetic energy upon impact and the severity of potential damage or injury.
- Close Proximity Flying: FPV pilots often fly close to obstacles, people (in controlled environments), or other drones, raising the risk of mid-air collisions or ground impacts.
- Specialized Events: Racing and freestyle events, while thrilling, concentrate many high-speed drones in one area, necessitating specific event liability coverage and stringent safety protocols.
Protection for FPV and racing drones often focuses on equipment replacement due to the high likelihood of crashes, alongside robust liability coverage for events or public demonstrations.
Micro Drones and Specialized UAVs: Niche Applications, Unique Considerations
This category encompasses a broad range of drones tailored for very specific, often niche, applications. This includes tiny indoor drones for inspection, specialized agricultural drones for precision spraying, or tethered drones for extended surveillance. While some micro-drones may pose lower risks due to their small size, others, despite their specialized nature, carry unique liabilities:
- Indoor Damage: Even small drones can damage delicate interior fixtures or cause minor injuries in confined spaces.
- Environmental Contamination: Agricultural spray drones, if misoperated, could apply chemicals incorrectly, leading to crop damage, environmental harm, or regulatory fines.
- Long-Duration Exposure: Tethered drones, while generally stable, present continuous overhead presence, and any failure could lead to prolonged exposure to risk for those below.
The “insurance” for these drones must be highly customized, reflecting the specific operational environment and potential unique risks inherent in their specialized functions.
Regulatory Compliance and Operational Safeguards for Drone Pilots
Beyond financial protection, a significant aspect of responsible drone operation, much like driving, involves adherence to regulatory frameworks and the adoption of best operational practices. These safeguards are integral to preventing incidents and minimizing the need for claims in the first place, serving as a critical layer of “preventative insurance.”
Understanding Airspace Rules and Certifications
Just as drivers require licenses and follow traffic laws, drone pilots must navigate a complex web of airspace regulations. These vary by country and region but typically involve:
- Pilot Certification: Commercial drone operators often require specific licenses (e.g., FAA Part 107 in the US) demonstrating their knowledge of airspace, regulations, and safe operating procedures.
- Airspace Restrictions: Knowledge of no-fly zones, temporary flight restrictions, and controlled airspace is crucial to avoid violations and dangerous encounters with manned aircraft.
- Operating Limitations: Regulations often dictate maximum altitudes, visual line-of-sight requirements, and restrictions on flying over people or at night.
Compliance with these rules is not only a legal requirement but also a fundamental component of risk management, significantly reducing the likelihood of accidents or legal repercussions.
Pre-Flight Planning and Risk Mitigation Strategies
Before any drone takes flight, comprehensive planning is essential. This includes:
- Site Surveys: Assessing the operational environment for potential hazards, obstacles, and suitable landing zones.
- Weather Checks: Ensuring conditions are safe for flight, considering wind, precipitation, and temperature.
- Equipment Inspections: Thoroughly checking the drone’s components, including propellers, batteries, motors, and camera systems, for any signs of damage or malfunction.
- Emergency Procedures: Having clear plans for what to do in case of a loss of signal, battery failure, or unexpected anomaly.
These proactive measures directly contribute to operational safety, analogous to a driver performing routine vehicle maintenance and planning their route to avoid hazards.
Data Security and Ethical Operation
With many drones equipped with advanced cameras and sensors, the ethical handling of collected data and the security of the drone’s systems are paramount.
- Privacy Protection: Ensuring compliance with privacy laws (e.g., GDPR) when collecting imagery or data that could identify individuals.
- Cybersecurity: Protecting the drone’s control systems and collected data from unauthorized access or malicious interference.
- Ethical Considerations: Operating drones responsibly, avoiding nuisance, harassment, or surveillance where not legally and ethically justified.
These aspects underscore that “insurance” for drones extends beyond physical damage to encompass digital and ethical liabilities.
The Imperative for Comprehensive Protection in Drone Activities
Ultimately, the answer to “what is car insurance for” resonates strongly within the drone ecosystem: it is for providing peace of mind and financial security against the myriad risks inherent in operating a complex machine in public or commercial environments. For drones, this imperative translates into a need for comprehensive protective measures that address various facets of potential loss.
Liability Coverage: Guarding Against Third-Party Claims
Just as car insurance protects drivers from claims arising from accidents they cause, drone liability coverage is crucial. This type of protection covers:
- Property Damage: Costs associated with repairing or replacing third-party property damaged by a drone.
- Bodily Injury: Medical expenses, lost wages, and other compensation for individuals injured by a drone.
- Legal Defense: Costs associated with legal fees, settlements, or judgments arising from drone-related incidents.
For both recreational and commercial operators, robust liability coverage is the cornerstone of responsible drone ownership.
Hull Coverage: Protecting Your Aerial Investment
Equivalent to collision and comprehensive coverage for a car, drone hull insurance protects the drone itself. Given the significant investment in professional UAVs, this is indispensable.
- Physical Damage: Covers repair or replacement costs for the drone and its components (e.g., camera, gimbal) due to crashes, collisions, or adverse weather.
- Theft: Protects against the financial loss if the drone is stolen.
This ensures operational continuity and safeguards the operator’s capital investment in their drone fleet.

Expanding Coverage for Specialized Risks
As drone applications become more sophisticated, specialized coverage options emerge, akin to riders on a traditional car insurance policy. These might include:
- Payload Coverage: Protecting specialized equipment attached to the drone, such as expensive LiDAR scanners or thermal cameras.
- Non-Owned Drone Coverage: For businesses that hire drone operators, ensuring their liability is covered for contracted services.
- Cyber and Data Breach Coverage: Specifically addressing risks related to data collected by drones, especially in sensitive commercial operations.
In conclusion, while the title “what is car insurance for” directly refers to automobiles, its underlying principles of managing risk, ensuring accountability, and providing financial protection are profoundly relevant and indeed critical for the responsible operation of drones. From recreational quadcopters to advanced commercial UAVs, the need for understanding potential liabilities and securing appropriate protection is not merely a recommendation but a fundamental requirement for navigating the skies safely and effectively.