
Choosing the right health insurance plan is a crucial decision that impacts your access to care, your out-of-pocket expenses, and your overall healthcare experience. Among the most common plan types are Health Maintenance Organizations (HMOs), Point of Service (POS) plans, and Preferred Provider Organizations (PPOs). Each offers a distinct approach to healthcare delivery and cost management, and understanding their fundamental differences is key to making an informed choice that aligns with your individual needs. This exploration delves into the intricacies of HMOs, POS plans, and PPOs, examining their structures, benefits, drawbacks, and suitability for different individuals and families.
Understanding the Core Structures: HMOs, POS, and PPOs
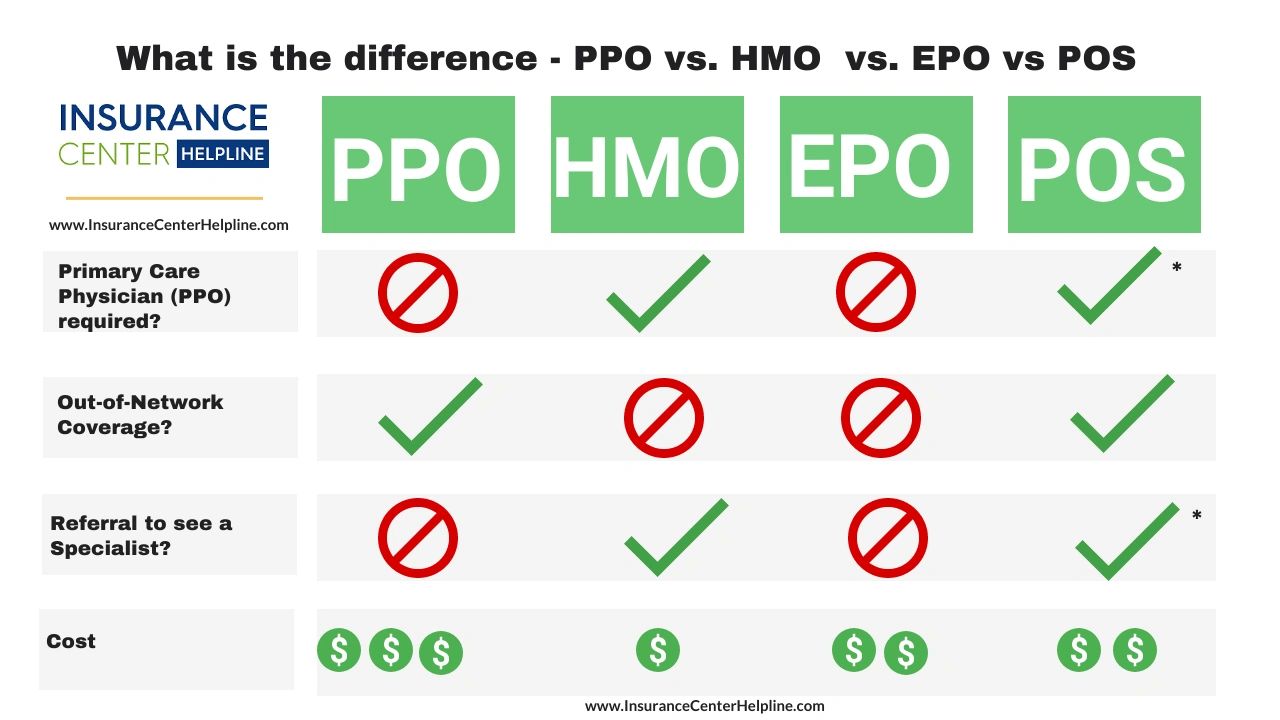
At their heart, these insurance models differ significantly in how they manage provider networks, referral processes, and out-of-network coverage. This foundational understanding is essential before considering specific features and costs.
Health Maintenance Organizations (HMOs)
HMOs are characterized by their focus on coordinated care and a defined network of healthcare providers. When you enroll in an HMO, you are generally required to choose a primary care physician (PCP) from the plan’s network. This PCP acts as your first point of contact for all non-emergency medical needs. They are responsible for managing your overall health, coordinating your care, and issuing referrals to specialists within the HMO’s network.
Key Features of HMOs:
- Primary Care Physician (PCP) Requirement: You must select a PCP who will manage your care and provide referrals.
- Network Restrictions: Generally, you must receive care from providers within the HMO’s network. Out-of-network care is typically not covered, except in cases of true emergencies.
- Referral System: Referrals from your PCP are usually required before you can see a specialist.
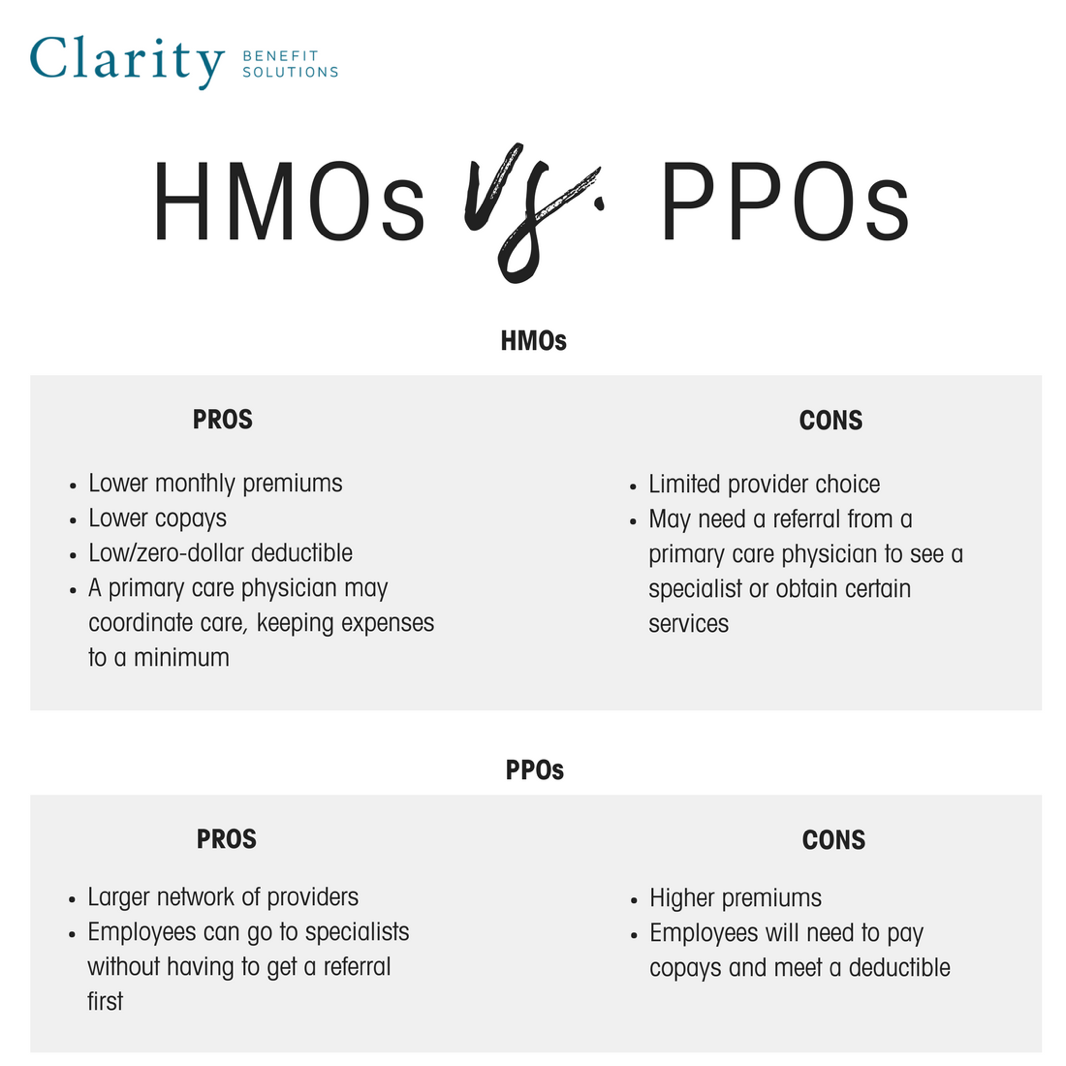
- Lower Premiums and Out-of-Pocket Costs: HMOs often have more affordable monthly premiums and lower deductibles, copayments, and coinsurance compared to PPOs. This is due to their emphasis on cost control through network management and a focus on preventive care.
- Emphasis on Preventive Care: HMOs typically cover a wide range of preventive services at little to no cost to encourage proactive health management.
When an HMO Might Be a Good Fit:
HMOs are often ideal for individuals and families who:
- Have a regular doctor they trust and are comfortable with their PCP coordinating their care.
- Do not anticipate needing frequent specialist visits outside of their PCP’s referral.
- Are looking for the most cost-effective option in terms of monthly premiums and routine medical expenses.
- Value a coordinated approach to healthcare where their PCP is central to all medical decisions.
Preferred Provider Organizations (PPOs)
PPOs offer a more flexible approach to healthcare by providing access to a network of preferred providers, but also allowing for out-of-network care. While you are encouraged to use in-network providers to minimize costs, you have the freedom to see any doctor or specialist you choose, even if they are not part of the PPO’s network.
Key Features of PPOs:
- No PCP Requirement: You are not typically required to select a PCP.
- In-Network and Out-of-Network Coverage: You can receive care from both in-network and out-of-network providers.
- No Referrals Needed for Specialists: You generally do not need a referral from a PCP to see a specialist.
- Higher Premiums and Out-of-Pocket Costs (for Out-of-Network): While in-network care in a PPO is usually cost-effective, you will pay significantly more for services received from out-of-network providers. This includes higher deductibles, copayments, and coinsurance. Premiums for PPOs are also generally higher than for HMOs.
- Greater Provider Choice: PPOs offer a broader range of provider choices, as you are not limited to a specific network.
When a PPO Might Be a Good Fit:
PPOs are often suitable for individuals and families who:
- Desire the flexibility to choose their own doctors and specialists without needing referrals.
- May need to see specialists frequently.
- Have a broad network of preferred providers they wish to continue seeing.
- Are willing to pay higher premiums for greater flexibility and the option of out-of-network care.
- Value the ability to seek care outside of a predefined network without a referral.
Point of Service (POS) Plans
POS plans represent a hybrid approach, combining elements of both HMOs and PPOs. Like HMOs, they often require you to designate a PCP. However, they also offer the flexibility to seek care outside the network, similar to PPOs, albeit with different cost implications.
Key Features of POS Plans:

- PCP Requirement (Often): You typically need to choose a PCP who will coordinate your care and provide referrals.
- In-Network Preferred: You receive the best coverage and lowest out-of-pocket costs when you use in-network providers.
- Out-of-Network Option with Higher Costs: You can choose to go out-of-network for care, but you will usually pay more than you would for in-network services. This often involves higher deductibles, copayments, and coinsurance.
- Referrals for Out-of-Network Care: Depending on the specific POS plan, you may still need a referral from your PCP to receive coverage for out-of-network services.
- Balance of Flexibility and Cost Control: POS plans aim to strike a balance between the cost controls of HMOs and the flexibility of PPOs.
When a POS Plan Might Be a Good Fit:
POS plans can be a good option for individuals and families who:
- Want the coordination benefits of a PCP but also desire the option to go out-of-network if necessary.
- Are comfortable with a structured approach to care but want a fallback option.
- Are looking for a middle ground between the cost-effectiveness of an HMO and the broad flexibility of a PPO.
Comparing Key Factors: Premiums, Out-of-Pocket Costs, and Provider Networks
The financial implications and the ease of accessing care are often the most significant considerations when comparing health insurance plans. Understanding how each plan type fares in these areas is paramount.
Premiums and Out-of-Pocket Expenses
- HMOs: Typically have the lowest monthly premiums. Out-of-pocket costs for in-network care (copayments, coinsurance) are also generally lower. However, if you go out-of-network for non-emergency care, you’ll likely pay the full cost.
- PPOs: Generally have higher monthly premiums than HMOs. While in-network costs are competitive, out-of-network care incurs significantly higher out-of-pocket expenses. This flexibility comes at a premium.
- POS Plans: Premiums are often in between HMOs and PPOs. Out-of-pocket costs for in-network care are similar to HMOs, while out-of-network costs are higher than in-network but potentially lower than a PPO’s out-of-network costs.
Provider Networks and Accessibility
- HMOs: Have the most restrictive provider networks. You must stay within the network to be covered for most services. This can be a challenge if your preferred doctors are not in the network or if you live in an area with limited network options.
- PPOs: Offer the largest and most flexible provider networks. You have a wide range of choices, both in and out of the network, providing greater peace of mind for those who value a broad selection of providers.
- POS Plans: Offer a good balance. Their in-network is generally robust, and while they allow out-of-network care, the associated costs mean the network’s breadth and your PCP’s referrals become more important.
Making the Right Choice: Factors to Consider for Your Needs
The “better” plan ultimately depends on your personal circumstances, healthcare utilization patterns, and financial priorities. A careful evaluation of these factors will guide you toward the most suitable option.
Evaluating Your Healthcare Needs
- Frequency of Doctor Visits: If you are generally healthy and rarely see doctors, an HMO might be sufficient and cost-effective. If you have chronic conditions or anticipate frequent specialist visits, a PPO’s flexibility could be more advantageous.
- Provider Preferences: Do you have a specific doctor or specialist you want to continue seeing? Check if they are in-network for the plans you are considering. If not, a PPO or POS plan may be necessary, or you may need to consider switching providers.
- Geographic Location: Consider the availability of providers within the plan’s network in your area. This is particularly important for HMOs, where limited network options can be a significant drawback.
- Prescription Drug Needs: While not a primary differentiator between HMOs, POS, and PPOs in terms of structure, drug formularies and copayments can vary significantly between plans. Always review the prescription drug coverage details.
The Role of Your Primary Care Physician (PCP)
The PCP’s role is a defining characteristic that often separates these plans.
- HMOs: Your PCP is your gatekeeper to the healthcare system. They are central to your care, and their coordination is essential. This can be beneficial for managing complex health issues.
- PPOs: The PCP is typically optional. You have the autonomy to self-direct your care and seek specialist appointments without a referral.
- POS Plans: The PCP’s role is often more nuanced. They coordinate care, and their referral may be needed, especially for out-of-network access, offering a middle ground in care coordination.
Understanding the Trade-offs
There is no one-size-fits-all answer. Each plan type involves trade-offs:
- HMOs: Offer lower costs in exchange for less flexibility and restricted provider choice.
- PPOs: Offer maximum flexibility and provider choice but at a higher cost.
- POS Plans: Aim for a balance, offering some flexibility with structured care coordination, with costs falling between HMOs and PPOs.
Ultimately, the decision between an HMO, POS, or PPO plan requires a thoughtful assessment of your personal health requirements, your preferred approach to managing your medical care, and your budget. By understanding the core structures, financial implications, and provider network considerations of each plan type, you can confidently select the health insurance option that best serves your needs.