
The Necessity of Protection in the Drone Ecosystem
In the rapidly evolving world of unmanned aerial vehicles (UAVs), commonly known as drones, the discussion surrounding robust protection measures is paramount. While the term “automobile insurance” traditionally brings to mind ground-based vehicles, the underlying principle – safeguarding valuable assets against unforeseen events and mitigating financial liabilities – applies with equal, if not greater, importance to drone operations. For hobbyists, professional aerial cinematographers, and industrial inspection teams alike, understanding the landscape of protection for their aerial platforms is not merely advisable; it is often a regulatory requirement and a critical business imperative. The sheer complexity, cost, and potential for harm associated with drone deployment necessitate a sophisticated approach to risk management.
Understanding Drone-Related Risks
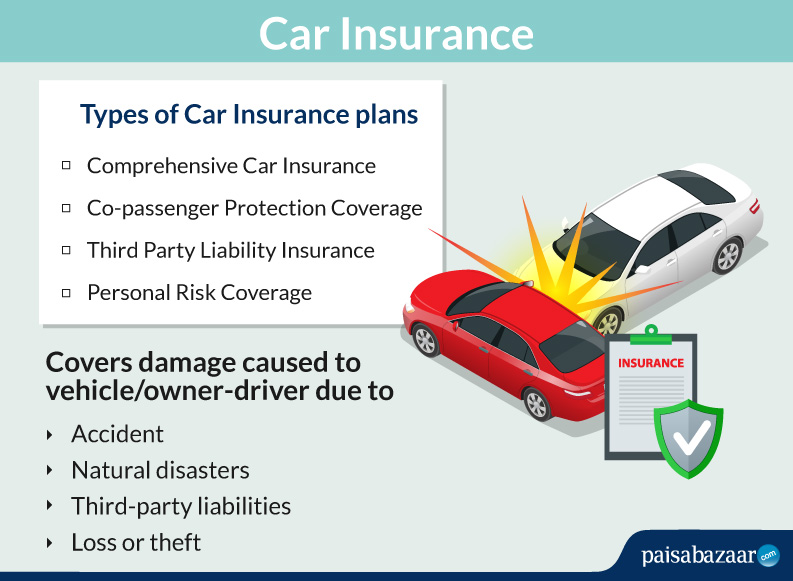
Drones, despite their increasing sophistication, are subject to a myriad of risks. Physical damage to the aircraft itself is a primary concern, whether due to operational errors, sudden mechanical failures, adverse weather conditions, or unexpected collisions. A drone can suffer irreparable damage from a hard landing or an unexpected encounter with an obstruction, rendering it inoperable and resulting in significant replacement or repair costs. Beyond the drone itself, the attached payloads, such as high-resolution cameras, thermal imaging sensors, or specialized mapping equipment, represent substantial investments that are equally vulnerable.
Furthermore, the operation of drones carries significant third-party liability risks. An uncontrolled descent, a collision with property, or an incident causing injury to individuals on the ground can lead to substantial legal claims and financial penalties. The public perception and potential for privacy concerns also add layers of complexity, even if direct physical harm is avoided. These risks are not theoretical; they are tangible threats that every drone operator must acknowledge and address.
Legal and Regulatory Frameworks
The global regulatory landscape for drone operations is dynamic and varies significantly by region and application. Many aviation authorities, such as the Federal Aviation Administration (FAA) in the United States, EASA in Europe, and Transport Canada, have established stringent guidelines governing commercial drone use, often mandating specific levels of liability coverage. For commercial operators, demonstrating adequate financial responsibility is a prerequisite for obtaining operational licenses or waivers for certain types of flights. Without appropriate coverage, businesses risk hefty fines, suspension of operating privileges, and severe financial exposure in the event of an incident. Even recreational operators, while sometimes exempt from commercial mandates, can face significant personal liability for damages caused by their UAVs. Adhering to these frameworks is crucial not only for compliance but also for fostering a safe and responsible drone community.
Types of Drone Protection Coverage
Just as with ground vehicles, various forms of protection exist to address the diverse risks associated with drone operations. These coverages are designed to provide financial relief and peace of mind, allowing operators to focus on their missions rather than crippling financial consequences.
Liability Coverage
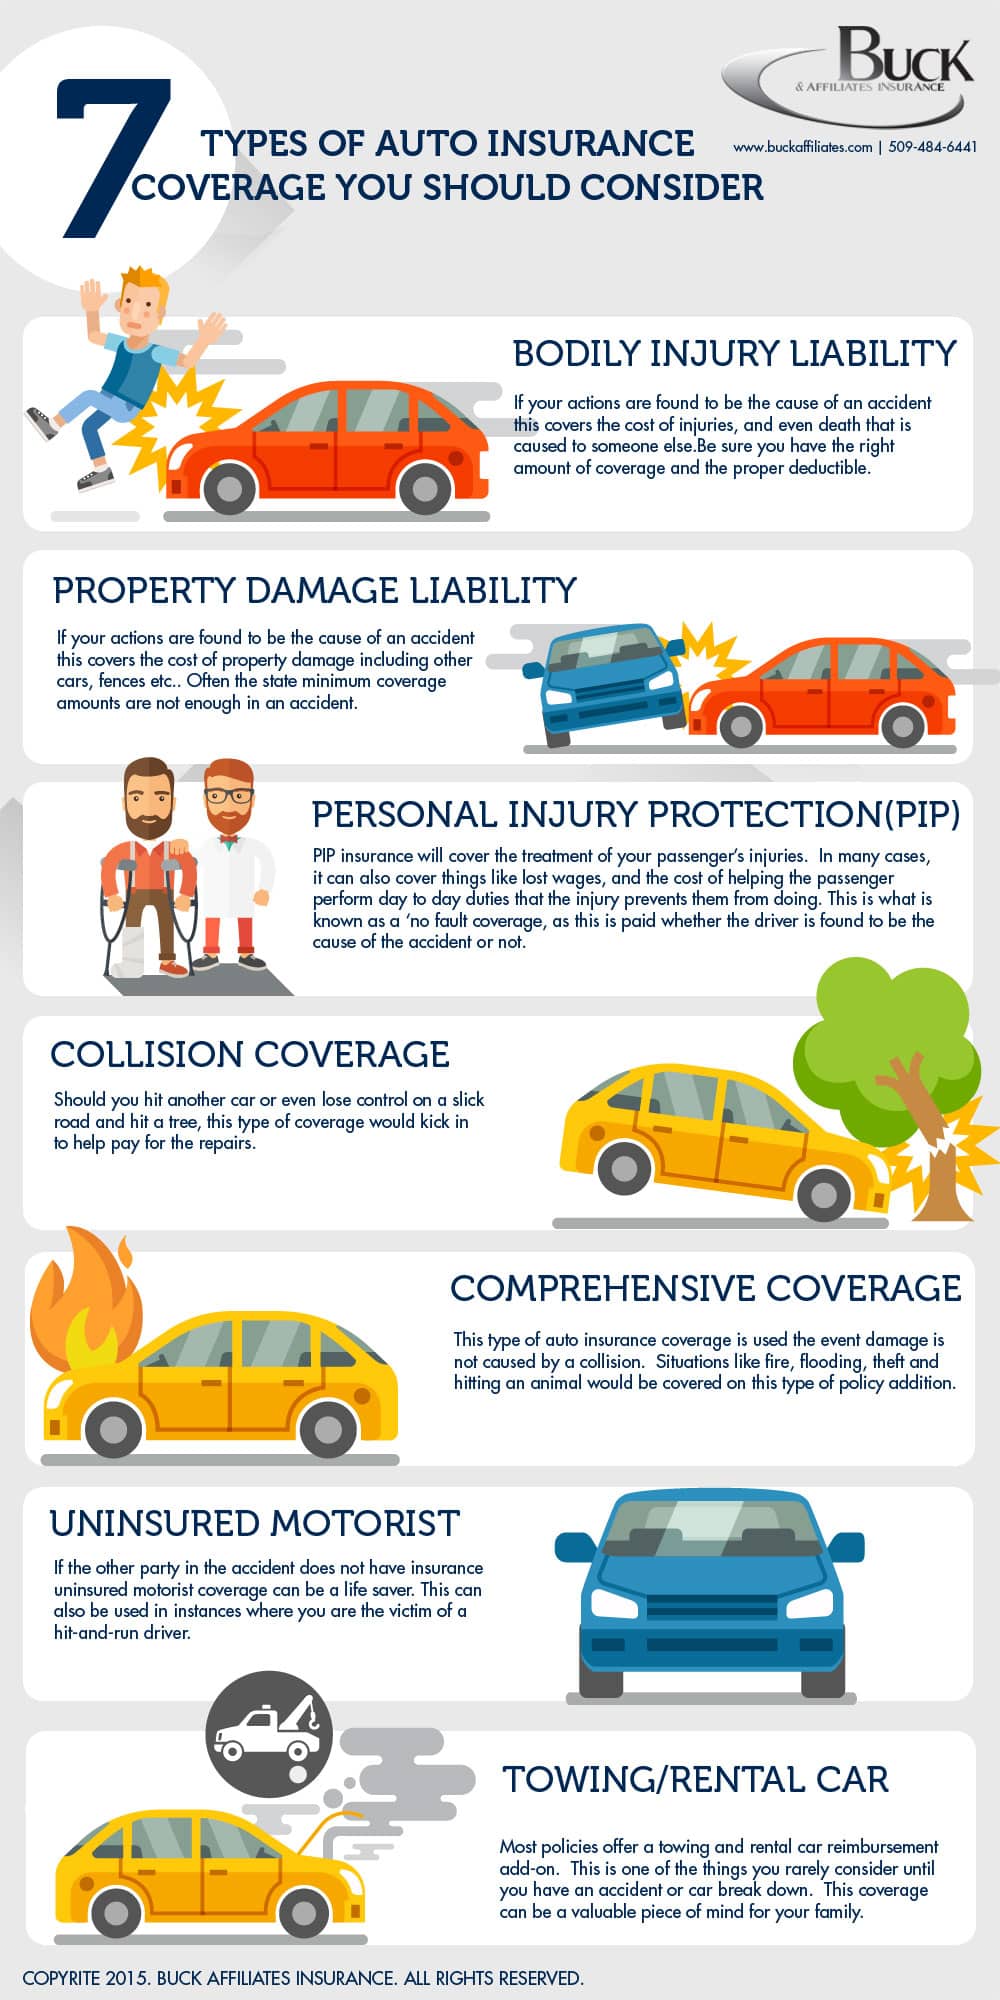
Liability protection is arguably the most critical component for any drone operator, particularly those engaged in commercial activities. This coverage protects the insured against claims for bodily injury or property damage to third parties caused by the operation of the drone. If a drone malfunctions and crashes into a building, damages a vehicle, or injures a bystander, liability coverage steps in to cover legal defense costs, settlements, or judgments awarded to the affected party. Policies can offer varying limits, typically ranging from hundreds of thousands to several millions of dollars, depending on the operational risk profile and regulatory requirements. For many commercial applications, a minimum liability limit is non-negotiable for legal operation.
Hull Coverage (Physical Damage)
Hull coverage, analogous to comprehensive and collision coverage for ground vehicles, protects the drone itself from physical loss or damage. This can include damage sustained during flight, takeoff, landing, or even during transportation or storage. Covered perils often include crashes, impacts, flyaways (where the drone is lost beyond recovery due to technical malfunction or signal loss), theft, fire, and natural disasters. Given the high cost of advanced drone platforms and their sensitive components, hull coverage is vital for protecting the significant capital investment made by operators. Without it, a single incident could wipe out an operator’s equipment or force them to bear the full cost of replacement.
Payload Coverage
Modern drones are often equipped with sophisticated and expensive payloads, such as high-resolution cameras, LiDAR scanners, multispectral sensors, or customized delivery mechanisms. These payloads can sometimes cost more than the drone platform itself. Payload coverage is specifically designed to protect these attached instruments from damage or loss while mounted on or used in conjunction with the insured drone. This ensures that a critical piece of equipment essential for a specific mission, like an industrial inspection or an aerial mapping project, is covered, preventing a potentially devastating financial setback for a business reliant on such technology.
Commercial vs. Recreational Policies
The distinction between commercial and recreational drone operations is fundamental in the realm of protection. Recreational policies are generally more limited in scope, often providing basic liability coverage and sometimes optional hull coverage for personal use. They typically come with lower premiums but also stricter restrictions on operational parameters, such as altitude, proximity to airports, and avoiding flights for any remuneration.
Commercial policies, on the other hand, are tailored for businesses and individuals using drones for profit-generating activities, such as real estate photography, agricultural surveying, construction site monitoring, or power line inspection. These policies offer higher liability limits, comprehensive hull coverage, and often include provisions for payload, non-owned drones, and specific endorsements for operating in complex environments or performing specialized tasks. Premiums are higher, reflecting the increased risk exposure and regulatory demands of professional operations, but they are an indispensable cost of doing business in the drone industry.
Key Factors Influencing Premiums
The cost of adequate protection for drones is not static; it is determined by a confluence of factors that assess the overall risk profile of the operator and the specific operational context.
Operator Experience and Training
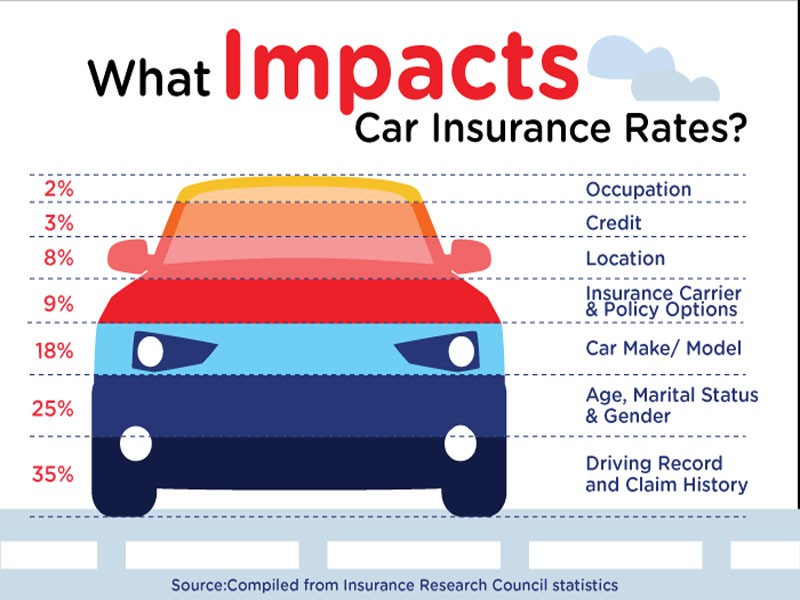
An operator’s skill level and experience are significant determinants. Individuals with extensive flight hours, valid certifications (e.g., FAA Part 107 certification), and a clean flight record are generally perceived as lower risk. Conversely, novice operators or those without formal training may face higher premiums or specific requirements, such as additional safety training or restrictions on flight conditions, reflecting their increased potential for incidents. Evidence of ongoing education and adherence to best practices can often lead to more favorable rates.
Drone Type and Value
The specific drone model, its size, weight, performance capabilities, and market value directly impact the cost of coverage. Larger, more powerful, or custom-built drones, especially those with advanced features or significant replacement costs, will naturally incur higher hull coverage premiums. The sensitivity and value of integrated or attached payloads also play a crucial role, influencing payload coverage costs proportionally. A high-end cinematic drone package, for example, will require more substantial coverage than a basic recreational quadcopter.
Operational Environment
Where and how a drone is operated significantly influences its risk profile. Flights in congested urban areas, near sensitive infrastructure, over large public gatherings, or in challenging weather conditions present higher risks compared to operations in open, rural environments. Similarly, the nature of the mission—whether it’s high-speed racing, intricate industrial inspections, or simple aerial photography—can dictate the likelihood and severity of potential incidents. Policies may include endorsements or exclusions based on the geographical area of operation or the specific industry application, tailoring the coverage to the inherent risks of the operational environment.
Navigating the Policy Landscape
Securing the right protection for drone operations requires careful consideration and a thorough understanding of available options. It’s a strategic decision that safeguards investments and ensures operational continuity.
Choosing the Right Provider
The drone protection market is served by specialized brokers and underwriters who understand the unique risks associated with UAVs. It is crucial to select a provider with a proven track record in aviation or drone protection, offering comprehensive policies tailored to the specific needs of drone operators. Engaging with providers who have extensive experience in this niche ensures that all potential risks are adequately addressed and that claims are handled efficiently by knowledgeable professionals. Online platforms and traditional brokers both offer access to various policies, and comparing quotes and coverage details from multiple providers is always recommended.
Policy Customization and Add-ons
Standard policies may not always cover every specific scenario an operator might encounter. Many providers offer customization options and add-ons to enhance coverage. These can include coverage for non-owned drones, allowing operators to be protected when using rented or borrowed equipment; coverage for specific flight waivers or exemptions; data loss protection; or even business interruption coverage for commercial operators whose drone operations are critical to their revenue stream. Operators should carefully assess their unique operational requirements and discuss these with their provider to ensure their policy is comprehensive and precisely matches their risk exposure.
The Claims Process
Understanding the claims process is vital before an incident occurs. A clear understanding of what information is required, the timelines involved, and the steps to take immediately following an incident can significantly streamline the process. Documenting pre-flight checks, maintaining flight logs, and having photographic or video evidence of drone condition can be invaluable in substantiating claims. Prompt reporting of incidents and adherence to the policy’s terms are crucial for a successful claim, ensuring that the financial relief intended by the policy is realized when it is most needed. For the modern drone operator, robust protection is not a luxury; it is a fundamental pillar of responsible and sustainable operation, securing both the hardware and the enterprise against the unpredictable nature of aerial endeavors.