
The Core Mechanics of a Leveraged Buyout Model in the Tech Landscape
A Leveraged Buyout (LBO) model is a sophisticated financial tool employed by private equity firms, investment banks, and corporate finance professionals to analyze and execute the acquisition of a company, predominantly with a significant amount of borrowed money (leverage). In the dynamic realm of Tech & Innovation, where companies often possess high growth potential, strong intellectual property, and recurring revenue streams, LBOs serve as a potent mechanism for investors seeking to generate substantial returns by optimizing operations, fueling strategic expansion, or consolidating market share. Understanding “what is an LBO model” is crucial for anyone engaging with the financial underpinnings of technology mergers and acquisitions.
Defining the LBO Structure
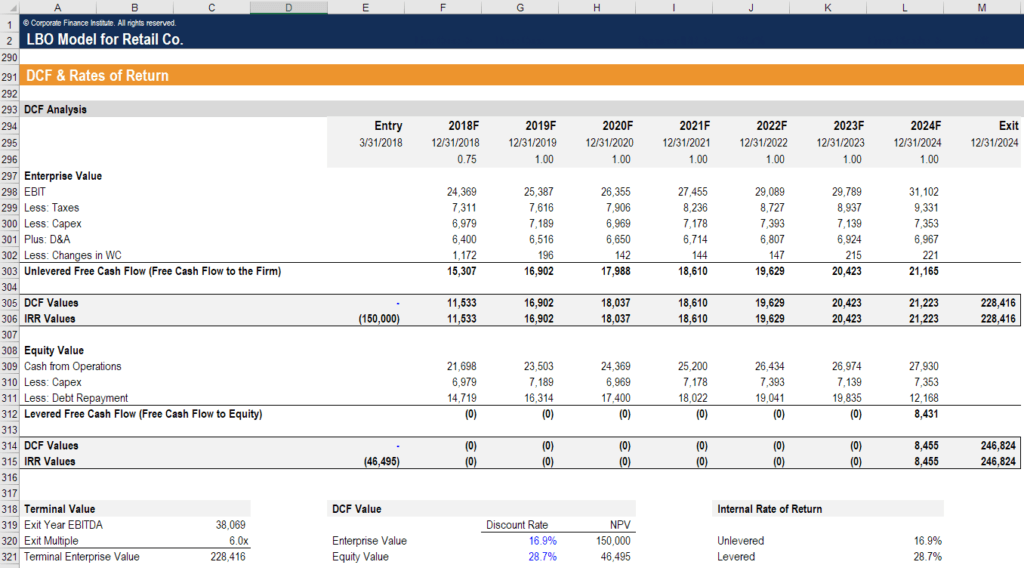
At its heart, an LBO involves acquiring a target company using a combination of debt and equity. The proportion of debt is typically very high, often ranging from 60% to 90% of the total purchase price. The assets of the acquired company, and sometimes those of the acquiring firm, are used as collateral for the borrowed funds. The acquiring entity, usually a private equity firm, contributes a smaller portion of its own capital (equity) and aims to use the target company’s future cash flows to service and ultimately repay the debt. The ultimate goal is to sell the company at a higher valuation in a few years, realizing a profit on the initial equity investment. In the context of Tech & Innovation, this might mean acquiring a mature software company with stable cash flows, a burgeoning SaaS provider with predictable recurring revenue, or even a hardware manufacturer with established market penetration. The model essentially forecasts the financial performance of the combined entity under the new ownership structure, projecting profitability, cash flow generation, and debt repayment capacity.
Key Inputs for Tech-Focused LBO Models
Building an effective LBO model for a technology company requires meticulous data gathering and informed assumptions. Unlike traditional industrial companies, tech firms often exhibit unique financial characteristics that must be carefully integrated:
- Revenue Projections: For a SaaS company, this involves subscription growth rates, churn rates, average revenue per user (ARPU), and pricing strategies. For a hardware company, it might focus on unit sales, product lifecycles, and market share. Innovation-driven firms might require assumptions around new product launches and market adoption curves.
- Cost Structure: This includes significant research and development (R&D) expenses, sales and marketing investments crucial for scaling tech platforms, and talent acquisition and retention costs. Unlike many sectors, tech companies often have high fixed costs associated with platform development and lower variable costs once a product is scaled.
- Capital Expenditures (CapEx): For tech firms, CapEx can relate to server infrastructure, data centers, intellectual property development, or specialized equipment for manufacturing advanced components (e.g., for drones or robotics).
- Working Capital Management: While not always as intensive as in manufacturing, managing accounts receivable (especially for enterprise software sales) and accounts payable can be critical.
- Debt Structure: This involves specifying the types of debt (senior, mezzanine, subordinated), interest rates, repayment schedules, and any associated covenants that might restrict operational flexibility.
- Exit Multiple: A crucial assumption is the valuation multiple (e.g., EV/EBITDA, EV/Revenue for high-growth tech firms) at which the company will be sold at the end of the investment horizon (typically 3-7 years). This multiple is highly sensitive to market conditions, industry trends in Tech & Innovation, and the company’s projected financial health at the time of exit.
Strategic Applications of LBO Models in Technology Acquisitions
LBO models are not merely academic exercises; they are vital strategic tools that guide significant investment decisions within the Tech & Innovation sector. Their application extends beyond mere valuation, influencing market dynamics, competitive landscapes, and the trajectory of technological advancement itself.
Driving Consolidation and Market Dominance
In mature or fragmented segments of the tech industry, LBOs can be used to acquire multiple smaller players, consolidating market share and achieving economies of scale. For instance, a private equity firm might identify several niche software providers serving a specific industry (e.g., logistics, healthcare tech) and use an LBO strategy to roll them up into a larger, more dominant entity. This consolidation can lead to greater pricing power, reduced operational costs, enhanced R&D capabilities, and ultimately, a more attractive platform for a future sale or IPO. The LBO model helps to evaluate the synergy benefits, potential cost savings, and the combined entity’s ability to service the increased debt burden.
Unlocking Value in Mature Tech Companies
Some established technology companies, while fundamentally sound, may be undervalued by public markets due to perceived slow growth, complex corporate structures, or non-core assets. An LBO model can identify opportunities to acquire such companies, take them private, and implement strategic initiatives away from public scrutiny. This might involve divesting non-performing divisions, streamlining operations, investing heavily in a specific product line, or shifting business models (e.g., from perpetual licenses to SaaS). The LBO model demonstrates how these operational improvements translate into enhanced cash flows and ultimately drive a higher valuation upon exit. It provides the roadmap for how the private equity firm will generate its return by repositioning the company within its market niche.
Financing Innovation and Growth through Debt
While high leverage often implies risk, in specific scenarios within Tech & Innovation, LBOs can paradoxically facilitate growth and innovation. For instance, a company with strong, predictable recurring revenue (e.g., a well-established cybersecurity firm or a data analytics platform) might be a prime candidate for an LBO. The stable cash flows can support significant debt service, allowing the private equity owner to inject additional capital for aggressive R&D, market expansion, or strategic acquisitions that accelerate product development cycles. The LBO model helps project the impact of these growth investments on future cash flows and ensures the company maintains sufficient liquidity to navigate market shifts while under a heavy debt load.

Deconstructing the Financial Engine: Model Components for Tech Deals
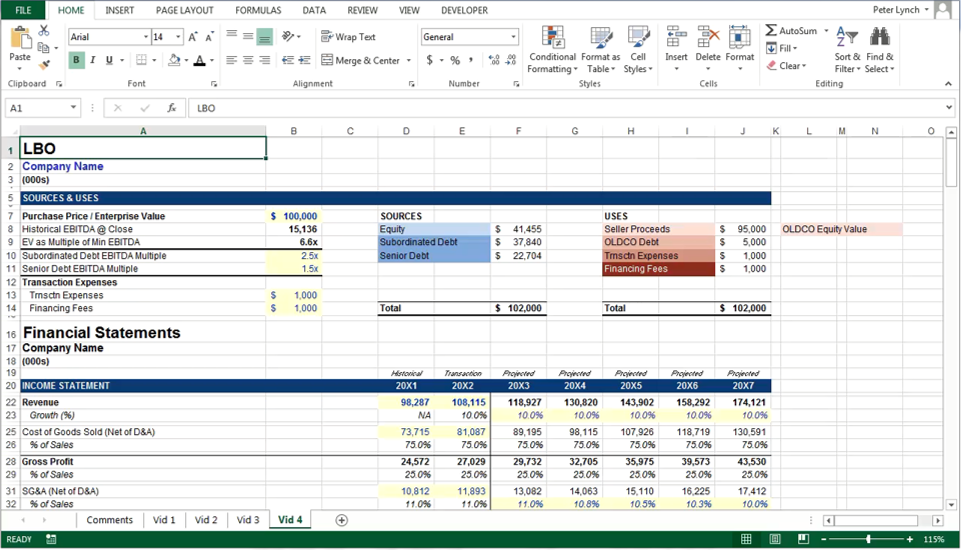
A comprehensive LBO model is typically built in Excel and consists of several interconnected sheets, each focusing on a critical aspect of the company’s financial performance and the transaction structure. For tech companies, specific considerations often dominate.
Revenue and Expense Projections for Tech Firms
The foundation of any LBO model is a robust set of financial projections. For tech companies, this requires deep industry understanding. Revenue forecasts must account for unique tech business models:
- SaaS/Subscription Revenue: Projecting growth in customer count, average subscription value, and understanding churn rates are paramount. Tiered pricing, upsells, and cross-sells also play a significant role.
- Licensing Revenue: Forecasting new licenses, renewals, and maintenance contracts.
- Hardware Sales: Unit volume, average selling price, and product refresh cycles.
- Advertising/Platform Revenue: User growth, engagement metrics, and monetization strategies.
Expense projections must also reflect tech-specific realities, such as high R&D intensity, significant cloud computing costs (COGS), and sales & marketing expenses that scale with customer acquisition efforts. The model must carefully distinguish between fixed and variable costs, especially as technology companies often exhibit high operating leverage once a platform is built.
Debt Structuring and Repayment Assumptions
The debt component is what defines a “leveraged” buyout. The LBO model meticulously details the various tranches of debt, their interest rates (fixed vs. floating), amortization schedules, and any associated fees or covenants. Common debt types include:
- Revolving Credit Facility: For short-term liquidity needs.
- Term Loans (A, B, C): Senior secured debt with varying maturities and amortization profiles.
- Mezzanine Debt: Hybrid debt-equity instruments, typically unsecured and subordinated, offering higher returns to lenders.
- Subordinated Debt: Junior to senior debt, with higher interest rates to compensate for increased risk.
The model projects the company’s ability to service this debt using its Free Cash Flow (FCF) and forecasts the remaining debt balance over the investment horizon. Critical analysis involves debt service coverage ratios and leverage ratios to ensure the company remains financially solvent under various operating scenarios.
Exit Strategies and Valuation Methodologies
The LBO model culminates in an exit analysis, projecting the returns to the private equity investor. This typically involves assuming a sale of the company after a 3-7 year holding period. Key valuation methodologies used include:
- Comparable Company Analysis (Comps): Valuing the company based on the trading multiples of similar publicly traded tech companies.
- Precedent Transaction Analysis: Valuing the company based on the multiples paid in recent M&A deals for comparable tech firms.
- Discounted Cash Flow (DCF): Projecting future free cash flows and discounting them back to a present value, particularly useful for high-growth tech companies with significant future potential.
The LBO model then calculates the Internal Rate of Return (IRR) and Money-on-Money (MoM) multiple for the equity investors, which are the primary metrics used to judge the attractiveness of the investment. For tech companies, the exit valuation can be heavily influenced by market sentiment towards the sector, the company’s intellectual property, competitive landscape, and its growth prospects in emerging technology trends.
Risks and Opportunities: LBOs Shaping the Future of Tech & Innovation
Leveraged Buyouts represent a powerful financial engineering technique with profound implications for the Tech & Innovation landscape, presenting both significant risks and unparalleled opportunities for value creation.
The Double-Edged Sword of Leverage in Volatile Markets
The primary risk in an LBO, particularly pertinent in the fast-evolving tech sector, is the high debt load. While leverage amplifies returns in good times, it also exacerbates losses during downturns. The tech market, known for its rapid shifts, intense competition, and sometimes speculative valuations, can be especially vulnerable. A sudden market correction, a disruptive new technology, or an economic recession can severely impact a tech company’s revenue and cash flow, making it challenging to service debt. This can lead to covenant breaches, forced asset sales, or even bankruptcy. An LBO model must incorporate robust stress testing and sensitivity analyses to assess the company’s resilience under adverse conditions, considering scenarios like reduced customer acquisition, increased churn, or delayed product launches.
Fostering Efficiency and Strategic Pivots
On the opportunity side, LBOs can serve as catalysts for significant operational improvements and strategic realignment within tech companies. Private equity firms bring not only capital but also deep operational expertise and a strong incentive to optimize performance. This can lead to:
- Streamlining Operations: Eliminating redundancies, improving software development lifecycles, and optimizing cloud infrastructure costs.
- Focusing on Core Competencies: Divesting non-strategic assets or product lines to concentrate resources on high-growth areas or core intellectual property.
- Aggressive Market Expansion: Providing the capital and strategic guidance to enter new markets, acquire competitors, or significantly scale sales and marketing efforts.
- Talent Optimization: Attracting and retaining top talent, especially in specialized areas like AI, cybersecurity, or advanced engineering, by offering performance-linked incentives.
The LBO model acts as the financial blueprint for these changes, showing how each strategic initiative impacts the balance sheet, income statement, and cash flow, ultimately contributing to a higher valuation.
Impact on R&D and Long-Term Innovation Cycles
The influence of LBOs on Research & Development (R&D) and long-term innovation in the tech sector is a complex topic. Critics sometimes argue that the pressure to service high debt levels can force companies to cut R&D spending, prioritizing short-term profitability over long-term innovation. However, proponents contend that focused LBOs can strategically invest in R&D, particularly if the technology is mature or has proven market potential. By taking a company private, an LBO can shield it from quarterly public market pressures, allowing for more substantial, longer-term investments in R&D that might not yield immediate returns but are critical for future competitiveness. The LBO model, in this context, helps to quantify the potential returns from strategic R&D investments, balancing debt service with the need to remain at the forefront of technological advancement. It enables a rigorous assessment of how innovation fuels future cash flows and underpins the ultimate success of the investment.