
The term “HSA insurance” is a common, albeit technically imprecise, way individuals refer to a specific type of health coverage that works in conjunction with a Health Savings Account (HSA). Understanding this relationship is crucial for individuals seeking to take a more proactive and financially advantageous approach to managing their healthcare expenses. An HSA is not insurance itself, but rather a tax-advantaged savings account that can be paired with a specific type of health insurance plan. This article will delve into the intricacies of HSA-compatible health insurance, exploring its benefits, how it functions, and who it’s best suited for.
Understanding the Core Components: HSA and High-Deductible Health Plans
At its heart, the concept of “HSA insurance” revolves around the synergy between a Health Savings Account and a High-Deductible Health Plan (HDHP). These two elements are inextricably linked, and one cannot fully realize the benefits of an HSA without the other.
Health Savings Accounts (HSAs)
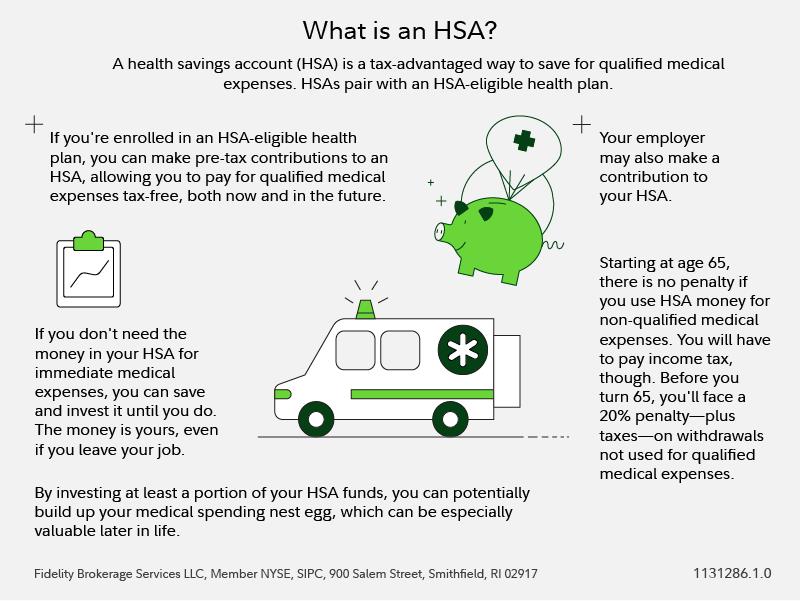
A Health Savings Account is a personal savings vehicle established by an individual to set aside pre-tax money for qualified medical expenses. It’s a powerful tool for managing healthcare costs because of its unique tax advantages:
- Tax-Deductible Contributions: Funds contributed to an HSA are typically tax-deductible, meaning they reduce your taxable income for the year. This offers an immediate tax benefit, lowering your overall tax burden.
- Tax-Free Growth: Any interest or investment earnings within the HSA grow on a tax-deferred basis. As long as the funds remain within the account, you won’t pay taxes on the growth.
- Tax-Free Withdrawals for Qualified Medical Expenses: When funds are withdrawn from the HSA to pay for qualified medical expenses, they are entirely tax-free. This is the primary benefit of the account, allowing you to use your own money for healthcare without incurring additional taxes.
These accounts are designed to encourage individuals to be more mindful of their healthcare spending, as they are directly managing and funding a portion of their medical needs.
High-Deductible Health Plans (HDHPs)
An HDHP is a health insurance plan characterized by a higher deductible compared to traditional health insurance plans. The deductible is the amount you must pay out-of-pocket for covered healthcare services before your insurance plan starts to pay.
Key features of HDHPs include:
- Lower Premiums: Generally, HDHPs come with lower monthly premiums than plans with lower deductibles. This can be a significant cost saving for individuals or families who are relatively healthy and don’t anticipate frequent or extensive medical care.
- Higher Out-of-Pocket Costs Upfront: As the name suggests, you will be responsible for paying a larger sum of money out-of-pocket before your insurance coverage kicks in for most services. This can range from a few thousand dollars to tens of thousands, depending on the plan and individual circumstances.
- Preventive Care Coverage: Importantly, IRS regulations stipulate that HDHPs must cover certain preventive care services at no cost to the member, even before the deductible is met. This includes services like annual check-ups, vaccinations, and screenings.
The crucial link between an HDHP and an HSA is that federal law requires that in order to be eligible to contribute to an HSA, an individual must be covered by an HDHP. This is why people often refer to the combination as “HSA insurance.”
How “HSA Insurance” Works in Practice
The interplay between an HDHP and an HSA is designed to provide a layered approach to healthcare financing and management.
The Patient’s Role
Under an HSA-compatible plan, the individual or family acts as the primary payer for initial healthcare costs up to the deductible amount. This is where the HSA comes into play. They can use the funds accumulated in their HSA to cover these out-of-pocket expenses.
- Routine Care: For doctor’s visits, prescription medications, and other routine medical services that fall below the deductible, the individual pays using funds from their HSA.
- Major Medical Events: In the event of an accident, surgery, or a significant illness, the individual will continue to pay for services until they meet their high deductible. Once the deductible is met, the HDHP begins to cover a larger portion of the costs, often through coinsurance or copayments, depending on the plan’s structure.
The Insurance Provider’s Role
The HDHP serves as a safety net for catastrophic medical expenses. While the individual is responsible for the initial deductible, the insurance plan is designed to protect them from overwhelming financial burdens should they experience a serious health issue.
- Catastrophic Coverage: The primary function of the HDHP is to provide coverage for high-cost medical events after the deductible has been satisfied. This prevents individuals from facing bankruptcy due to unexpected medical emergencies.
- Prescription Drug Coverage: Most HDHPs include prescription drug coverage, although this may also be subject to the deductible and coinsurance.
Benefits of Choosing an HSA-Compatible Plan
Opting for a plan that allows for HSA contributions offers a multitude of advantages, particularly for individuals who are financially savvy and health-conscious.
Financial Advantages
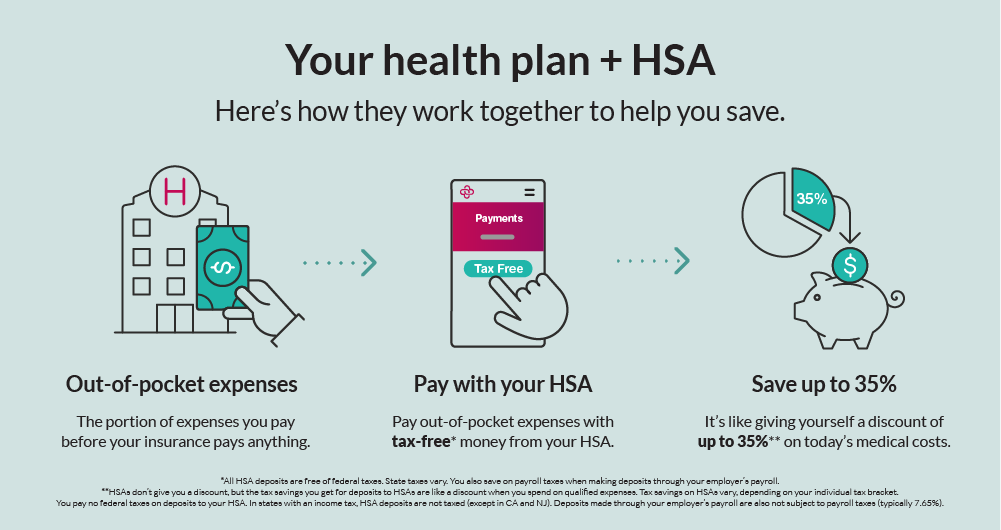
The tax benefits associated with HSAs are perhaps the most compelling reason to choose this type of coverage.
- Triple Tax Advantage: As previously mentioned, the triple tax advantage (deductible contributions, tax-free growth, and tax-free withdrawals for qualified expenses) makes HSAs one of the most powerful savings vehicles available. This can lead to significant long-term savings on healthcare costs.
- Potential for Investment Growth: Many HSA administrators allow account holders to invest their funds in a variety of options, similar to a 401(k) or IRA. This means that over time, the money in your HSA can grow and potentially outpace inflation, further increasing its value for future medical needs.
- Portability: Unlike employer-sponsored health benefits that are tied to your employment, an HSA is owned by you. This means that when you change jobs or retire, your HSA and the funds within it go with you. You retain control and ownership regardless of your employment status.
- No “Use It or Lose It” Rule: A key differentiator from Flexible Spending Accounts (FSAs) is that HSA funds do not expire at the end of the year. Any unused funds roll over year after year, accumulating over time. This allows for long-term planning for future healthcare needs, including potential retirement healthcare expenses.
Control and Empowerment
HSAs empower individuals to take a more active role in managing their health and finances.
- Informed Spending Decisions: When you are directly responsible for paying for your healthcare services up to a certain point, you are more likely to research options, compare prices, and make informed decisions about your care. This can lead to reduced unnecessary spending.
- Flexibility in Healthcare Choices: With funds readily available in your HSA, you have more flexibility to choose the healthcare providers and services that best meet your needs, rather than being restricted by a narrow network of providers often associated with lower-deductible plans.
- Long-Term Health Planning: The ability to accumulate funds over time allows individuals to plan for future medical needs, such as elective procedures, dental work, vision care, or even long-term care expenses in retirement, all funded through a tax-advantaged account.
Who is Best Suited for HSA-Compatible Plans?
While the benefits of HSA-compatible plans are significant, they are not universally ideal for everyone. Certain demographics and individuals tend to benefit the most.
The Young and Healthy
Individuals or families who are generally healthy, have minimal chronic conditions, and anticipate relatively low healthcare utilization may find HDHPs with HSAs to be a financially sound choice. The lower premiums can lead to substantial savings, and the ability to build up HSA funds provides a cushion for unexpected minor medical events.
The Financially Disciplined
HSAs require a degree of financial discipline. Individuals who are comfortable with budgeting, saving, and making proactive financial decisions will thrive with this model. The temptation to dip into HSA funds for non-medical expenses must be resisted to maximize its benefits.
Those Planning for the Future
Individuals who are thinking long-term, perhaps saving for a major purchase, planning for retirement, or anticipating future medical needs (e.g., starting a family, potential chronic conditions later in life), will find the accumulating, portable, and tax-advantaged nature of HSAs to be incredibly beneficial.
Individuals Seeking Tax Advantages
Anyone looking to maximize their tax savings and reduce their overall tax burden will find the triple tax advantage of HSAs to be a powerful financial tool.
Considerations and Potential Downsides
It is essential to acknowledge the potential challenges associated with HSA-compatible plans.
High Upfront Costs
The primary concern for many is the high deductible. If you experience a sudden illness or injury, you will be responsible for paying a significant amount out-of-pocket before your insurance coverage fully kicks in. This can be a financial strain if you do not have adequate savings in your HSA or elsewhere.
Potential for Unpredictable Healthcare Needs
For individuals with chronic conditions, frequent medical appointments, or ongoing treatment needs, an HDHP might not be the most suitable option. The out-of-pocket costs could become prohibitive, even with an HSA.
Requires Active Management
Unlike traditional plans where insurance companies often manage more of the financial aspects, an HSA requires active management by the account holder. This includes tracking expenses, understanding what is considered a qualified medical expense, and making timely contributions.
Conclusion
The term “HSA insurance” encapsulates a powerful combination of a High-Deductible Health Plan and a Health Savings Account. This pairing offers significant tax advantages, financial control, and long-term savings potential for individuals who are healthy, financially disciplined, and forward-thinking. By understanding the mechanics of both the HDHP and the HSA, consumers can make an informed decision about whether this approach to healthcare financing aligns with their personal health and financial goals. It’s a strategic choice that empowers individuals to take ownership of their healthcare journey, turning potential medical expenses into opportunities for tax-advantaged savings and investment.