
An Equity Line of Credit (HELOC) on a mortgage represents a dynamic and innovative financial instrument that empowers homeowners to leverage their most significant asset: their home equity. Unlike a traditional second mortgage which provides a lump sum payment, a HELOC functions much like a credit card, offering a revolving line of credit that can be drawn upon as needed, repaid, and then drawn again, up to an approved limit. This flexible access to capital, secured by the equity in one’s home, stands as a testament to ongoing innovation in personal finance, providing a versatile tool for managing expenses, funding significant projects, or consolidating debt.

At its core, a HELOC is a second mortgage, but its structure and operational mechanics differentiate it significantly. Lenders assess a homeowner’s available equity—the difference between the home’s current market value and the outstanding mortgage balance—to determine the maximum credit line. Typically, lenders allow homeowners to borrow up to a certain percentage of their home’s value, often ranging from 75% to 90%, minus the amount still owed on the primary mortgage. This innovative approach to accessing capital means homeowners can tap into their wealth without selling their property or refinancing their primary mortgage.
Understanding the Mechanics and Phases of a HELOC
The operational lifespan of a HELOC is typically divided into two distinct phases: the draw period and the repayment period. This dual-phase structure is a key innovative aspect, offering flexibility during the initial years followed by a structured repayment plan.
The Draw Period: Flexible Access to Capital
The draw period, often lasting 5 to 10 years, is the phase during which the homeowner can access funds from the approved credit line. During this time, borrowers have the flexibility to take out money as needed, up to their credit limit, and can choose to make interest-only payments on the amount borrowed. This “as-needed” access is a hallmark of the HELOC’s innovative design, providing liquidity without immediately incurring interest on the full credit line. For instance, if a homeowner has a $50,000 HELOC but only uses $10,000, interest is only charged on that $10,000. This flexibility is particularly valuable for ongoing projects or unexpected expenses, offering a modern alternative to multiple smaller loans.
The interest rate on a HELOC is almost exclusively variable, meaning it can fluctuate with market rates. This is typically tied to an index, such as the prime rate, plus a margin determined by the lender based on the borrower’s creditworthiness. While a variable rate introduces a degree of uncertainty regarding future payments, it also means borrowers can benefit when market interest rates fall. The technological advancements in financial tracking and digital banking mean homeowners can often monitor their interest rates and outstanding balances in real-time, enabling proactive financial management.
The Repayment Period: Structured Amortization
Once the draw period concludes, the HELOC transitions into the repayment period, which can last 10 to 20 years. During this phase, borrowers are no longer able to draw new funds. Instead, they must begin making principal and interest payments on the outstanding balance. These payments are typically amortized over the remaining term, similar to a traditional mortgage, ensuring the loan is fully repaid by the end of the period.
A critical consideration during this transition is the potential for “payment shock.” If a borrower was making interest-only payments during the draw period, the shift to principal and interest payments can lead to a significant increase in the monthly outlay. Financial technology tools and platforms are increasingly important here, allowing homeowners to model these scenarios, project future payments, and plan accordingly. Understanding this transition is vital for responsible use of a HELOC.
Innovative Applications and Benefits
The flexibility inherent in a HELOC makes it a powerful financial tool for a variety of purposes, showcasing its innovative role in personal finance management.

Home Improvement and Renovation
One of the most common and strategic uses for a HELOC is funding home improvement projects. Whether it’s a kitchen remodel, a new roof, or an extension, a HELOC provides readily available funds to enhance property value. Unlike taking out a series of smaller, higher-interest loans, a HELOC consolidates this borrowing into one revolving credit line, often at a lower interest rate, especially beneficial for projects with phased costs. The ability to draw funds as different stages of construction are completed aligns perfectly with the typical progression of a renovation project, minimizing interest accrual on unused capital.
Debt Consolidation
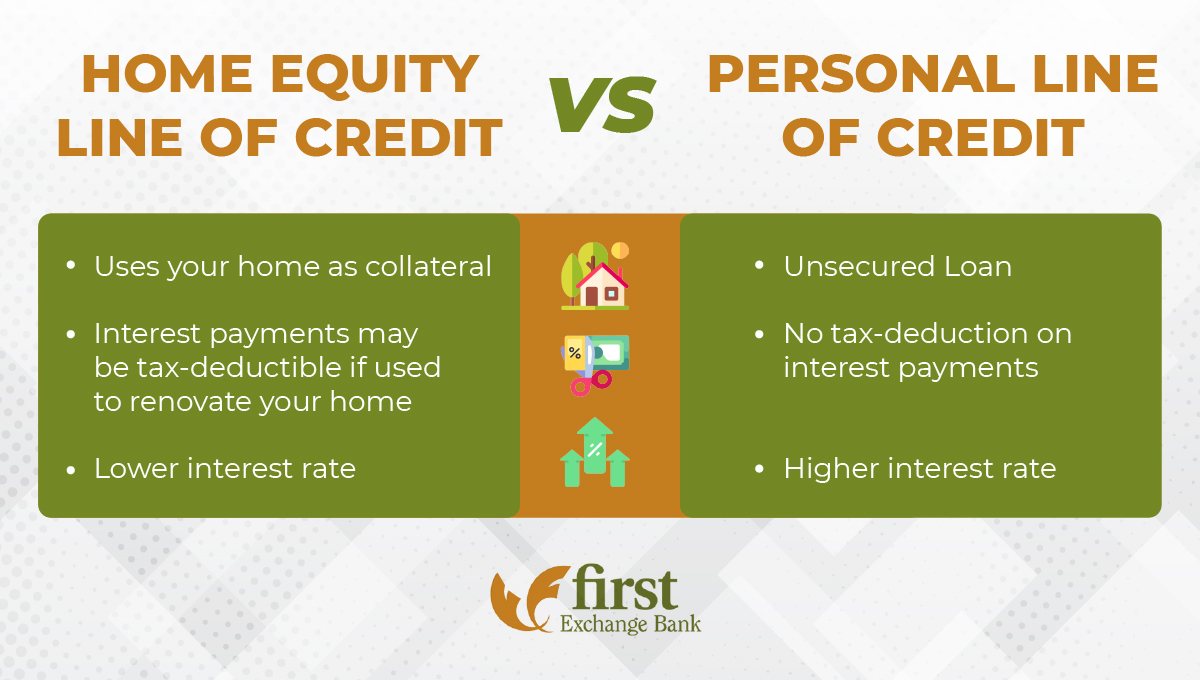
For homeowners burdened with high-interest credit card debt or personal loans, a HELOC can be an innovative solution for debt consolidation. By using a HELOC to pay off these higher-interest debts, borrowers can potentially reduce their overall monthly payments and save on interest costs over the long term. This strategy effectively converts unsecured, high-interest debt into lower-interest, secured debt. However, it’s crucial to understand the implications of securing consumer debt with one’s home, as failure to repay could lead to foreclosure.
Funding Major Expenses
Beyond renovations and debt consolidation, a HELOC can serve as a flexible funding source for other significant life events. This could include financing a child’s education, covering unexpected medical expenses, or even starting a small business. Its revolving nature means that if funds are repaid, they become available again, providing a financial safety net that traditional installment loans cannot match. This adaptability positions the HELOC as a modern financial instrument designed for varying, often unpredictable, needs.
Key Considerations and Risks
While a HELOC offers significant advantages and flexibility, it’s essential to approach it with a clear understanding of its inherent risks, demonstrating the importance of informed decision-making in financial innovation.
Variable Interest Rates
The primary risk associated with a HELOC is its variable interest rate. If market rates rise significantly, monthly payments can increase substantially, potentially straining a borrower’s budget. This necessitates a careful assessment of one’s financial resilience to rising rates and potentially incorporating a buffer into financial planning. Some lenders offer the option to convert all or a portion of the HELOC balance to a fixed rate during the draw period, which can mitigate this risk for a fee, an evolving feature reflecting financial innovation.
Risk to Home Equity and Foreclosure
Since a HELOC is secured by your home, failure to make payments can result in foreclosure. This is the most significant risk and underscores the importance of responsible borrowing. Unlike unsecured loans, your home is directly at stake. Diligent financial planning and a clear understanding of the repayment capacity are paramount.
Home Value Fluctuations
The amount of available equity is tied directly to your home’s market value. A downturn in the housing market could reduce your home’s value, potentially leaving you owing more than your home is worth (being “underwater”). In such scenarios, if your home value drops below the outstanding balance of your first mortgage and HELOC combined, your lender might freeze or reduce your credit line, preventing you from drawing additional funds when you might need them most. This dynamic interaction with market forces highlights the sophisticated risk profiles of such innovative financial products.
The Role of Technology and Future Outlook
The management and accessibility of HELOCs are increasingly intertwined with technological advancements. Online banking platforms allow for instant fund transfers, real-time balance checks, and automated payment setups. Digital tools help borrowers track their home equity, estimate potential credit lines, and model different repayment scenarios. This integration of technology enhances the user experience, making HELOCs more transparent and manageable.
As financial technology (FinTech) continues to evolve, we can anticipate further innovations in the HELOC space. This might include more sophisticated AI-driven credit assessment models, personalized repayment options, integration with broader financial planning software, and potentially even dynamic interest rate adjustments based on real-time economic indicators or borrower behavior. The journey of the HELOC from a simple concept of leveraging home equity to a sophisticated, flexible, and technologically-supported financial instrument exemplifies the continuous innovation in the financial services sector, aiming to provide consumers with more efficient and adaptable ways to manage their wealth and meet their financial goals.