Understanding the financial health and performance of any enterprise, particularly within the fast-paced and capital-intensive realm of Tech & Innovation, hinges on a clear grasp of profitability metrics. Among these, accounting profit stands as a foundational concept, offering a direct measure of a company’s financial success based on its explicit revenues and expenses over a specific period. It is the bottom line reported on financial statements, providing a crucial lens through which stakeholders, from investors to internal management, assess operational efficiency and overall viability.
The Fundamentals of Business Profitability
At its core, accounting profit is a straightforward calculation that reflects the surplus of revenue generated over the explicit costs incurred during a business cycle. It’s the profit that an accountant calculates and reports, adhering to generally accepted accounting principles (GAAP) or international financial reporting standards (IFRS). This metric is distinct from other profitability measures by focusing exclusively on tangible, recorded financial transactions.

Revenue: The Top Line
Revenue represents the total income generated by a company from its primary business activities before any expenses are deducted. In the context of Tech & Innovation, revenue can stem from a diverse array of sources:
- Product Sales: Selling hardware (e.g., drones, sensors, specialized cameras), software licenses, or integrated systems.
- Service Subscriptions: Recurring income from software-as-a-service (SaaS) platforms, data analytics subscriptions, or managed services for autonomous systems.
- Consulting and Development: Fees for custom solutions, R&D partnerships, or expert guidance in areas like AI integration, specialized mapping, or remote sensing applications.
- Licensing and Royalties: Income from intellectual property (IP) related to patented technologies, algorithms, or unique software functionalities.
For tech and innovation companies, revenue generation often involves a mix of upfront sales and recurring models, each with its own accounting nuances regarding recognition and timing. Accurate revenue tracking is the first critical step in determining profitability.
Explicit Costs: The Tangible Outlays
Explicit costs are the direct, out-of-pocket expenses that a business incurs in its operations. These are monetary costs, easily quantifiable, and recorded in a company’s ledger. In the Tech & Innovation sector, these can be substantial and varied:
- Research & Development (R&D): Salaries for engineers and scientists, costs of prototyping, testing equipment, software development tools, and materials for innovative projects like new drone designs or advanced AI algorithms.
- Manufacturing and Production: Costs of raw materials (e.g., carbon fiber for drone frames, electronic components), assembly labor, factory overheads, and quality control for hardware products.
- Employee Wages and Salaries: Compensation for all personnel, including developers, marketing teams, sales force, administrative staff, and executive leadership.
- Marketing and Sales Expenses: Advertising campaigns for new tech products, participation in industry conferences, commissions for sales teams, and digital marketing efforts to reach target audiences for innovative solutions.
- Administrative and Overhead Costs: Rent for offices or labs, utilities, insurance, legal fees (especially critical for IP protection in tech), and general office supplies.
- Depreciation and Amortization: The systematic expensing of tangible assets (like machinery, flight test facilities) and intangible assets (like patents, software development costs) over their useful life, reflecting their consumption in generating revenue.
- Cloud Computing and Infrastructure: Significant expenses for data storage, processing power, and specialized cloud services essential for AI, mapping, and large-scale data analytics platforms.
Accurately identifying and categorizing these explicit costs is paramount for financial reporting and for understanding the true cost structure of developing and deploying advanced technologies.
Calculating Accounting Profit in Practice
The calculation of accounting profit is fundamental to financial statements, particularly the income statement (or profit and loss statement). It serves as the primary indicator of an entity’s operational success and efficiency.
A Simple Formula
The most basic formula for accounting profit is:
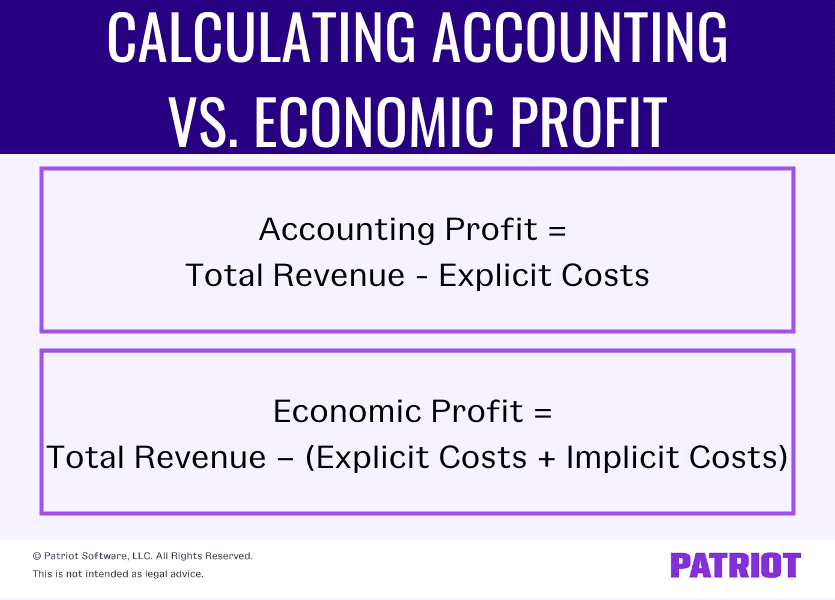
Accounting Profit = Total Revenue – Total Explicit Costs
For example, if a company specializing in autonomous drone delivery systems generates $50 million in revenue over a year from service contracts and hardware sales, and incurs $35 million in explicit costs (R&D, manufacturing, salaries, marketing, etc.), its accounting profit would be $15 million. This figure is often referred to as net income or net profit after all expenses, including taxes, have been accounted for.
Beyond the Basics: Depreciation and Amortization
While the formula appears simple, the ‘Total Explicit Costs’ can encompass complex items. Depreciation and amortization are crucial non-cash explicit costs in the tech sector.
- Depreciation: Applies to tangible assets, like manufacturing robots for drone components or high-end testing equipment for flight technology. It systematically allocates the cost of an asset over its useful life. For a drone manufacturer, a $1 million assembly line might be depreciated over 10 years, adding $100,000 annually to explicit costs, even though no cash is spent in that specific year for that portion of the asset.
- Amortization: Applies to intangible assets, such as patents for obstacle avoidance algorithms, developed software (e.g., flight control systems), or acquired intellectual property. If a company develops a unique AI navigation software at a cost of $5 million and expects it to be useful for 5 years, it would amortize $1 million annually.
These non-cash expenses reduce taxable income and reflect the consumption of assets, providing a more accurate picture of long-term profitability and asset utilization crucial for innovation-driven companies.
The Strategic Importance of Accounting Profit for Tech & Innovation
In the dynamic landscape of Tech & Innovation, accounting profit is more than just a number; it’s a strategic indicator that drives crucial business decisions, influences investor sentiment, and ultimately determines a company’s ability to innovate and sustain growth.
Informing Operational Decisions and Funding
For startups and established companies alike, accounting profit offers vital insights into the effectiveness of business models and operational strategies. A healthy accounting profit margin indicates that the company is efficiently converting its innovative ideas and technologies into tangible financial gains. This profitability allows tech companies to:
- Reinvest in R&D: Fund the next generation of AI algorithms, develop new drone capabilities, or explore breakthrough flight technologies without solely relying on external financing.
- Scale Operations: Expand production capabilities, hire more specialized talent (e.g., AI engineers, avionics experts), or enter new markets.
- Improve Cash Flow: While accounting profit isn’t cash, consistent profitability contributes to stronger cash reserves, providing a buffer against market fluctuations or unexpected R&D challenges.
- Attract Venture Capital and Loans: Profitability signals maturity and reduced risk to potential investors and lenders. Early-stage tech companies, while often unprofitable initially, must demonstrate a clear path to accounting profit to secure subsequent funding rounds.
Investor Relations and Market Perception
Publicly traded tech companies are scrutinized intensely on their profitability. Analysts and investors closely watch accounting profit figures to assess performance, project future earnings, and determine valuation. A company consistently reporting strong accounting profits can command higher stock prices and investor confidence. For private companies seeking acquisition or an IPO, demonstrating a track record of profitability is a significant valuation enhancer. It shows that the technology or service can not only attract users or customers but also do so in a financially sustainable manner.
Scaling and Sustainability in Dynamic Markets
The tech sector is characterized by rapid change and intense competition. Companies must constantly innovate to stay relevant. Achieving and maintaining accounting profit enables this long-term sustainability. It means the company isn’t just surviving on investment capital but is generating enough internal resources to fund its growth and innovation cycles. This is particularly relevant for companies developing complex systems like autonomous flight or advanced mapping, where initial R&D costs are high, but the potential for widespread adoption and recurring revenue streams can lead to substantial long-term profits.
Accounting Profit vs. Economic Profit: A Critical Distinction
While accounting profit provides a clear picture of reported earnings, it’s essential for strategic thinkers in Tech & Innovation to understand its distinction from economic profit. This comparison reveals a deeper truth about true value creation and resource allocation.
Understanding Opportunity Costs in Innovation
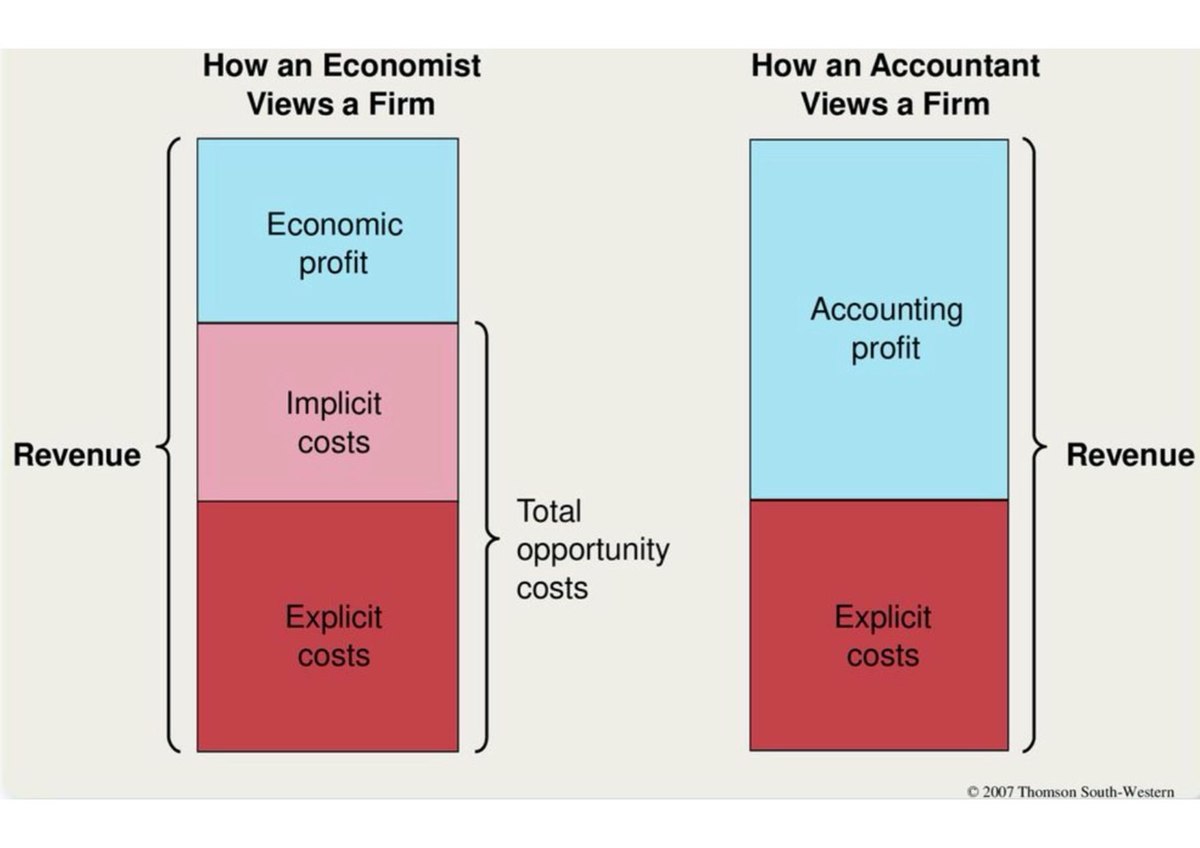
Economic profit factors in not only explicit costs but also implicit costs, primarily opportunity costs. An opportunity cost represents the value of the next best alternative that was foregone when a particular choice was made. For a tech company, this could mean:
- The potential profit from investing capital in a different R&D project instead of the chosen one.
- The salary that a founder could earn working for another company versus building their own startup.
- The return on investment (ROI) that could have been achieved by investing in a diversified portfolio instead of allocating capital to a new drone manufacturing facility.
Economic Profit = Accounting Profit – Implicit Costs (Opportunity Costs)
If a tech company earns an accounting profit, but an alternative investment of the same capital and effort would have yielded a higher return, then the economic profit is negative. This indicates that while the company is profitable on paper, it might not be the most efficient use of resources.
Strategic Implications for Tech Companies
For Tech & Innovation companies, where talent, capital, and intellectual property are highly sought after, considering economic profit is crucial for long-term strategic planning:
- Resource Allocation: Helps management decide if their current R&D focus or product line is truly the most beneficial use of their limited resources, prompting a re-evaluation if economic profit is low or negative.
- Investor Decisions: Venture capitalists and angel investors implicitly consider opportunity costs. They evaluate whether investing in a specific drone startup, for instance, offers a higher potential return than other available high-growth tech ventures.
- Sustainability: Companies need to generate at least zero economic profit (meaning, their accounting profit covers all explicit and implicit costs) to ensure they are creating enough value to justify their existence and continue attracting resources in a competitive market.
While accounting profit reports past performance, economic profit helps in forward-looking strategic assessments, especially pertinent for industries like Tech & Innovation that are constantly making choices about where to allocate scarce, valuable resources for future breakthroughs.
Challenges and Nuances in Tech & Innovation Context
The application and interpretation of accounting profit in the Tech & Innovation sector come with unique challenges and nuances that demand a sophisticated understanding.
R&D Investment and Future Profitability
Tech companies often pour significant resources into R&D, which directly impacts accounting profit. In many cases, R&D expenses are immediately expensed, reducing current period profits. This can lead to seemingly lower accounting profits for companies heavily invested in innovation, even if these investments are crucial for future blockbuster products or services.
- Balancing Act: Management faces the challenge of balancing current profitability with strategic long-term R&D investments. Too little R&D can stifle future innovation; too much can make a company appear unprofitable in the short term, potentially deterring investors.
- Capitalization vs. Expensing: While most R&D is expensed, specific development costs (e.g., software development costs meeting certain criteria) can be capitalized and amortized, spreading their impact on profit over time. This accounting choice can significantly alter reported accounting profit and is a key area of scrutiny.
Intangible Assets and Valuation
The value of many Tech & Innovation companies lies not just in their physical assets, but in their intangible assets: patents, proprietary algorithms, brand recognition, and a skilled workforce. While the costs to develop or acquire some intangibles are reflected in explicit costs (and amortized), the true economic value of these assets often far exceeds their book value.
- Undervaluation Risk: Relying solely on accounting profit without considering the underlying value of intangible assets can lead to an undervaluation of innovative companies, especially those with strong IP portfolios but modest current profits.
- Market Perception: The market often attributes a premium to tech companies with strong intangible assets, recognizing their potential for future accounting profits and competitive advantage, even if current accounting profits are not yet stellar.
In conclusion, accounting profit provides a fundamental and indispensable measure of financial performance. For companies in Tech & Innovation, it serves as a critical indicator for operational efficiency, investor attractiveness, and the capacity for sustainable growth and continued innovation. However, a deeper strategic understanding requires considering its relationship with economic profit and the unique accounting complexities inherent in developing and commercializing cutting-edge technologies.