
The Foundational Purpose of the VA Funding Fee
The VA funding fee is an essential component of the Department of Veterans Affairs (VA) home loan program, a benefit designed to help eligible veterans, service members, and surviving spouses purchase or refinance a home. Far from being an arbitrary charge, this fee serves a critical purpose: it helps to offset the costs of the VA loan program for U.S. taxpayers. Unlike conventional mortgages that often require private mortgage insurance (PMI) for borrowers with less than 20% down, VA loans do not require PMI, making homeownership more accessible and affordable for veterans. The funding fee is the mechanism by which the program remains self-sustaining, reducing the burden on taxpayers and ensuring the continued availability of this invaluable benefit.
Supporting the VA Loan Program
At its core, the VA funding fee acts as a direct contribution to the sustainability of the VA home loan program. This program guarantees a portion of the loan to approved lenders, significantly reducing the risk for these financial institutions. This guarantee is what allows lenders to offer favorable terms, such as no down payment requirements for many borrowers and competitive interest rates, without the need for PMI. The funds collected through the funding fee are deposited into a special VA-managed fund. This fund is then used to cover potential losses incurred by lenders when a VA-guaranteed loan defaults. Without the funding fee, the program would either require substantial direct taxpayer subsidies or lenders would be less inclined to participate, diminishing the availability and attractiveness of VA loans. By having borrowers contribute a small, one-time fee, the program can continue to operate robustly, fulfilling its mission to support veteran homeownership for generations to come.
Understanding the Fee’s Role in Lender Protection
The VA loan guarantee provides a vital layer of protection for lenders, encouraging them to extend credit to veterans who might otherwise face challenges in the conventional mortgage market. This protection is key to the program’s success. The funding fee directly contributes to the capital that backs these guarantees. In essence, it’s an upfront cost that fortifies the financial safety net, making VA loans a less risky proposition for banks and other mortgage providers. This mechanism ensures that even in economic downturns or instances of borrower default, lenders have a reliable recourse, maintaining their willingness to offer VA loans. For veterans, this means continued access to flexible qualification criteria and often more advantageous terms than those found in traditional lending, ultimately leading to greater homeownership opportunities. Understanding this protective role helps contextualize the fee not as an extra cost, but as an investment in the longevity and stability of a vital veteran benefit.
How the Funding Fee is Calculated and Applied
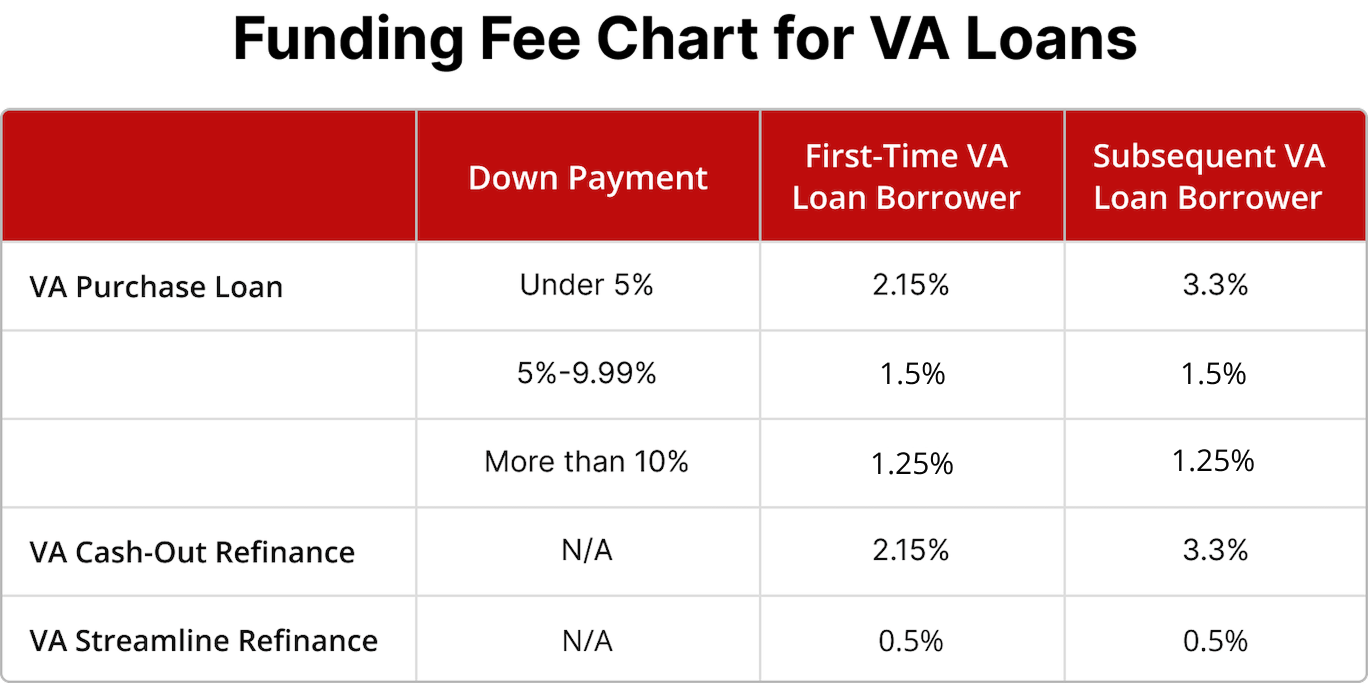
The VA funding fee is not a fixed amount; its rate varies based on several factors, including the type of loan, whether it’s the veteran’s first or subsequent use of the VA loan benefit, and the amount of the down payment. This nuanced calculation ensures that the fee is tailored to the specific circumstances of each loan, reflecting the risk profile and the borrower’s contribution. Generally, the fee is expressed as a percentage of the total loan amount and is typically financed into the loan, meaning it’s added to the principal balance and paid off over the life of the mortgage. However, borrowers have the option to pay the fee upfront if they choose, which can reduce their monthly payments and overall interest paid.
Variable Rates Based on Loan Type and Down Payment
The funding fee structure is designed with a graduated scale. For instance, a veteran using their VA loan benefit for the first time with no down payment on a purchase loan will pay a higher funding fee percentage compared to a veteran making a significant down payment. Similarly, subsequent users of the VA loan benefit, especially those who previously had a VA loan foreclose or default, face higher funding fee rates. Refinancing loans, such as Interest Rate Reduction Refinance Loans (IRRRLs) or cash-out refinances, also have their own specific funding fee rates. These variations reflect the program’s intent to balance its self-sustaining nature with the flexibility needed to serve a diverse group of borrowers. Transparency regarding these rates is crucial, and lenders are obligated to clearly explain the applicable fee to borrowers early in the loan process, often through digital tools that allow for quick estimation based on various scenarios.
Exceptions and Waivers for Eligible Veterans
Crucially, not all eligible individuals are required to pay the VA funding fee. The VA provides significant exceptions and waivers for certain categories of veterans and service members, acknowledging their unique sacrifices and circumstances. Veterans who receive VA compensation for service-connected disabilities are typically exempt from paying the funding fee. This exemption also extends to service members who are still on active duty but have received a proposed rating of eligibility for service-connected disability compensation, as well as surviving spouses of veterans who died in service or from a service-connected disability, provided they are receiving Dependency and Indemnity Compensation (DIC). It is imperative for eligible borrowers to verify their exemption status during the loan application process, as this can lead to substantial savings. The application process for determining exemption often involves providing documentation of disability ratings or DIC eligibility, which is then verified by the VA. Digital platforms and integrated systems have greatly streamlined this verification process, reducing delays and ensuring eligible veterans receive their rightful exemption.
Navigating the Funding Fee with Modern Tools and Systems
In today’s digital age, technology plays an increasingly vital role in demystifying complex financial processes like the VA funding fee. Modern tools and systems offer unparalleled transparency, efficiency, and personalized guidance, making it easier for veterans to understand, calculate, and manage their VA home loan benefits. From initial inquiries to final loan closing, technological innovation is transforming how veterans interact with the funding fee, ensuring they are well-informed and empowered throughout their homeownership journey.
Digital Platforms for Transparency and Calculation

The advent of sophisticated online platforms and mobile applications has revolutionized access to information about the VA funding fee. These digital tools often feature interactive calculators that allow prospective borrowers to input their specific circumstances – loan type, down payment amount, veteran status, and previous VA loan usage – to instantly estimate their applicable funding fee. This real-time calculation capability removes much of the guesswork, providing immediate clarity on potential costs. Beyond mere calculation, many platforms offer detailed explanations of how the fee is determined, outlining the different rate schedules and highlighting potential exemptions. They serve as central repositories for frequently asked questions, educational articles, and even video tutorials, empowering veterans to conduct thorough research and make informed decisions from the comfort of their homes. This level of digital transparency fosters trust and reduces the anxiety often associated with complex financial obligations.
AI-Assisted Guidance for Veteran Borrowers
Artificial intelligence (AI) and machine learning are beginning to transform the advisory landscape for VA loan borrowers. AI-powered chatbots and virtual assistants, integrated into lender websites and VA-related portals, can provide instant, round-the-clock support regarding the funding fee. These intelligent systems can answer common questions, guide users through the calculation process, and even identify preliminary eligibility for funding fee exemptions based on user input. Beyond simple Q&A, advanced AI algorithms can analyze a veteran’s financial profile and eligibility criteria to offer personalized recommendations, such as suggesting strategies to reduce the funding fee through a larger down payment or advising on the documentation needed for an exemption. This intelligent guidance can significantly streamline the information-gathering process, ensure accuracy, and free up human loan officers to focus on more complex cases requiring nuanced human interaction, ultimately enhancing the overall borrower experience.
Secure Data Management in Financial Transactions
The processing of VA loans and the associated funding fee involves handling sensitive personal and financial data. Robust cybersecurity and secure data management systems are paramount to protect veterans’ information from fraud and unauthorized access. Innovative encryption technologies, multi-factor authentication, and blockchain-inspired distributed ledger systems are increasingly being deployed to safeguard data throughout the loan application and closing process. These technologies ensure the integrity and confidentiality of documents related to eligibility, disability status, and financial disclosures. For the funding fee specifically, secure platforms facilitate the safe transfer of funds, whether it’s paid upfront or financed into the loan, ensuring that all financial transactions are executed with the highest level of security and compliance with regulatory standards. This focus on data integrity builds confidence in the digital processes and protects the financial well-being of veteran borrowers.
Strategic Financial Planning for VA Loan Borrowers
Understanding the VA funding fee is just one piece of the puzzle for veteran borrowers. Strategic financial planning involves looking at the fee within the broader context of the entire loan, including interest rates, closing costs, and long-term repayment. Borrowers must consider how the funding fee impacts their overall mortgage burden and explore available options to mitigate its financial impact, ensuring the VA loan remains a truly advantageous path to homeownership.
Weighing the Funding Fee Against Other Loan Costs
While the VA funding fee is a distinctive element of VA loans, it’s crucial to compare its cost against other potential expenses. For conventional loans, private mortgage insurance (PMI) is a recurring monthly cost for borrowers with less than 20% down payment, which can often amount to more than the one-time VA funding fee over the life of the loan. Furthermore, various closing costs, such as appraisal fees, title insurance, and origination fees, are standard across most mortgage types. Veterans should request a detailed loan estimate that itemizes all costs, allowing them to make an informed comparison. In many cases, even with the funding fee, a VA loan’s overall financial package—including no down payment and competitive interest rates—can be significantly more favorable than other mortgage products. Digital comparison tools can assist in this comprehensive analysis, presenting side-by-side cost breakdowns to highlight the true value proposition of a VA loan.
Refinancing Options and Their Associated Fees
For veterans who already have a mortgage, the VA offers various refinancing options, each with its own funding fee structure. The Interest Rate Reduction Refinance Loan (IRRRL), also known as a VA streamline refinance, is popular for its simplicity and typically lower funding fee (currently 0.5%). This option allows veterans to refinance an existing VA loan to get a lower interest rate or move from an adjustable-rate to a fixed-rate mortgage with minimal documentation. In contrast, a VA cash-out refinance allows veterans to convert home equity into cash, often involving a higher funding fee similar to that of a purchase loan. Understanding these distinct funding fee implications is vital for veterans considering refinancing. Advanced online calculators can help model different refinancing scenarios, projecting the impact of the funding fee on new monthly payments and total interest paid, thus guiding veterans toward the most financially sound decision for their specific goals.
Future Outlook: Enhancing the Veteran Homeownership Experience
The VA home loan program has consistently evolved to meet the changing needs of veterans, and the funding fee, as a core component, is also subject to ongoing review and potential refinement. The future holds opportunities for even greater integration of technology and policy adjustments aimed at further simplifying the process and maximizing the benefits for those who have served.
Continuous Improvement in Digital Services
The trajectory of digital innovation points towards even more seamless and intuitive experiences for veterans navigating the VA loan process. Expect advanced personalized dashboards that centralize all loan-related information, smart notifications that alert borrowers to important deadlines or policy changes, and integrated communication tools that connect veterans directly with loan officers and VA representatives. The goal is to reduce friction points, minimize paperwork, and empower veterans with instant access to the information and support they need regarding the funding fee and other loan aspects. Future digital services may also incorporate predictive analytics to anticipate common veteran questions or hurdles, offering proactive solutions and tailored educational content, making the journey from application to closing as smooth and transparent as possible.

Policy Adjustments and Their Technological Implications
Changes to the VA funding fee rates or exemption criteria are periodically reviewed by Congress and the VA. Any future policy adjustments, whether minor tweaks or significant overhauls, will invariably have technological implications. For instance, if new categories of veterans become eligible for waivers, or if the fee structure itself is modified, digital systems will need to rapidly adapt to reflect these changes accurately. This requires agile software development and robust backend systems capable of real-time updates to ensure that online calculators, lender platforms, and VA portals all display the most current and correct information. Furthermore, advancements in data privacy and security will continue to be paramount, ensuring that any new digital processes align with evolving regulatory standards and maintain the highest level of protection for veterans’ sensitive financial and personal data. The intersection of policy and technology will continue to shape how the VA funding fee is understood, calculated, and ultimately managed for the benefit of veteran homeownership.