
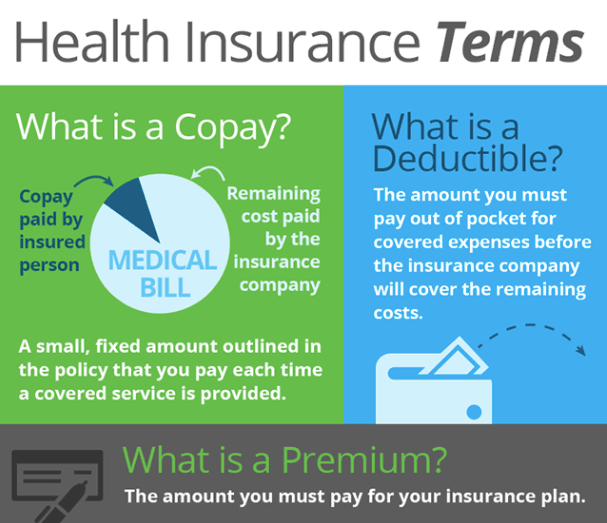
Understanding the intricacies of health insurance can often feel like navigating a complex maze. Among the various terms and concepts, the “deductible” stands out as one of the most fundamental and often misunderstood components. A healthcare deductible is the amount of money you must pay out-of-pocket for covered medical services before your health insurance plan begins to pay. It’s a critical element that directly impacts your financial responsibility for healthcare costs, influencing everything from routine check-ups to emergency procedures and chronic disease management. Grasping what a deductible is, how it works, and its various forms is essential for making informed decisions about your health coverage and managing your medical expenses effectively.
The Core Concept of a Deductible
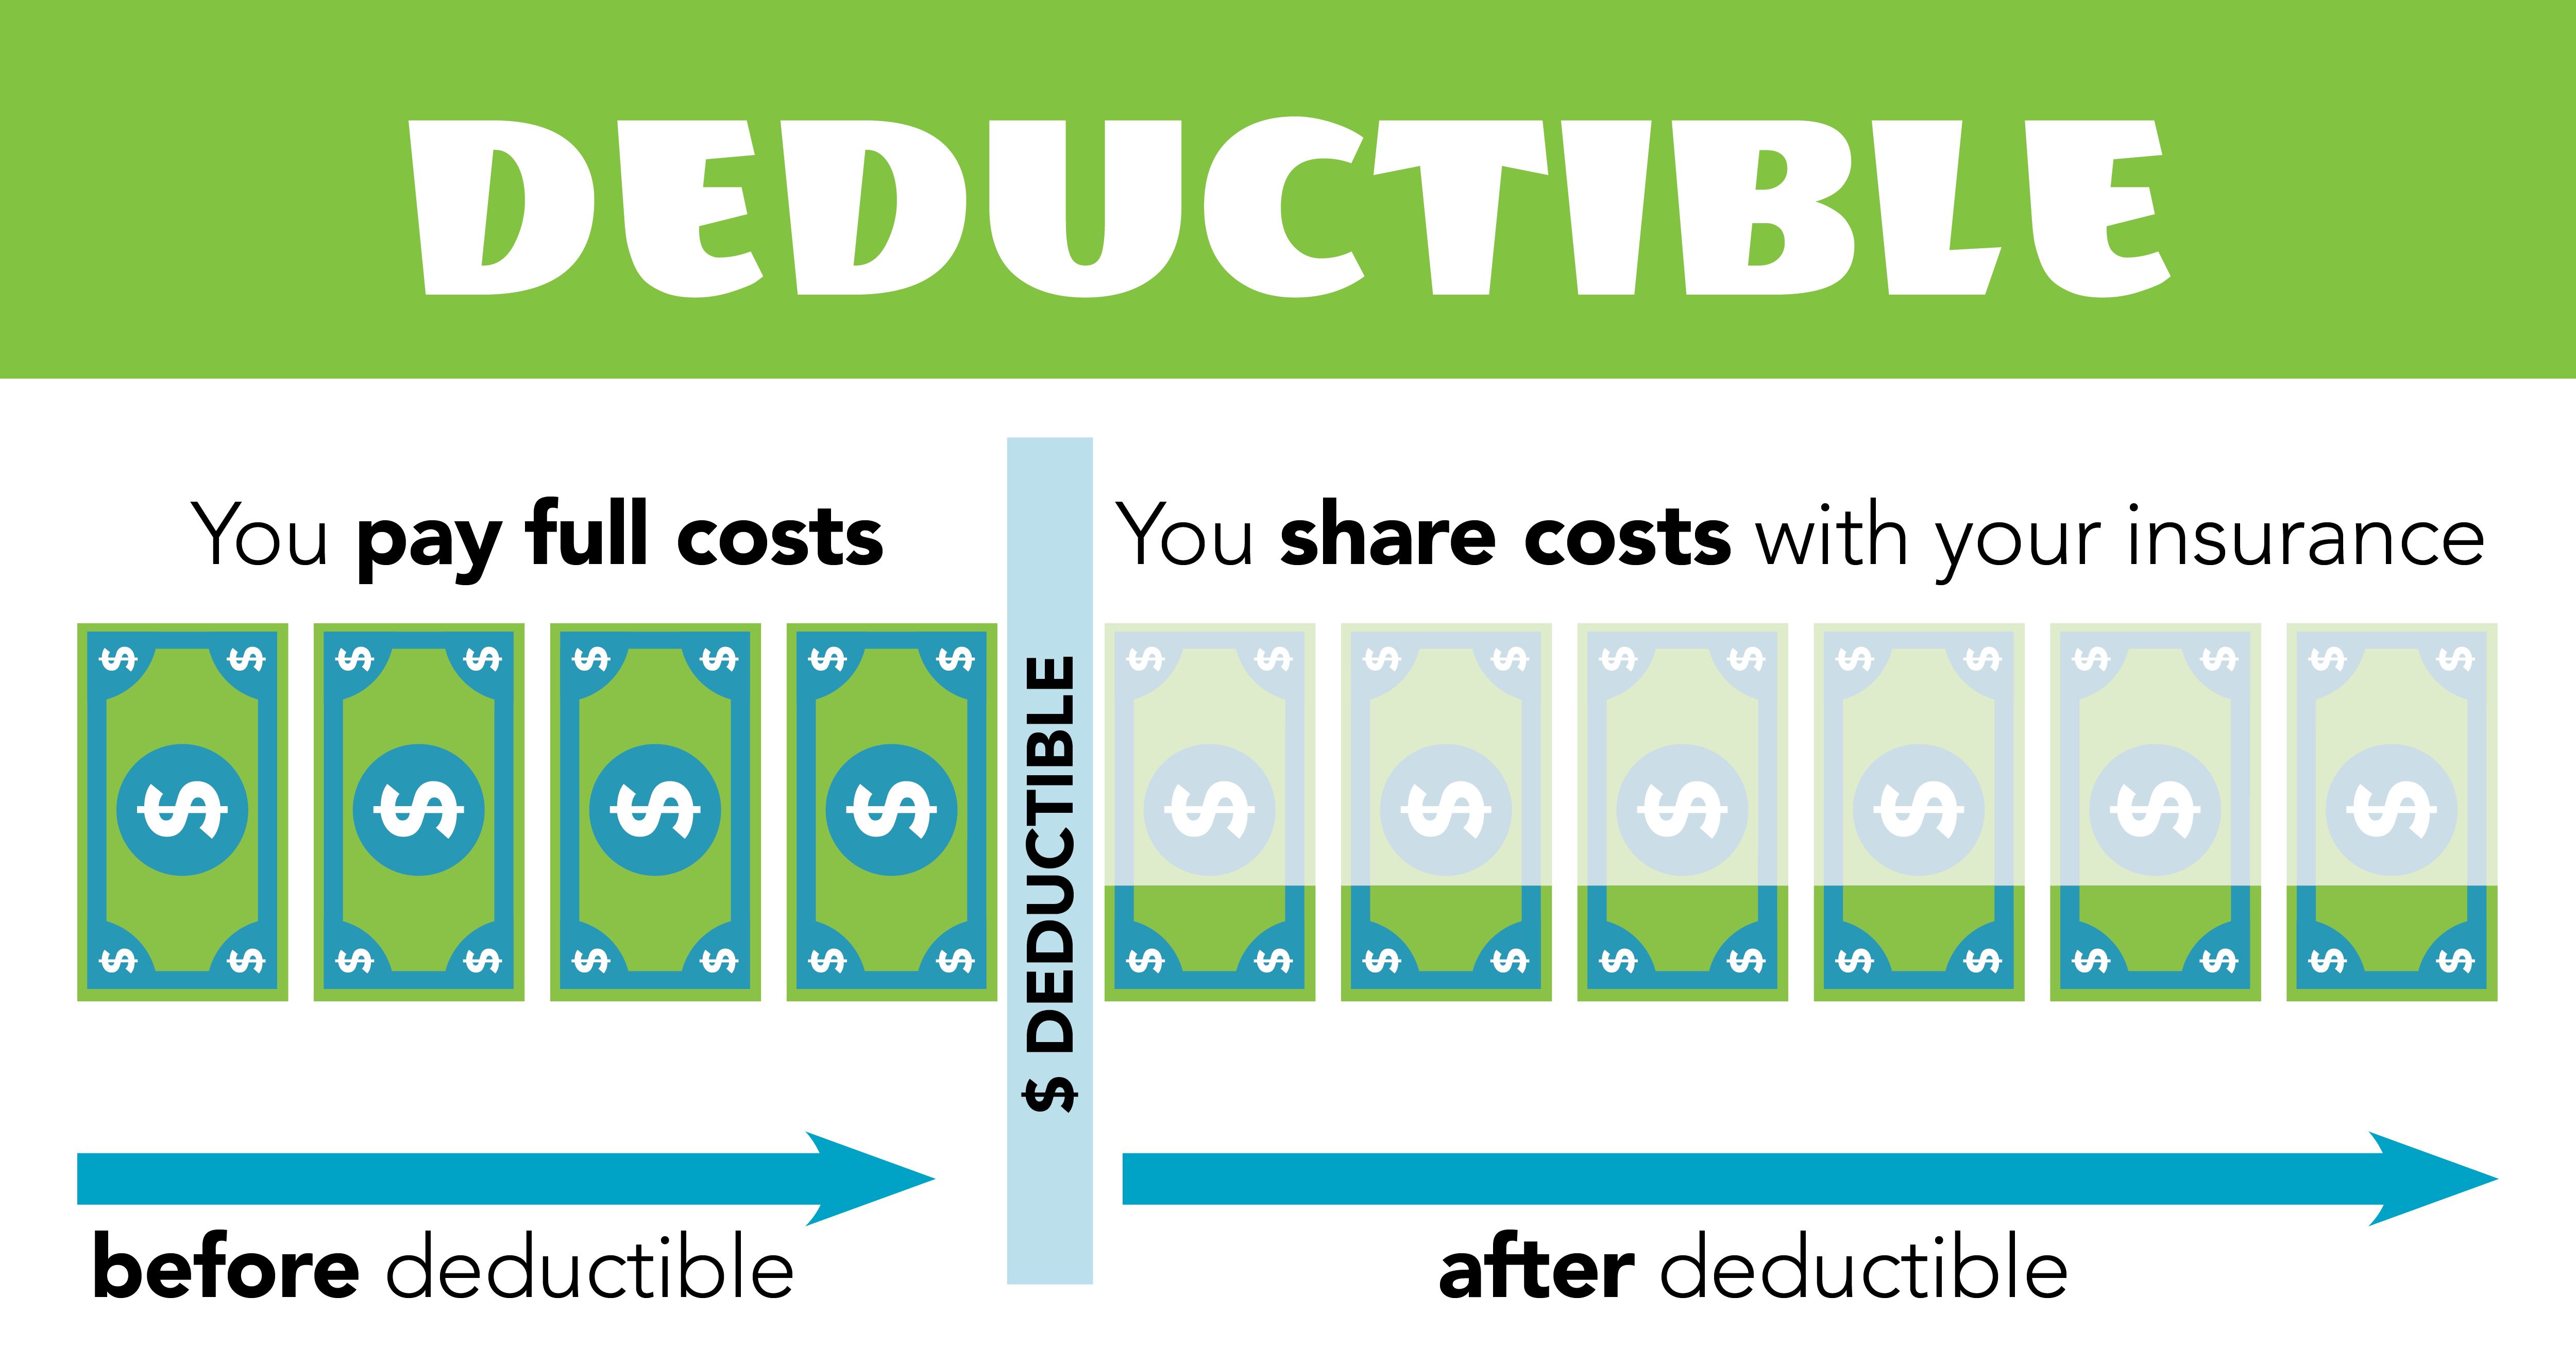
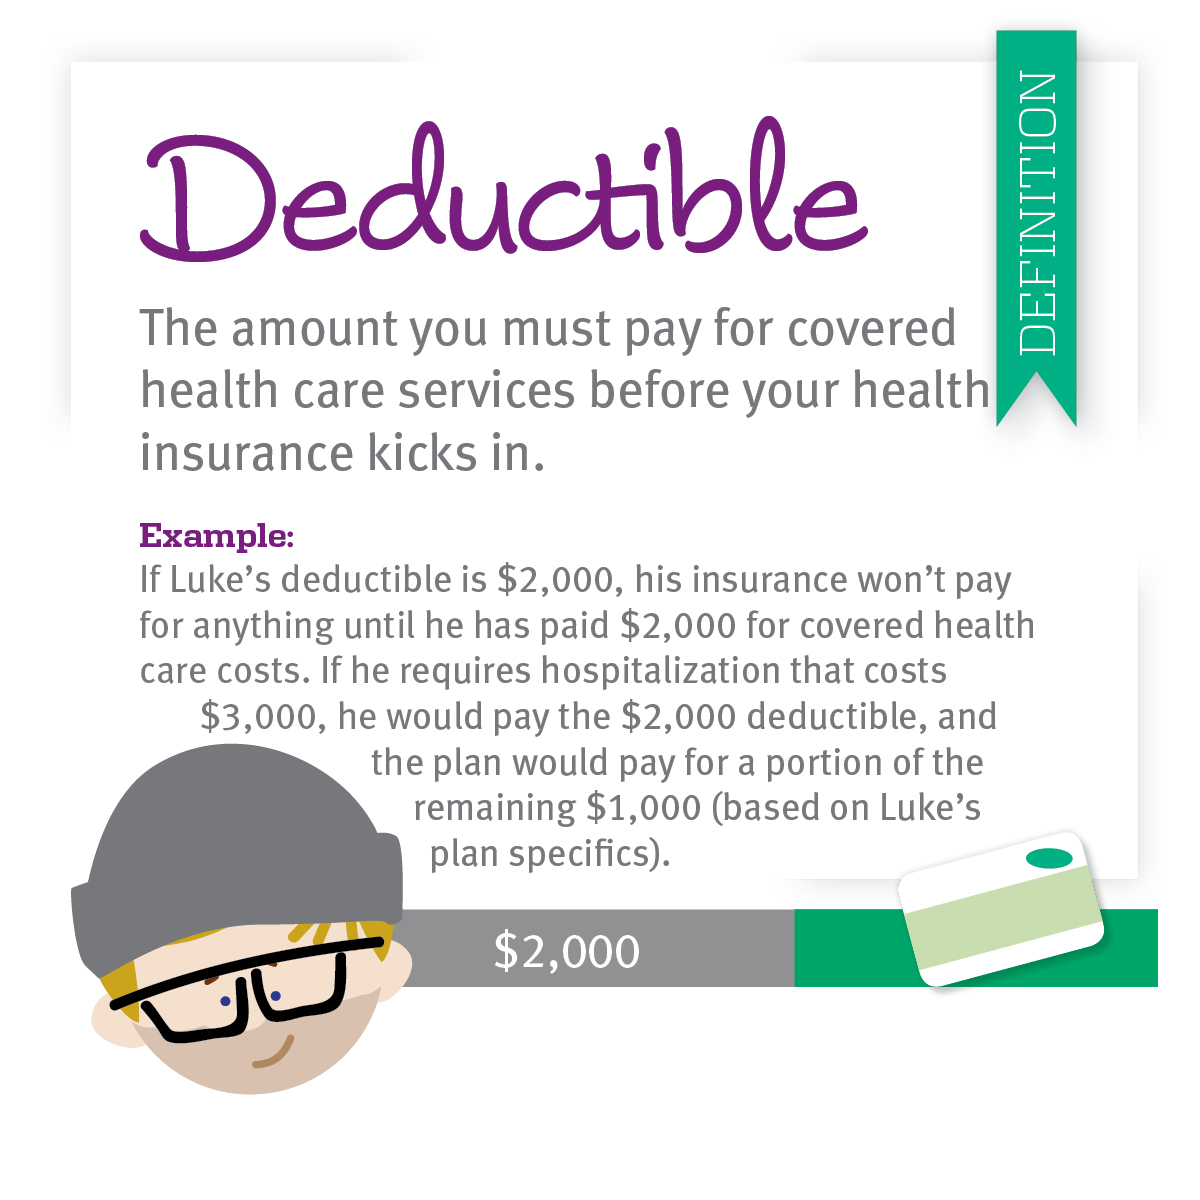
At its heart, a deductible acts as a threshold. Imagine your health insurance as a safety net, but before that net fully catches you, there’s a certain distance you must fall on your own. That distance is your deductible. Each year, your policy will specify a deductible amount – for instance, $1,000, $2,500, or even higher. Until you have paid this amount for covered services, your insurance plan will not contribute financially, beyond perhaps offering certain preventive care services for free.
Once you’ve accumulated eligible medical expenses that meet or exceed your deductible, your insurance “kicks in.” This doesn’t necessarily mean they start paying 100% of your costs immediately. Often, after the deductible is met, you enter a phase known as “coinsurance,” where your plan pays a percentage of costs, and you pay the remaining percentage (e.g., 80/20 coinsurance means the plan pays 80%, you pay 20%). This continues until you reach your out-of-pocket maximum, at which point the insurance typically covers 100% of covered services for the rest of the policy year.
It’s crucial to distinguish a deductible from your monthly premium. Your premium is the fixed amount you pay regularly (monthly, quarterly, or annually) to keep your health insurance coverage active. This payment is separate from and does not count towards your deductible. Whether you use medical services or not, you must pay your premium to maintain coverage. The deductible, on the other hand, only comes into play when you receive medical care that your plan covers.
How Deductibles Reset
Most health insurance deductibles operate on an annual cycle, typically aligning with the calendar year (January 1 to December 31). This means that any medical expenses you incur towards your deductible will accumulate over that specific year. Once the new year begins, your deductible resets to zero, and you must meet it again before your insurance begins to pay for services in that new policy period. This annual reset is a significant factor in financial planning for healthcare, as it means even if you met a substantial deductible late in the year, you’ll face the same financial responsibility early in the next year if you need further medical care.
The Trade-off: Premiums vs. Deductibles
There’s often a direct correlation between the amount of your deductible and the cost of your monthly premium. Generally, plans with lower deductibles tend to have higher monthly premiums, and vice-versa. This presents a key decision point when choosing a health insurance plan:
- High-Deductible Health Plans (HDHPs): These plans feature lower monthly premiums but require you to pay a larger amount out-of-pocket before your insurance coverage begins. HDHPs are often paired with Health Savings Accounts (HSAs), which allow you to save money tax-free for medical expenses. They can be attractive to individuals who anticipate needing less medical care and prefer lower monthly costs.
- Low-Deductible Health Plans (LDHPs): These plans come with higher monthly premiums but offer the benefit of your insurance coverage starting sooner. LDHPs are generally preferred by individuals or families who expect frequent medical needs, manage chronic conditions, or simply desire more predictable out-of-pocket costs when seeking care.
Choosing between a high or low deductible plan requires careful consideration of your health status, anticipated medical needs, risk tolerance, and financial situation. A healthy individual with emergency savings might opt for an HDHP, while someone with ongoing medical conditions might find an LDHP more cost-effective in the long run.
Types and Variations of Deductibles
While the basic concept remains consistent, deductibles can manifest in several different forms, depending on the specific health insurance plan and its structure. Understanding these variations is crucial for interpreting your policy documents accurately.
Individual vs. Family Deductibles
For family health insurance plans, deductibles are often structured in one of two ways:
- Individual Deductible: Each covered family member has their own separate deductible that they must meet. Once an individual meets their deductible, the plan starts paying for their covered services.
- Family Deductible: This is a single, higher deductible amount that applies to the entire family. Once the combined eligible medical expenses of all family members reach this family deductible, the plan begins paying for all covered family members’ services, regardless of whether each individual has met their individual share. Some family plans may also have a “per-person” deductible with an “overall family maximum” deductible, meaning no single person has to meet the full family amount, but the family as a whole must meet it.
The rules for how individual contributions count towards a family deductible can vary significantly. Some plans might require two or three individuals to meet their individual deductibles before the family deductible is considered met, while others pool all family members’ expenses. Always check your specific plan’s Summary of Benefits and Coverage (SBC) for these details.
Embedded vs. Non-Embedded Deductibles
These terms primarily apply to family plans:
- Embedded Deductible: In a family plan with an embedded deductible, each individual in the family has an individual deductible (which is typically lower than the family deductible), and the family also has an overall family deductible. If any single family member meets their individual deductible, the plan starts paying for their services, even if the overall family deductible hasn’t been met yet. However, the plan will not pay for other family members until either they meet their individual deductible or the total family deductible is met.
- Non-Embedded (Aggregate) Deductible: With a non-embedded deductible, there is only one large family deductible. No individual deductibles apply. The plan will not pay for any family member’s services until the cumulative medical expenses of all family members combined meet the full family deductible amount. This structure often means higher out-of-pocket costs for the family before benefits kick in.
Understanding whether your family plan has an embedded or non-embedded deductible is vital for financial planning, especially if one family member has significant medical needs.
Deductibles for Specific Services
In some health insurance plans, you might encounter separate deductibles for different categories of services. For example:
- Prescription Drug Deductible: Some plans have a separate deductible specifically for prescription medications. This means you would need to meet this drug deductible before the plan contributes to your medication costs, even if you’ve already met your medical deductible for doctor visits or hospital stays.
- Out-of-Network Deductible: If your plan offers out-of-network coverage, it almost certainly has a separate, and usually much higher, deductible for services received from providers outside of your plan’s network. This is a common feature designed to incentivize members to use in-network providers.
- Tiered Deductibles: Less common, but some plans might have different deductible amounts based on the type of service (e.g., a lower deductible for primary care, a higher one for specialist visits).
These specific deductibles add another layer of complexity, emphasizing the importance of thoroughly reviewing your plan’s benefits.
Impact on Financial Planning and Healthcare Decisions
The deductible plays a monumental role in how you approach your healthcare and manage your personal finances.
Budgeting for Unexpected Costs
A high deductible means you must be prepared to pay a substantial amount for medical care if you get sick or injured. It’s wise to have an emergency fund specifically earmarked for potential healthcare expenses, especially if you have an HDHP. Knowing your deductible amount allows you to budget proactively and avoid financial stress when medical needs arise. For those with chronic conditions, understanding the deductible helps in planning for regular treatments, medications, and specialist visits.
Choosing Providers and Services
Your deductible can influence your decisions about seeking care. If you have a high deductible that hasn’t been met, you might be more inclined to compare costs for procedures or choose generic medications. It can also make you more conscious of utilizing in-network providers, as out-of-network services often don’t count towards your in-network deductible and may have their own, higher out-of-network deductible.
Maximizing Benefits
Understanding your deductible helps you maximize your insurance benefits. For instance, knowing which services are covered before your deductible (like preventive care, which is often 100% covered) can help you stay healthy without immediate out-of-pocket costs. Once your deductible is met, you become aware that your coinsurance phase has begun, potentially making further necessary medical care more affordable. Tracking your accumulated expenses towards your deductible throughout the year is good practice to understand your current financial standing relative to your plan benefits.
In conclusion, a healthcare deductible is far more than just a number on your insurance card; it’s a pivotal component of your health insurance architecture that dictates a significant portion of your financial responsibility for medical care. By understanding its definition, how it functions, its various types, and its annual reset, individuals and families can make more informed choices about their health plans, better manage their healthcare budgets, and confidently navigate the complexities of the healthcare system.