
A Grantor Retained Annuity Trust (GRAT) stands as a sophisticated and often misunderstood instrument within the realm of estate planning. At its core, a GRAT is an irrevocable trust established by an individual (the grantor) who transfers assets into it for a specified term of years. In return, the grantor receives a series of fixed annuity payments back from the trust for the duration of that term. Upon the expiration of the trust term, any remaining assets within the trust, along with any appreciation in value above a predetermined interest rate (known as the Section 7520 rate or hurdle rate), pass to the designated beneficiaries, often the grantor’s children or other heirs, free of additional gift or estate tax.
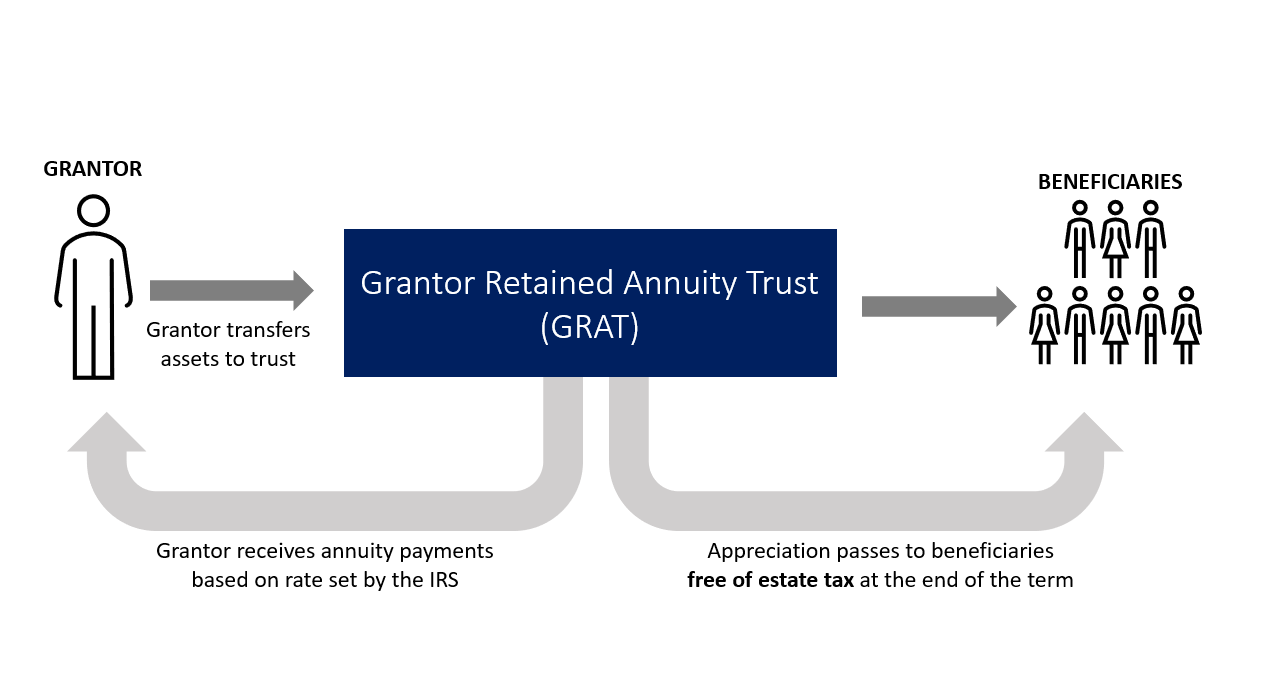
The primary objective of establishing a GRAT is to transfer wealth to future generations in a tax-efficient manner, particularly when the grantor anticipates that the assets placed into the trust will appreciate significantly during the trust term. It leverages the legal framework to “freeze” the value of the gift for tax purposes at the time the trust is created, allowing future growth to bypass the grantor’s taxable estate. This strategic use of a trust structure exemplifies a form of financial innovation that has proven remarkably resilient and adaptable through various economic cycles and legislative changes, presenting complex challenges and opportunities for integration with modern technological solutions.
The Core Mechanics of a Grantor Retained Annuity Trust
Understanding the precise mechanics of a GRAT is crucial to appreciating its innovative potential within a tech-driven financial ecosystem. It operates on a principle of calculated risk and projected growth, designed to optimize asset transfer.
Establishing the Trust
The process begins with the grantor drafting an irrevocable trust agreement, specifying the terms, duration, annuity payment schedule, and ultimate beneficiaries. Key to this initial phase is the selection of assets to be transferred. These typically include assets expected to appreciate substantially, such as shares in a privately held company, real estate, or marketable securities. The valuation of these assets at the time of transfer is critical, as it determines the initial gift amount for tax purposes. In a digitally evolving world, this valuation process itself could benefit from AI-powered predictive analytics and automated data aggregation, streamlining a historically cumbersome task.
The Annuity Payment Phase
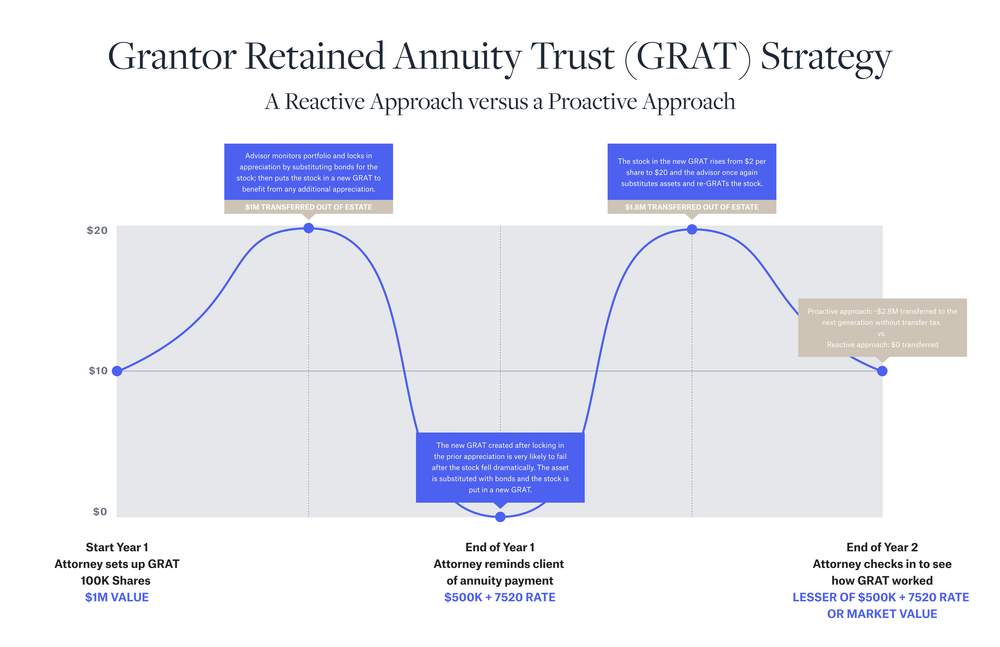
Once assets are transferred, the trust begins making annuity payments back to the grantor. These payments can be made annually, semi-annually, quarterly, or monthly, and can be structured as level payments or increasing payments (often up to 20% year-over-year). The total value of these annuity payments is intentionally designed to “zero out” the initial gift for gift tax purposes. This means the present value of the annuity stream paid back to the grantor should be approximately equal to the fair market value of the assets initially contributed to the trust, based on the IRS Section 7520 interest rate. If successfully “zeroed out,” the taxable gift to the beneficiaries at the time of the trust’s creation is negligible, or even zero. The magic of the GRAT lies in the asset appreciation that exceeds the Section 7520 rate. If the assets grow faster than this hurdle rate, that excess growth passes to the beneficiaries tax-free.
Beneficiary Remainder Interest
At the end of the specified trust term, if the assets have appreciated beyond the rate necessary to fund the grantor’s annuity payments, the remaining assets are distributed to the designated beneficiaries. This “remainder interest” represents the wealth successfully transferred outside the grantor’s estate without incurring significant gift or estate tax. This entire process, from asset transfer and valuation to annuity calculation and beneficiary distribution, involves intricate financial modeling and legal compliance, making it a prime candidate for innovative technological solutions that enhance efficiency, accuracy, and transparency.
GRATs in the Digital Age: An Innovative Framework for Wealth Transfer
While GRATs have traditionally been managed through conventional legal and financial services, the principles underlying their structure – systematic asset management, precise calculation, and future-oriented wealth transfer – are highly amenable to innovation, particularly in a tech-forward environment.
Traditional Application and Modern Challenges
Historically, setting up and administering a GRAT involved extensive manual calculations, legal drafting, and ongoing oversight by financial advisors and attorneys. Challenges included accurate asset valuation, especially for illiquid assets, meticulous tracking of annuity payments, and ensuring compliance with ever-changing tax regulations. The static nature of traditional trust management often lagged behind dynamic market conditions, limiting real-time adaptability and optimization. Moreover, the lack of immediate, transparent data often made it difficult for grantors to fully visualize and adjust their strategies.
Leveraging Technology for Enhanced GRAT Administration
The advent of advanced analytics, cloud computing, and secure digital platforms offers unprecedented opportunities to streamline and enhance GRAT administration. Imagine a system where asset valuations are automatically updated based on market data feeds, annuity payments are scheduled and processed with smart contracts, and compliance checks are performed in real-time. This not only reduces the administrative burden and potential for human error but also provides grantors and their advisors with dynamic insights, allowing for more informed decision-making and potentially more effective wealth transfer strategies. This shift moves GRAT management from a purely static legal document to a living, dynamic financial mechanism capable of responding to market shifts.
Emerging Technologies and the Future of GRATs
The intersection of sophisticated financial instruments like GRATs and cutting-edge technologies promises a future of greater efficiency, transparency, and adaptability in wealth management. This represents a significant area for innovation within financial technology.
Blockchain and Smart Contracts for Trust Automation
Blockchain technology, with its immutable ledger and decentralized nature, offers a compelling solution for the automated execution and administration of GRATs. Smart contracts, self-executing contracts with the terms of the agreement directly written into code, could be programmed to manage annuity payments, track asset appreciation, and trigger the final distribution to beneficiaries automatically upon the trust’s termination. This would eliminate the need for intermediaries in many administrative functions, reduce costs, enhance security, and provide an auditable, transparent record of all transactions within the trust. Imagine a “decentralized GRAT” where the rules are coded and enforced cryptographically.
AI-Driven Portfolio Optimization and Risk Management
Artificial intelligence and machine learning algorithms can revolutionize the strategic planning and ongoing management of assets within a GRAT. AI could analyze vast datasets to predict asset performance, identify optimal asset allocation strategies to maximize appreciation above the Section 7520 rate, and dynamically adjust portfolios to mitigate risks. Furthermore, AI could provide sophisticated scenario planning, allowing grantors to model various market conditions and their potential impact on the GRAT’s success, optimizing the trust term and annuity structure for maximum benefit. This moves beyond simple actuarial tables to predictive, adaptive financial modeling.
Digital Asset Integration and Estate Planning Innovation
As digital assets like cryptocurrencies, NFTs, and tokenized securities become increasingly prevalent, the ability to incorporate them effectively into estate planning structures like GRATs becomes critical. Innovative platforms are emerging that allow for the secure transfer, valuation, and management of these digital assets within traditional trust frameworks. Tech-driven solutions could provide robust mechanisms for authenticating ownership, managing private keys, and ensuring the smooth transfer of these unique asset classes, expanding the utility and relevance of GRATs in an increasingly digital economy. This represents a frontier for wealth transfer, where traditional legal instruments meet novel asset types.
Considerations and Strategic Implementation in a Tech-Forward World
Adopting these technological innovations for GRATs requires careful consideration of various factors to ensure successful and compliant implementation. The promise of efficiency must be balanced with the realities of security and regulation.
Legal and Regulatory Evolution
The integration of blockchain, AI, and smart contracts into GRAT administration necessitates a corresponding evolution in legal and regulatory frameworks. Legislators and legal professionals must adapt to define the legal enforceability of smart contracts in this context, address issues of jurisdiction, and ensure robust consumer protection. Innovation in this space will be a collaborative effort between technologists, legal experts, and regulatory bodies to create a supportive ecosystem for digital wealth management.
Security and Data Integrity
With increased automation and digital storage of sensitive financial information, robust cybersecurity measures are paramount. Blockchain’s inherent security features provide a strong foundation, but platforms integrating AI and other tools must implement multi-layered security protocols to protect against cyber threats, data breaches, and unauthorized access. Ensuring data integrity and privacy will be a continuous, evolving challenge that sophisticated tech solutions are designed to meet.

The Role of Expert Platforms
While technology can automate many processes, the complex nature of GRATs, particularly regarding tax implications and unique family dynamics, will always require the expertise of human advisors. Innovative platforms will likely emerge as collaborative tools, empowering financial advisors, estate planners, and legal professionals with advanced data analytics, automation capabilities, and compliance tools. This synergy between human expertise and technological innovation will define the next generation of GRAT planning and administration, enabling more efficient, customized, and resilient wealth transfer strategies for a modern age.