
Understanding the forward rate is crucial for anyone involved in financial markets, particularly those dealing with futures, forwards, and interest rate derivatives. In essence, a forward rate is a pre-determined interest rate for a future loan or deposit. It’s not the current rate, but rather the rate agreed upon today for a transaction that will occur at a specified point in the future. This concept is fundamental to hedging against future interest rate volatility and for speculative purposes.
The Mechanics of Forward Rates
The forward rate is intrinsically linked to the current spot rates and the time value of money. It’s calculated to ensure that there’s no arbitrage opportunity between entering into a series of spot transactions versus entering into a single forward transaction. Essentially, the market implies the forward rate from the existing yield curve.
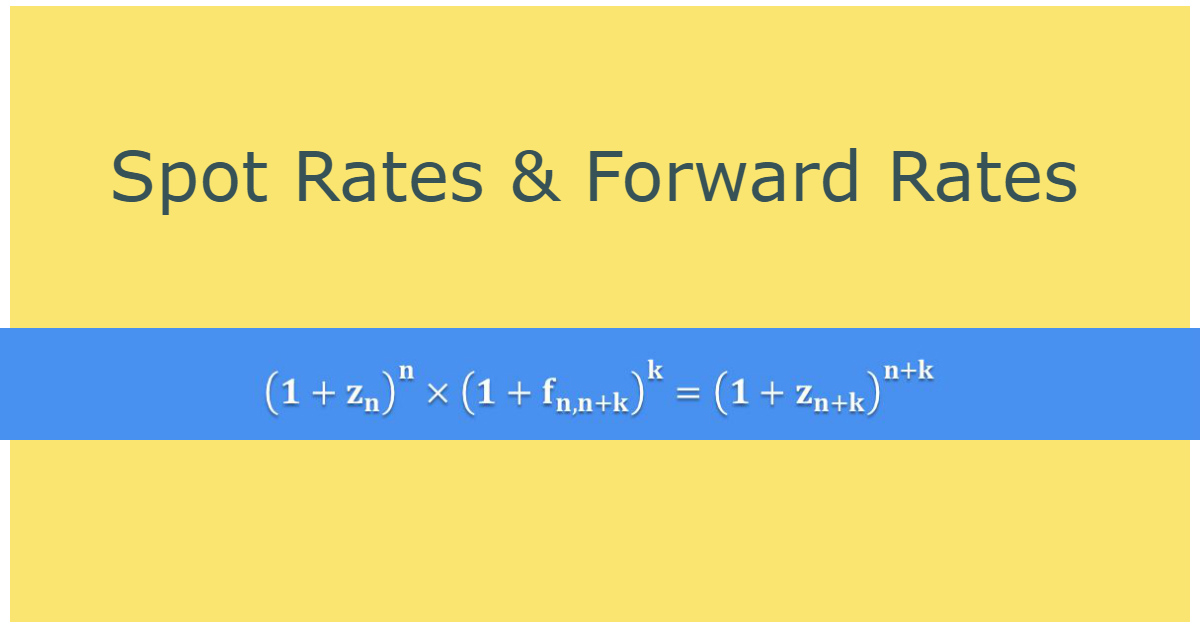
Spot Rates vs. Forward Rates
To grasp forward rates, it’s essential to differentiate them from spot rates.
Spot Rates
A spot rate is the interest rate for a loan or deposit that begins immediately and matures at a specific future date. For instance, if you can currently invest money for one year at 5% per annum, that 5% is the one-year spot rate. If you can invest for two years at 6% per annum (compounded annually), that 6% is the two-year spot rate.
Forward Rates
A forward rate, on the other hand, is the interest rate agreed upon today for a loan or deposit that will commence at a future date and mature at a later date. For example, a one-year forward rate starting in one year would be the rate applicable to a loan or deposit that begins in one year and lasts for one year.
The Relationship: No Arbitrage
The core principle underpinning the relationship between spot rates and forward rates is the no-arbitrage condition. This means that an investor should be indifferent between two investment strategies that yield the same outcome.
Consider two scenarios for investing money for two years:
- The “One-Step” Approach: Invest the money for two years at the current two-year spot rate.
- The “Two-Step” Approach: Invest the money for one year at the current one-year spot rate, and then reinvest the principal and earned interest for the second year at the one-year forward rate that begins in one year.
According to the no-arbitrage principle, the total return from both approaches must be identical. If they weren’t, an investor could borrow at the lower rate and lend at the higher rate, making a risk-free profit.
This relationship can be expressed mathematically. Let:
- $S_{n}$ be the spot rate for a period of $n$ years.
- $F_{m, n}$ be the forward rate for a period of $n$ years starting at time $m$.
For a two-year investment (where $n=2$) and a one-year forward rate starting in one year (where $m=1, n=1$), the no-arbitrage equation is:
$(1 + S{2})^{2} = (1 + S{1})(1 + F_{1,1})$
Where:
- $S_{2}$ is the two-year spot rate.
- $S_{1}$ is the one-year spot rate.
- $F_{1,1}$ is the one-year forward rate starting in one year.
Rearranging this equation to solve for the forward rate $F_{1,1}$:
$1 + F{1,1} = frac{(1 + S{2})^{2}}{(1 + S_{1})}$
$F{1,1} = frac{(1 + S{2})^{2}}{(1 + S_{1})} – 1$
This formula demonstrates how the forward rate is derived from current spot rates. The market’s expectations of future interest rates are implicitly embedded in the current yield curve, and thus in the calculated forward rates.
Forward Rate Agreements (FRAs)
Forward Rate Agreements (FRAs) are the most common financial instruments used to trade and hedge forward rates. An FRA is a customized over-the-counter (OTC) contract between two parties that locks in an interest rate on a notional amount of money for a specified period in the future.
How FRAs Work
An FRA contract specifies:
- Notional Principal Amount: The amount of money on which the interest will be calculated.
- Interest Rate: The fixed rate (the forward rate) agreed upon for the future period.
- Settlement Date: The date on which the contract begins and the interest rate differential is paid.
- Termination Date: The date on which the contract ends.
- Reference Rate: Typically a benchmark short-term interest rate, such as LIBOR (historically) or SOFR (currently), on which the floating rate will be based.
Let’s consider an example. Suppose a company wants to borrow $1 million for six months starting in three months. They are concerned that interest rates might rise by the time they need to borrow. They enter into a 3-vs-6 FRA (meaning the loan starts in 3 months and ends in 6 months, a 3-month period).
The FRA contract might specify:
- Notional Principal: $1,000,000
- Forward Rate (fixed rate): 4.00% per annum
- Settlement Date: 3 months from today
- Termination Date: 9 months from today (3 months + 6 months)
- Reference Rate: SOFR
If, on the settlement date (in 3 months), the 3-month SOFR rate is 4.50% per annum, the buyer of the FRA (who agreed to pay 4.00%) will receive a payment from the seller because the market rate is higher than the contracted rate. The seller of the FRA (who agreed to receive 4.00%) will pay the buyer.
The payment is calculated as the difference between the interest calculated at the floating rate and the interest calculated at the fixed rate, on the notional principal, for the specified period, discounted back to the settlement date.
Payment = (Notional Principal × (Floating Rate – Fixed Rate) × Days/360) / (1 + Floating Rate × Days/360)
Where:
- Days = Number of days in the settlement period (e.g., 180 days for a 6-month period in a 360-day year).
In our example:
- Floating Rate = 4.50%
- Fixed Rate = 4.00%
- Difference = 0.50%

The payment would compensate the borrower for having to pay a higher rate in the market than they locked in through the FRA. Conversely, if the market rate on the settlement date was 3.50%, the borrower would have to pay the seller the difference because the market rate is lower than the contracted fixed rate.
Applications of Forward Rates
Forward rates are not just theoretical constructs; they have significant practical applications in finance.
Hedging Interest Rate Risk
One of the primary uses of forward rates is to hedge against adverse movements in interest rates. Companies that anticipate needing to borrow money in the future, or those who will receive interest payments on investments, can use FRAs or other derivatives to lock in a rate and protect themselves from unfavorable market changes.
For example, a company planning to issue bonds in six months can use an FRA to fix the borrowing cost for that future period. This provides certainty for budgeting and financial planning, as the future interest expense is known.
Speculation
Traders can use forward rates to speculate on the future direction of interest rates. If a trader believes that interest rates will rise significantly, they might enter into an FRA as a seller, expecting to profit when the market rate surpasses their contracted rate. Conversely, if they anticipate rates falling, they might buy an FRA at a higher rate.
Yield Curve Analysis
The shape of the yield curve, which plots spot interest rates against their maturities, directly reflects the market’s expectations of future interest rates. By calculating forward rates from the yield curve, analysts can gain insights into these expectations.
- Upward-sloping yield curve: Indicates that the market expects future short-term interest rates to rise. Forward rates will be higher than current spot rates.
- Downward-sloping yield curve: Suggests expectations of falling future short-term interest rates. Forward rates will be lower than current spot rates.
- Flat yield curve: Implies expectations of stable future short-term interest rates. Forward rates will be close to current spot rates.
Understanding this relationship allows economists and financial strategists to gauge market sentiment and make informed predictions about economic conditions.
Pricing of Other Derivatives
Forward rates are a fundamental input in the pricing of many other interest rate derivatives, including interest rate swaps, options, and caps/floors. These instruments often involve a series of future interest rate payments, and the forward rates are used to determine the expected cash flows and thus the fair value of the derivative.
Factors Influencing Forward Rates
Several economic and market factors can influence the level and shape of forward rates:
Expectations Theory
As discussed, a significant driver of forward rates is the market’s expectation of future short-term interest rates. If the central bank is expected to raise its policy rate, this anticipation will push up forward rates for future periods.
Liquidity Premium
In some cases, longer-term instruments may carry a liquidity premium. Investors may demand a higher rate for holding longer-term securities because they are less liquid than shorter-term ones. This premium can affect the shape of the forward curve, making it steeper than pure expectations would suggest.
Inflation Expectations
Inflation is a key determinant of interest rates. If investors expect inflation to rise in the future, they will demand higher nominal interest rates to compensate for the erosion of purchasing power. These inflation expectations are incorporated into spot rates and, consequently, into forward rates.
Monetary Policy
The actions and anticipated actions of central banks are paramount. Decisions on interest rate settings, quantitative easing or tightening, and forward guidance all shape market expectations and directly impact the yield curve and forward rates.
Economic Growth Prospects
Stronger economic growth typically leads to higher demand for credit and potentially higher inflation, which central banks may counter with higher interest rates. Conversely, weak economic prospects can lead to expectations of lower interest rates.
Challenges and Considerations
While the concept of forward rates is straightforward, its practical application involves nuances and challenges.
Model Risk
The calculation of forward rates relies on specific models and assumptions, such as the no-arbitrage principle. If these models are flawed or if market conditions deviate significantly from the assumptions, the calculated forward rates might not accurately reflect actual market prices or future outcomes.
Basis Risk
When using FRAs or other derivatives to hedge, there’s a risk that the reference rate used in the contract may not perfectly match the actual rate on the underlying loan or investment. This difference is known as basis risk and can lead to imperfect hedging.
Counterparty Risk
For over-the-counter (OTC) derivatives like FRAs, there is the risk that the counterparty to the contract may default on its obligations. This risk is mitigated through collateralization and the use of reputable financial institutions, but it remains a consideration.
Implied vs. Actual Rates
It’s crucial to remember that forward rates are implied rates. They represent what the market believes rates will be, based on current information and expectations. The actual future spot rates may turn out to be different due to unforeseen economic events, policy changes, or shifts in market sentiment.

Conclusion
The forward rate is a fundamental concept in finance, representing the interest rate agreed upon today for a future borrowing or lending transaction. Derived from current spot rates and embodying market expectations of future interest rates, it plays a vital role in hedging interest rate risk, speculation, yield curve analysis, and the pricing of complex financial instruments. While challenges exist in accurately predicting future rates, understanding the mechanics and applications of forward rates provides invaluable insight into the functioning of financial markets and the dynamics of interest rate movements.