
Embarking on the journey to homeownership is a significant life milestone, often met with a mix of excitement and trepidation. For many, the most formidable hurdle is securing the necessary financing. Fortunately, a variety of loan programs are specifically designed to assist individuals purchasing their very first home. These “first-time home buyer loans” are not a single product but rather a collection of government-backed and conventional programs that offer more favorable terms, lower down payment requirements, and other benefits tailored to those new to the real estate market. Understanding these options is the crucial first step toward unlocking the door to your new home.

Understanding the Landscape of First-Time Home Buyer Programs
The term “first-time home buyer loan” is broad, encompassing several distinct programs, primarily backed by the federal government, as well as some conventional loan products that cater to this demographic. These programs aim to make homeownership more accessible, especially for individuals who may not have substantial savings for a large down payment or perfect credit scores.
Government-Backed Loans: FHA, VA, and USDA
These are some of the most popular and beneficial options for first-time buyers due to their flexible qualification criteria and attractive terms.
FHA Loans
Backed by the Federal Housing Administration (FHA), these loans are arguably the most commonly used by first-time buyers. They are attractive for several reasons:
- Low Down Payment: Borrowers can qualify with a down payment as low as 3.5% of the home’s purchase price. This significantly reduces the upfront cash needed compared to traditional conventional loans.
- Flexible Credit Requirements: FHA loans are more forgiving when it comes to credit scores. While specific lenders may have their own overlays, the FHA generally allows for lower credit scores than conventional mortgages.
- Less Stringent Debt-to-Income Ratios: FHA guidelines often permit higher debt-to-income (DTI) ratios, making it easier for buyers with existing debts to qualify.
- Mortgage Insurance Premium (MIP): A key feature of FHA loans is the mandatory mortgage insurance, which includes an upfront premium and annual premiums paid monthly. This insurance protects the lender in case of default, a trade-off for the lower down payment and more flexible terms. While it adds to the monthly cost, it enables access to homeownership for many.
VA Loans
Exclusively available to eligible service members, veterans, and surviving spouses, VA loans are one of the most powerful benefits of military service.
- No Down Payment Required: This is the standout feature of VA loans, allowing qualifying buyers to finance 100% of the home’s value.
- No Private Mortgage Insurance (PMI): Unlike FHA and most conventional loans with low down payments, VA loans do not require PMI, saving borrowers a significant amount monthly.
- Competitive Interest Rates: VA loans often come with lower interest rates than other loan types, thanks to the government backing.
- Funding Fee: Most VA borrowers are required to pay a one-time VA funding fee, which can be financed into the loan or paid upfront. Certain exemptions apply for veterans with service-connected disabilities.
- Flexible Credit and DTI: Similar to FHA, VA loans offer more lenient credit and DTI requirements, making them highly accessible.
USDA Loans
Guaranteed by the U.S. Department of Agriculture (USDA) Rural Development program, these loans are designed to promote homeownership in rural and eligible suburban areas.
- No Down Payment Required: Like VA loans, USDA loans often require no down payment, making them highly attractive.
- Geographic Restrictions: The primary limitation is that the property must be located in an eligible rural or suburban area as defined by the USDA.
- Income Limitations: Borrowers must meet specific income requirements, which vary by location and household size, to ensure the program assists low to moderate-income families.
- Mortgage Insurance: USDA loans require both an upfront guarantee fee and an annual fee, similar to FHA’s mortgage insurance.
Conventional Loans for First-Time Buyers
While government-backed loans are popular, conventional loans also offer options for first-time buyers, particularly those with strong credit and a modest down payment.

Low Down Payment Conventional Options
Many lenders now offer conventional loan programs with down payments as low as 3%. These programs are often supported by Fannie Mae and Freddie Mac (government-sponsored enterprises).
- Fannie Mae’s HomeReady and Freddie Mac’s Home Possible: These programs are specifically designed for low to moderate-income borrowers, offering flexible underwriting and reduced PMI requirements compared to standard conventional loans.
- Private Mortgage Insurance (PMI): For conventional loans with less than a 20% down payment, borrowers will typically be required to pay PMI. However, unlike FHA MIP, PMI on conventional loans can often be canceled once sufficient equity is built in the home.
- Stricter Credit Requirements: Generally, conventional loans require higher credit scores than FHA loans to qualify for the best rates and terms.
Eligibility and Application Process
Regardless of the specific program, a first-time home buyer loan typically refers to someone who has not owned a home in the last three years. However, specific programs might have slightly different definitions or additional criteria.
Key Eligibility Factors
Lenders will assess several aspects of your financial profile to determine eligibility:
- Credit Score: A higher credit score generally leads to better interest rates and more loan options. FHA and VA loans are more forgiving, but good credit is always beneficial.
- Income and Employment Stability: Lenders want to see a consistent income stream and stable employment history, typically two years in the same line of work, to ensure you can make monthly payments.
- Debt-to-Income Ratio (DTI): This measures how much of your gross monthly income goes toward debt payments. Lower DTI ratios are preferred, though government-backed loans often allow higher limits.
- Assets and Down Payment: The amount of money you have saved for a down payment and closing costs is crucial. While some loans require no down payment, you’ll still need funds for closing costs, which can range from 2-5% of the loan amount.
- Property Type: The home must meet specific appraisal and property standards for the chosen loan program.
The Application Journey
The path to securing a first-time home buyer loan generally follows these steps:
- Financial Review and Budgeting: Understand your current financial situation, including income, expenses, debts, and savings. Determine a comfortable monthly mortgage payment.
- Get Pre-Approved: This crucial step involves a lender reviewing your financial information and credit history to estimate how much you can borrow. A pre-approval letter strengthens your offer when you find a home.
- Find a Real Estate Agent: A buyer’s agent can help you navigate the housing market, find suitable properties, and negotiate offers.
- Find a Home and Make an Offer: Once you find a home you love, your agent will help you submit an offer.
- Loan Application and Underwriting: After your offer is accepted, you’ll formally apply for the loan. The lender will collect all necessary documents (pay stubs, bank statements, tax returns, etc.) and begin the underwriting process, which involves a thorough review of your finances and the property’s appraisal and title.
- Closing: This is the final step where all documents are signed, funds are transferred, and you officially become the homeowner. You’ll typically pay closing costs at this stage.
Benefits and Considerations for First-Time Buyers
First-time home buyer loans are designed to alleviate some of the common barriers to homeownership, but it’s important to weigh their benefits against their unique considerations.
Advantages of Specific Programs
- Accessibility: Lower down payments and more flexible credit criteria make homeownership attainable for more people.
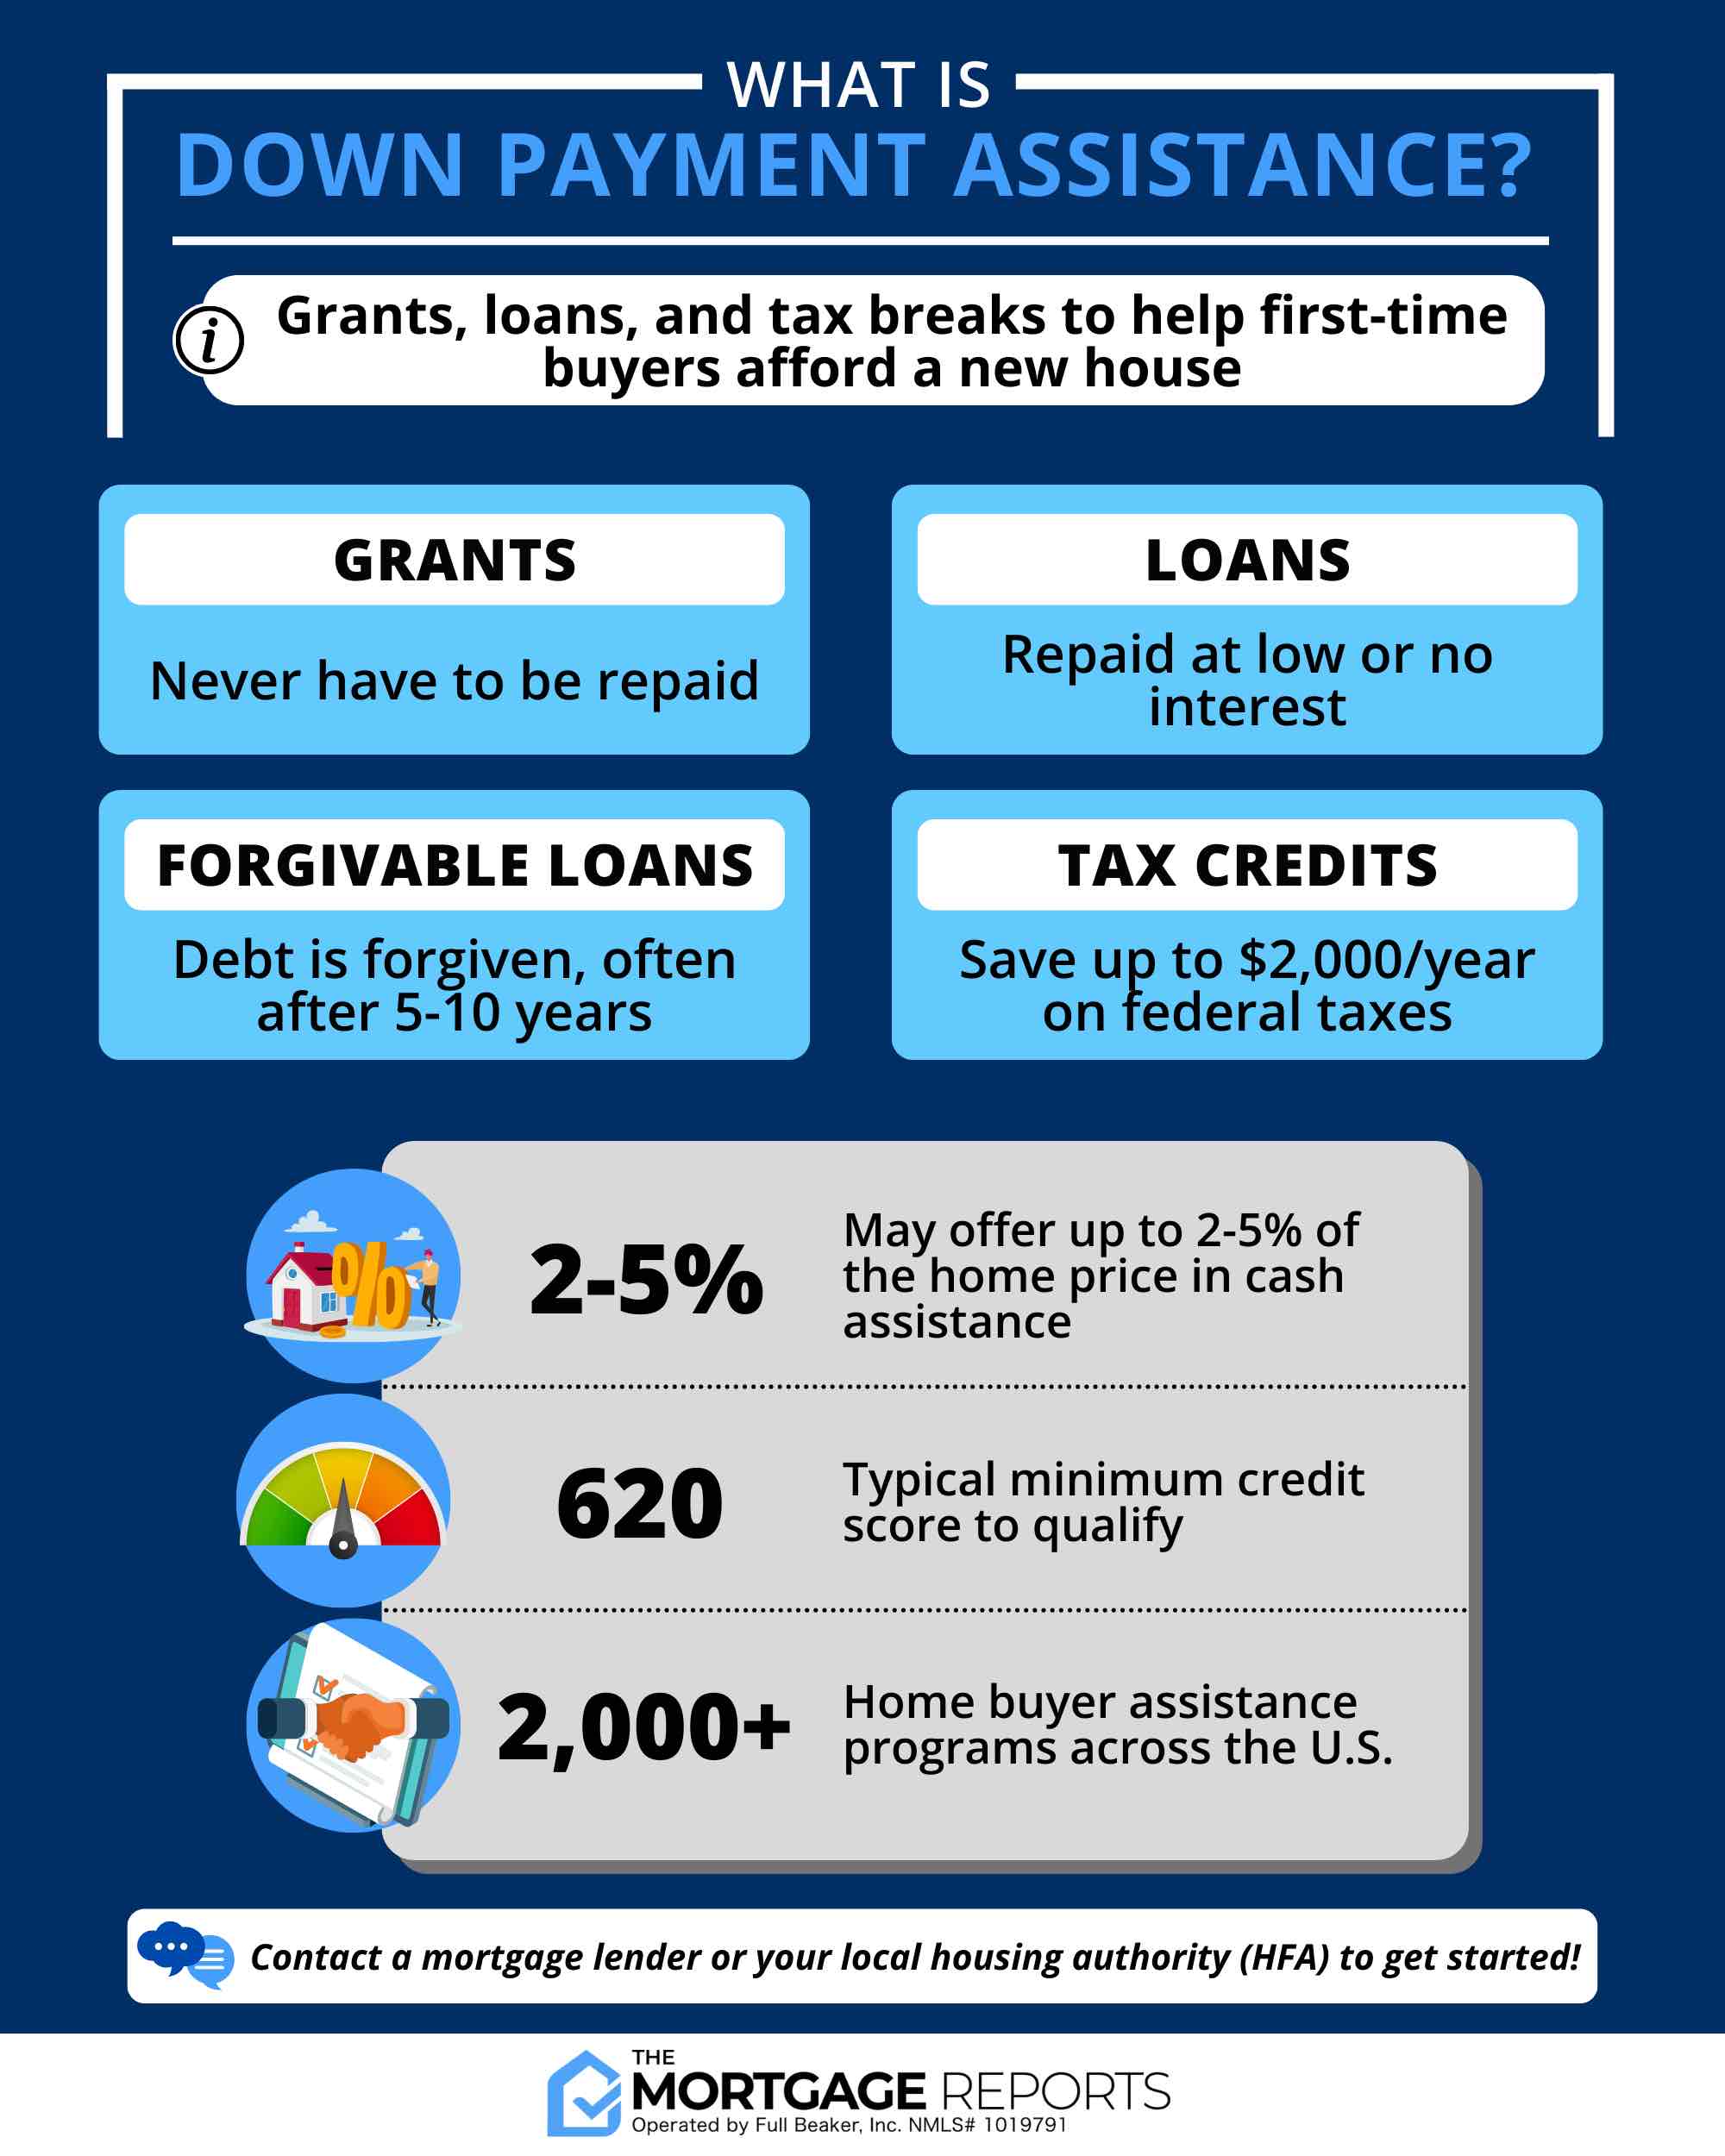
- Financial Assistance: Many state and local programs offer down payment assistance (DPA) or closing cost assistance, often in conjunction with FHA, VA, or USDA loans, further reducing upfront costs.
- Education and Support: Some programs require or offer homebuyer education courses, which can be invaluable for understanding the responsibilities of homeownership.
- Competitive Rates: Government backing often leads to competitive interest rates, making monthly payments more affordable.
Important Considerations
- Mortgage Insurance: While it enables lower down payments, the required mortgage insurance (MIP for FHA, Guarantee Fee for USDA, PMI for conventional) adds to your monthly housing expense. Understand its costs and how long it will be required.
- Property Requirements: Government-backed loans often have specific property standards that homes must meet to qualify, which can sometimes limit options in the market.
- Limited Choice in Some Areas: USDA loans are restricted to rural or eligible suburban areas, meaning they are not an option for buyers in major metropolitan centers.
- Future Refinancing: As your equity grows, you might consider refinancing out of an FHA loan (which typically has lifelong MIP unless you put 10% or more down initially, then it cancels after 11 years) into a conventional loan to eliminate mortgage insurance.
In conclusion, “what is a first-time home buyer loan” is not a singular answer but rather an exploration of diverse financial products designed to simplify the path to homeownership. By understanding the nuances of FHA, VA, USDA, and conventional low down payment options, prospective buyers can identify the program best suited to their financial situation, propelling them from aspiring homeowners to proud property owners. Engaging with knowledgeable lenders and real estate professionals is key to navigating these choices effectively and confidently stepping into your first home.