
Discount points, often simply referred to as “points,” are a financial instrument used in mortgage lending to reduce the interest rate on a loan. In essence, a discount point is a fee paid directly to the lender at closing in exchange for a reduction in the interest rate of the mortgage. This fee is typically equal to 1% of the loan amount. Understanding discount points is crucial for any borrower seeking to optimize their mortgage costs over the life of the loan. They represent a strategic decision that can have significant financial implications, impacting both the upfront costs of obtaining a mortgage and the long-term monthly payments.
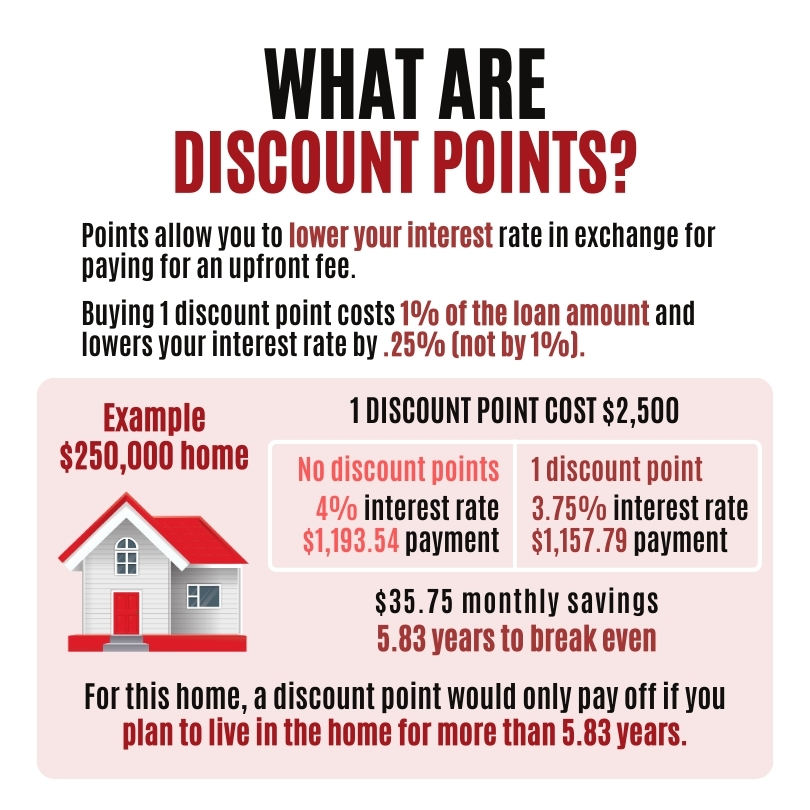
The Mechanics of Discount Points
When a borrower decides to purchase discount points, they are essentially prepaying a portion of the interest that would otherwise be paid over the loan’s term. This upfront payment is then factored into the lender’s pricing model, allowing them to offer a lower interest rate on the mortgage. The relationship between paying for points and receiving a lower interest rate is not always linear and can vary between lenders. However, the general principle holds true: more points paid often equate to a larger reduction in the interest rate.
How Many Points Can You Buy?
Borrowers are typically not limited to purchasing just one discount point. Lenders may allow the purchase of fractional points, such as half a point (.5%), or multiple points, depending on the loan product and market conditions. The decision to buy points is a strategic one, requiring careful consideration of the loan terms, the borrower’s financial situation, and their future plans for the property.
The Cost of a Point
As mentioned, a discount point usually costs 1% of the total loan amount. For instance, on a $300,000 mortgage, one discount point would cost $3,000. This fee is paid at closing, alongside other associated closing costs such as appraisal fees, title insurance, and origination fees. The total amount paid for discount points will be clearly itemized in the loan estimate and the closing disclosure provided by the lender.
The Interest Rate Reduction
The amount by which the interest rate is reduced for each point purchased can vary. A common benchmark is that one discount point can lower the interest rate by approximately 0.25% to 0.50%. However, this is not a fixed rule. Lenders set their own pricing structures, which can be influenced by market dynamics, the borrower’s creditworthiness, and the overall loan program. It is essential to get a precise quote from the lender on how many basis points (hundredths of a percentage point) the interest rate will decrease for each point purchased.
Break-Even Point Calculation
The primary consideration when deciding whether to buy discount points is the break-even point. This is the point in time, measured in months, at which the savings from the lower monthly payments offset the upfront cost of purchasing the points. To calculate the break-even point, one needs to know:
- The upfront cost of the discount points.
- The monthly savings in principal and interest payments resulting from the lower interest rate.
The formula is straightforward:
Break-Even Point (in months) = Total Cost of Points / Monthly Savings
For example, if a borrower pays $6,000 for two discount points on a $300,000 loan, and this results in a monthly saving of $150 in principal and interest payments, the break-even point would be:
$6,000 / $150 = 40 months
This means that after 40 months of making mortgage payments, the borrower will have recouped the initial investment in discount points through their reduced monthly obligations. Beyond this point, the borrower will continue to benefit from the lower interest rate for the remainder of the loan term.
When is Buying Discount Points a Good Idea?
The decision to purchase discount points is not a one-size-fits-all solution. It is a strategic financial move that is most beneficial under certain circumstances. The key factor is the borrower’s expected duration of homeownership.
Long-Term Homeownership
If a borrower anticipates staying in their home for a significant period, buying discount points can be a wise investment. The longer the loan is in effect, the more time there is to realize the benefits of the reduced interest rate, making the upfront cost of the points more than worth it. In the break-even point calculation, if the borrower expects to remain in the home for longer than the calculated break-even period, the purchase of points is likely to be financially advantageous. For instance, if the break-even point is 40 months and the borrower plans to live in the home for 10 years (120 months), the savings over the remaining 80 months will be substantial.
Interest Rate Environment
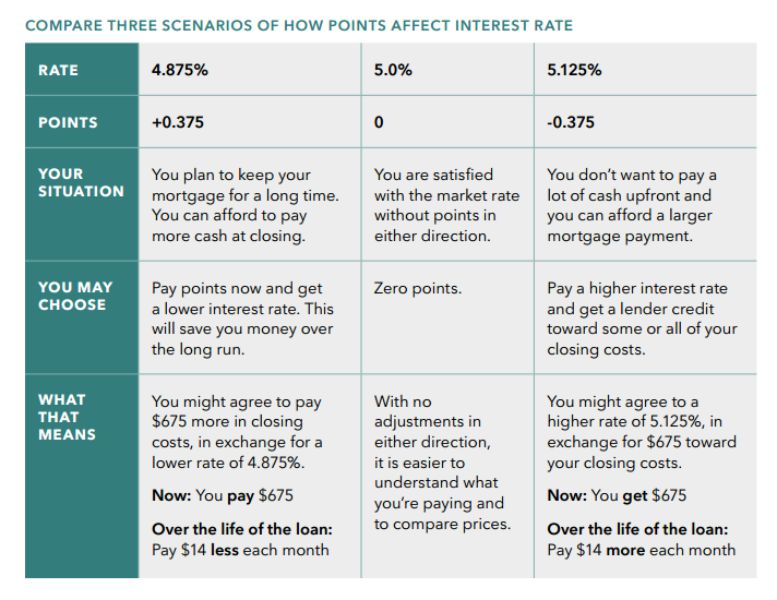
The prevailing interest rate environment also plays a role. When interest rates are high, the impact of even a small reduction can lead to significant savings over the life of the loan. In such scenarios, the upfront cost of points may be more justified as the difference between the current market rate and a slightly lower rate can be substantial. Conversely, when interest rates are already very low, the potential for further reduction might be limited, making the purchase of points less impactful.
Refinancing Decisions
Discount points are often considered when refinancing an existing mortgage. If a borrower refinances to a lower interest rate, they may choose to pay points to further decrease that rate. This is particularly relevant if the borrower plans to stay in the home for the long haul after the refinance. The decision to buy points during a refinance should be based on a similar break-even analysis, considering the cost of the points versus the monthly savings from the new, lower interest rate.
Strong Financial Position
Borrowers who are in a strong financial position and have sufficient cash reserves may consider purchasing discount points. The ability to pay the upfront cost without straining their budget is a prerequisite. This upfront payment is essentially an investment, and it requires available funds. For borrowers with limited liquidity, spending cash on discount points might not be advisable, especially if those funds could be better used for emergency savings or other financial goals.
When to Avoid Discount Points
While discount points can be beneficial, there are situations where they are not the best financial strategy.
Short-Term Homeownership
If a borrower plans to sell their home or move within a few years, buying discount points is generally not advisable. The break-even point calculation is critical here. If the expected duration of homeownership is shorter than the break-even period, the borrower will likely not recoup the cost of the points. In such cases, the upfront cost will simply add to the overall expenses of buying and selling the home without yielding any long-term savings.
Limited Cash Reserves
For borrowers with tight budgets or limited cash reserves, purchasing discount points can be a financial burden. The upfront fee, while potentially leading to long-term savings, can deplete essential funds needed for emergencies, unexpected home repairs, or other immediate financial obligations. It is generally recommended to prioritize having a robust emergency fund before committing to paying for discount points.
Volatile Interest Rate Market
In a highly volatile interest rate market, it might be prudent to wait. If interest rates are expected to decline significantly in the near future, a borrower might choose not to pay points now, hoping to refinance at an even lower rate later without the added cost of points. However, this is a speculative strategy, as interest rate movements cannot be precisely predicted.
Borrowers with High Credit Risk
While not directly a reason to avoid points, lenders may offer less favorable terms on points to borrowers with lower credit scores. The reduction in interest rate per point might be smaller, or the overall cost of points may be higher. In such cases, the value proposition of buying points diminishes.
Discount Points vs. Origination Fees
It’s important to distinguish discount points from origination fees, although they are often discussed together as lender fees.
Origination Fees
Origination fees are charges levied by the lender for processing and underwriting the mortgage loan. These fees cover the lender’s administrative costs and are typically a percentage of the loan amount, often around 0.5% to 1%. Unlike discount points, origination fees do not directly result in a reduction of the interest rate. They are simply a cost of doing business with the lender. Some lenders may waive origination fees in exchange for a higher interest rate, which is essentially the opposite of buying discount points.
The Interplay
While distinct, origination fees and discount points are often part of the same loan pricing structure. A lender might offer a loan with a specific interest rate and a certain origination fee. Alternatively, they might offer a slightly lower interest rate with a higher origination fee, or a lower origination fee with a higher interest rate. Discount points allow borrowers to further manipulate this pricing by paying an upfront fee to reduce the interest rate. When comparing loan offers, it’s essential to look at the Annual Percentage Rate (APR), which is a broader measure of the cost of borrowing, as it includes both the interest rate and most of the fees associated with the loan, providing a more comprehensive picture of the loan’s true cost over its life.

Conclusion
Discount points are a powerful tool for borrowers to manage the cost of their mortgage. By strategically paying an upfront fee, homeowners can secure a lower interest rate, leading to reduced monthly payments and substantial savings over the long term. However, the decision to buy points is not without its considerations. A thorough understanding of the break-even point, the borrower’s expected duration of homeownership, and their overall financial situation is paramount. By carefully analyzing these factors and comparing loan offers, borrowers can make an informed decision that aligns with their financial goals and ensures they are making the most of their mortgage investment.