
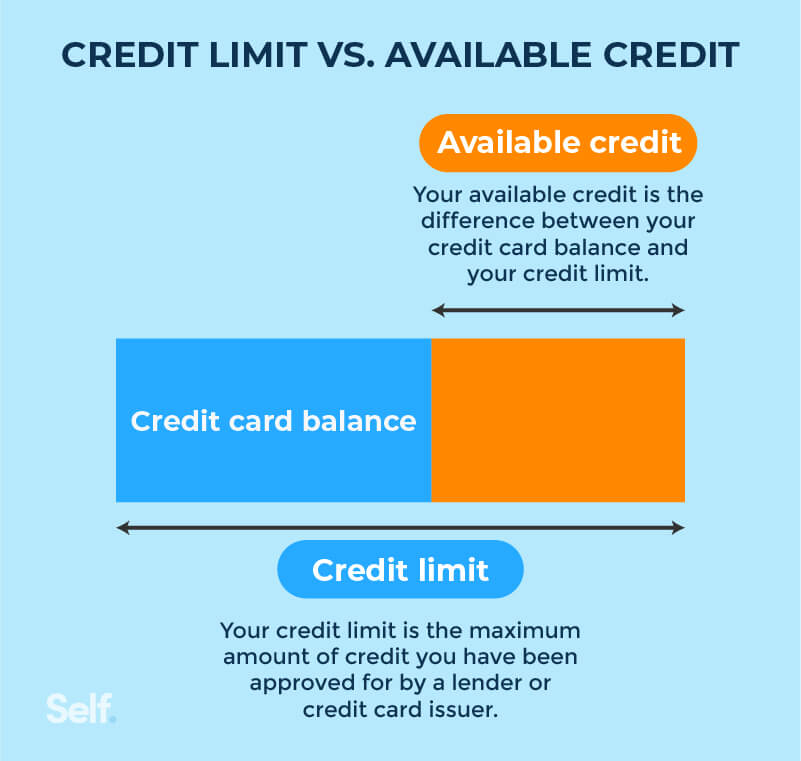
Understanding the intricacies of credit cards is fundamental to responsible financial management. Among the key concepts to grasp is the credit limit, a term that directly impacts how you can utilize your plastic and influences your overall financial health. In essence, your credit limit is the maximum amount of money a credit card issuer will allow you to borrow on a given card. It acts as a ceiling for your spending, a boundary beyond which you cannot accrue further debt on that particular account until you make payments to reduce your outstanding balance.
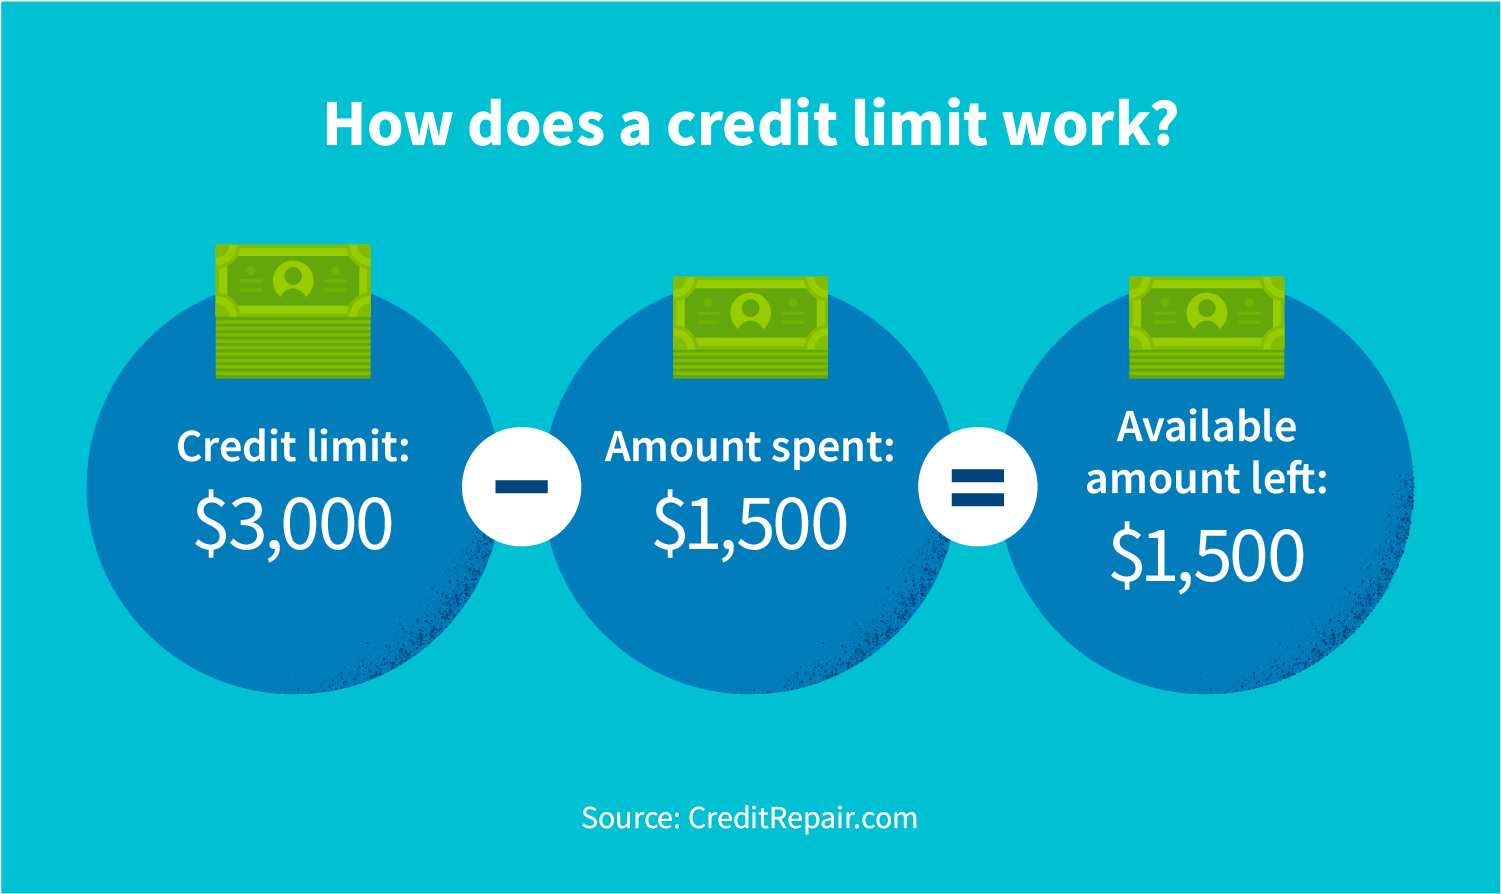
This limit is not arbitrary; it is a carefully calculated figure based on a variety of factors that lenders assess to gauge your creditworthiness and your ability to repay borrowed funds. It’s a dynamic number, subject to change over time, and understanding its significance is paramount for effective budgeting, debt management, and strategic use of credit.
The Mechanics of Setting a Credit Limit
The determination of your credit limit is a sophisticated process undertaken by credit card issuers. It’s not a one-size-fits-all approach. Instead, it’s a personalized assessment that considers your financial profile and your history with credit. The primary goal for the issuer is to extend credit in a way that minimizes their risk while maximizing the potential for profitable engagement with you as a customer.
Credit Score and History
At the forefront of credit limit determination is your credit score. This three-digit number, typically ranging from 300 to 850, is a numerical representation of your credit risk. Scores are compiled by credit bureaus (such as Equifax, Experian, and TransUnion) based on your past borrowing and repayment behavior. A higher credit score generally indicates a lower risk to lenders, signaling that you have a proven track record of managing debt responsibly. Consequently, individuals with excellent credit scores often qualify for higher credit limits.
Your credit history, which is the detailed record of your borrowing and repayment activities, is intrinsically linked to your credit score. This history includes:
- Payment History: This is the most significant factor. Consistently paying your bills on time demonstrates reliability. Late payments, defaults, or bankruptcies can severely damage your credit history and lead to lower credit limits or even denial of credit.
- Credit Utilization Ratio: This refers to the amount of credit you are currently using compared to your total available credit. A high utilization ratio (using a large portion of your available credit) can negatively impact your score and signal to lenders that you might be overextended, potentially resulting in a lower credit limit.
- Length of Credit History: A longer history of responsible credit use provides lenders with more data to assess your behavior. Older, well-managed accounts can contribute positively to your creditworthiness.
- Credit Mix: Having a diverse mix of credit accounts (e.g., credit cards, installment loans like mortgages or car loans) can show you can manage different types of debt, although this is a less impactful factor than payment history or utilization.
- New Credit: Opening multiple new credit accounts in a short period can be seen as a red flag, suggesting potential financial distress or a higher risk of default.
Income and Employment Stability
Beyond your credit history, lenders also scrutinize your income and employment situation. They need to ascertain your capacity to repay the debt you might incur. Your stated income, often verified through pay stubs or tax returns, provides a baseline for how much you can realistically afford to spend and repay. Lenders assess not only the amount of your income but also its stability. A consistent and reliable income stream, typically from a stable employment source, suggests a lower risk than a fluctuating or uncertain income. This is why individuals with higher, more stable incomes often receive more generous credit limits.
Existing Debt Obligations
The amount of debt you already carry plays a crucial role in credit limit decisions. Lenders consider your “debt-to-income ratio” (DTI), which compares your total monthly debt payments to your gross monthly income. A high DTI indicates that a significant portion of your income is already committed to servicing existing debts, leaving less capacity for new borrowing. If your DTI is already high, card issuers are likely to extend a lower credit limit to ensure you don’t become over-leveraged. They want to see that you have enough disposable income to manage a new credit obligation comfortably.
Relationship with the Issuer
Sometimes, your existing relationship with a credit card issuer can influence your credit limit. If you have other accounts with the same bank or financial institution, and you have managed them responsibly (e.g., checking accounts with good balances, other credit cards paid on time), this positive history can work in your favor. A long-standing, positive customer relationship can sometimes lead to more favorable credit limit offers, as the issuer has a proven history of your financial behavior within their system.
The Impact of Your Credit Limit
Your credit limit is more than just a spending cap; it has far-reaching implications for your financial well-being and your ability to access credit in the future. Understanding these impacts is crucial for making informed decisions about how you use your credit cards.
Credit Utilization Ratio and Credit Score
One of the most significant ways your credit limit affects your financial health is through its impact on your credit utilization ratio. As mentioned earlier, this ratio is calculated by dividing the total amount of credit you are using by your total available credit. For example, if you have a credit card with a $10,000 credit limit and you owe $3,000 on it, your utilization ratio is 30% ($3,000 / $10,000).
Credit scoring models, particularly FICO and VantageScore, place a heavy emphasis on this ratio. Experts generally recommend keeping your credit utilization below 30%, and ideally below 10%, to maintain a healthy credit score. Using a large percentage of your available credit, even if you pay it off in full each month, can signal to credit bureaus that you are heavily reliant on credit, potentially impacting your score negatively. Therefore, a higher credit limit can provide you with more breathing room, allowing you to make purchases without unduly increasing your utilization ratio.
Purchasing Power and Financial Flexibility
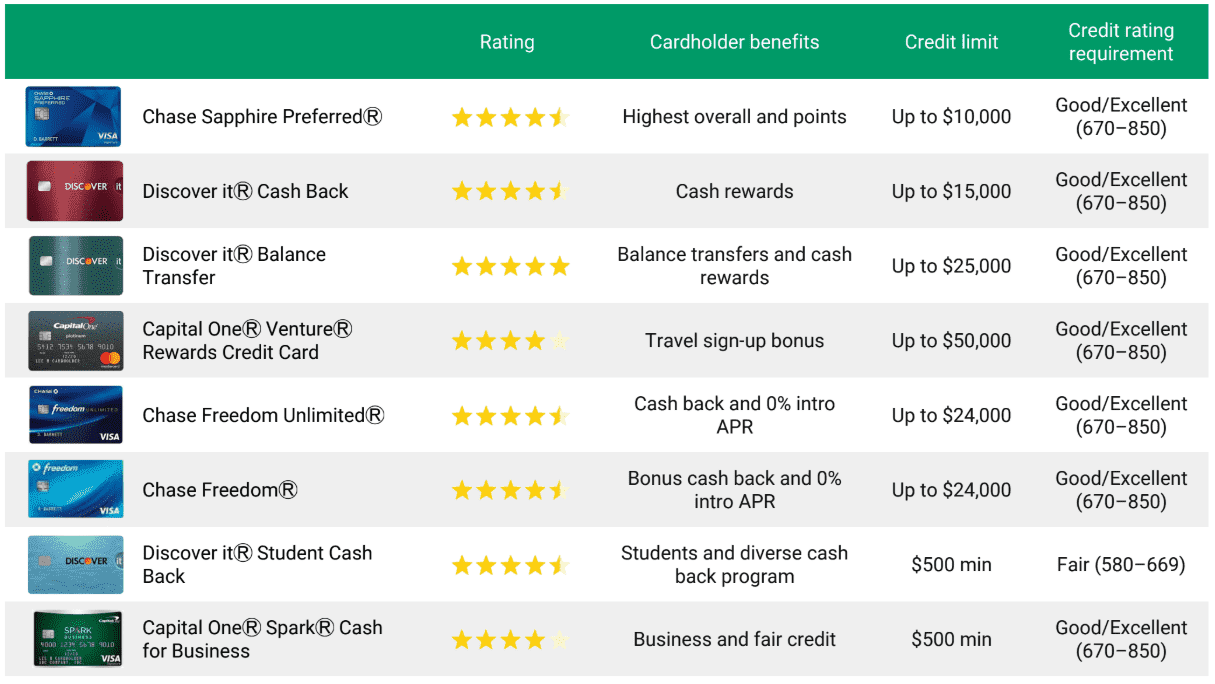
Naturally, a higher credit limit translates directly to greater purchasing power. It means you can make larger purchases, whether for essential items, significant investments, or emergency expenses, without immediately maxing out your card. This flexibility can be particularly valuable for unexpected events, such as medical emergencies, urgent home repairs, or even seizing time-sensitive opportunities. It can provide a financial safety net, offering peace of mind knowing that you have access to funds when needed.
However, this increased purchasing power must be coupled with strong financial discipline. A high credit limit is a tool, and like any tool, it can be used constructively or destructively.
Potential for Debt Accumulation
The flip side of increased purchasing power is the increased potential for accumulating debt. A generous credit limit can make it easier to overspend and accrue balances that become difficult to manage. If purchases consistently exceed your ability to repay them, you can quickly find yourself in a cycle of debt, incurring interest charges that escalate your total debt burden. This is why responsible use of credit, regardless of the limit, is paramount. It’s essential to treat your credit limit not as free money, but as a line of credit that must be repaid.
Impact on Future Credit Applications
The credit limits on your existing cards also influence your ability to obtain new credit. Lenders look at your total available credit across all your accounts when evaluating new applications. If your existing credit cards are consistently maxed out, or if your available credit is low due to high utilization on multiple cards, it can make it harder to get approved for new loans or credit cards, and if approved, the limits offered may be lower. Maintaining healthy credit limits and low utilization demonstrates responsible credit management and can enhance your attractiveness to future lenders.
Strategies for Managing Your Credit Limit
Effectively managing your credit limit is a cornerstone of sound financial planning. It involves a proactive approach to spending, borrowing, and repayment, ensuring that your credit cards serve as valuable financial tools rather than sources of stress.
Prioritizing Responsible Spending
The most fundamental strategy is to spend within your means. Before making a purchase, especially a significant one, consider whether it aligns with your budget and if you can comfortably repay the amount. Treat your credit limit as a ceiling, not a target. Avoid the temptation to spend just because the credit is available. Develop a habit of checking your available credit and current balance regularly to stay aware of your spending patterns.
Understanding and Managing Credit Utilization
Actively monitor your credit utilization ratio. Aim to keep it as low as possible, ideally below 30% and even better, below 10%. If you find yourself approaching higher utilization, consider making a payment before your statement closing date to reduce the reported balance. Alternatively, if you have multiple cards, strategically pay down balances on cards with higher utilization first. Paying your balance in full each month is the ideal scenario, but if that’s not feasible, managing your utilization is the next best thing for your credit score.
Making Timely Payments
Consistent, on-time payments are non-negotiable for good credit management. Set up payment reminders or automatic payments to ensure you never miss a due date. Late payments not only incur fees but also significantly damage your credit score and can lead to a reduction in your credit limit. Prioritize paying at least the minimum due, but aim to pay more, ideally the full statement balance, to avoid interest charges.
Requesting Credit Limit Increases
If you have a history of responsible credit card use and your income has increased, you may consider requesting a credit limit increase from your issuer. A higher credit limit can lower your credit utilization ratio, assuming your spending remains consistent. It can also provide greater financial flexibility for emergencies or planned large purchases. However, only request an increase if you are confident in your ability to manage the additional credit responsibly. Some issuers may perform a “hard pull” on your credit report for limit increase requests, which can temporarily lower your score, so be mindful of this.
Avoiding Over-Limit Fees
Be aware of whether your card issuer charges over-limit fees if you exceed your credit limit. While many issuers no longer automatically decline transactions that exceed the limit, they may choose to do so or charge a fee for transactions that push you over. It is best practice to avoid reaching or exceeding your credit limit altogether to prevent unexpected charges and negative impacts on your credit.
In conclusion, a credit limit is a foundational element of credit card management. It is a figure shaped by your financial history and income, and it profoundly impacts your purchasing power, your credit score, and your overall financial flexibility. By understanding how credit limits are set, their implications, and by adopting disciplined management strategies, individuals can harness the power of credit effectively, paving the way for a more secure and prosperous financial future.