
In the rapidly evolving world of aerial photography and videography, drones have become indispensable tools for creators. From breathtaking cinematic landscapes to intricate architectural surveys, these unmanned aerial vehicles (UAVs) offer perspectives previously unimaginable. However, with this advanced technology comes a significant financial investment. Whether you’re a seasoned professional or an enthusiastic hobbyist, the prospect of damage or loss to your valuable drone equipment can be a source of considerable anxiety. This is where the concept of “gap insurance” for your drone becomes critically important, especially when considering the insurance landscape surrounding your aerial assets.
Understanding Your Drone’s Insurance Needs
When investing in a drone, particularly a high-end model equipped with advanced cameras, gimbals, and sophisticated flight controllers, its value can quickly escalate into thousands of dollars. Standard homeowners or renters insurance policies often provide limited coverage for specialized equipment like drones, and even then, the payout may not reflect the depreciated value of your asset. This is a crucial point: insurance settlements are typically based on the market value of an item at the time of loss, not its replacement cost.
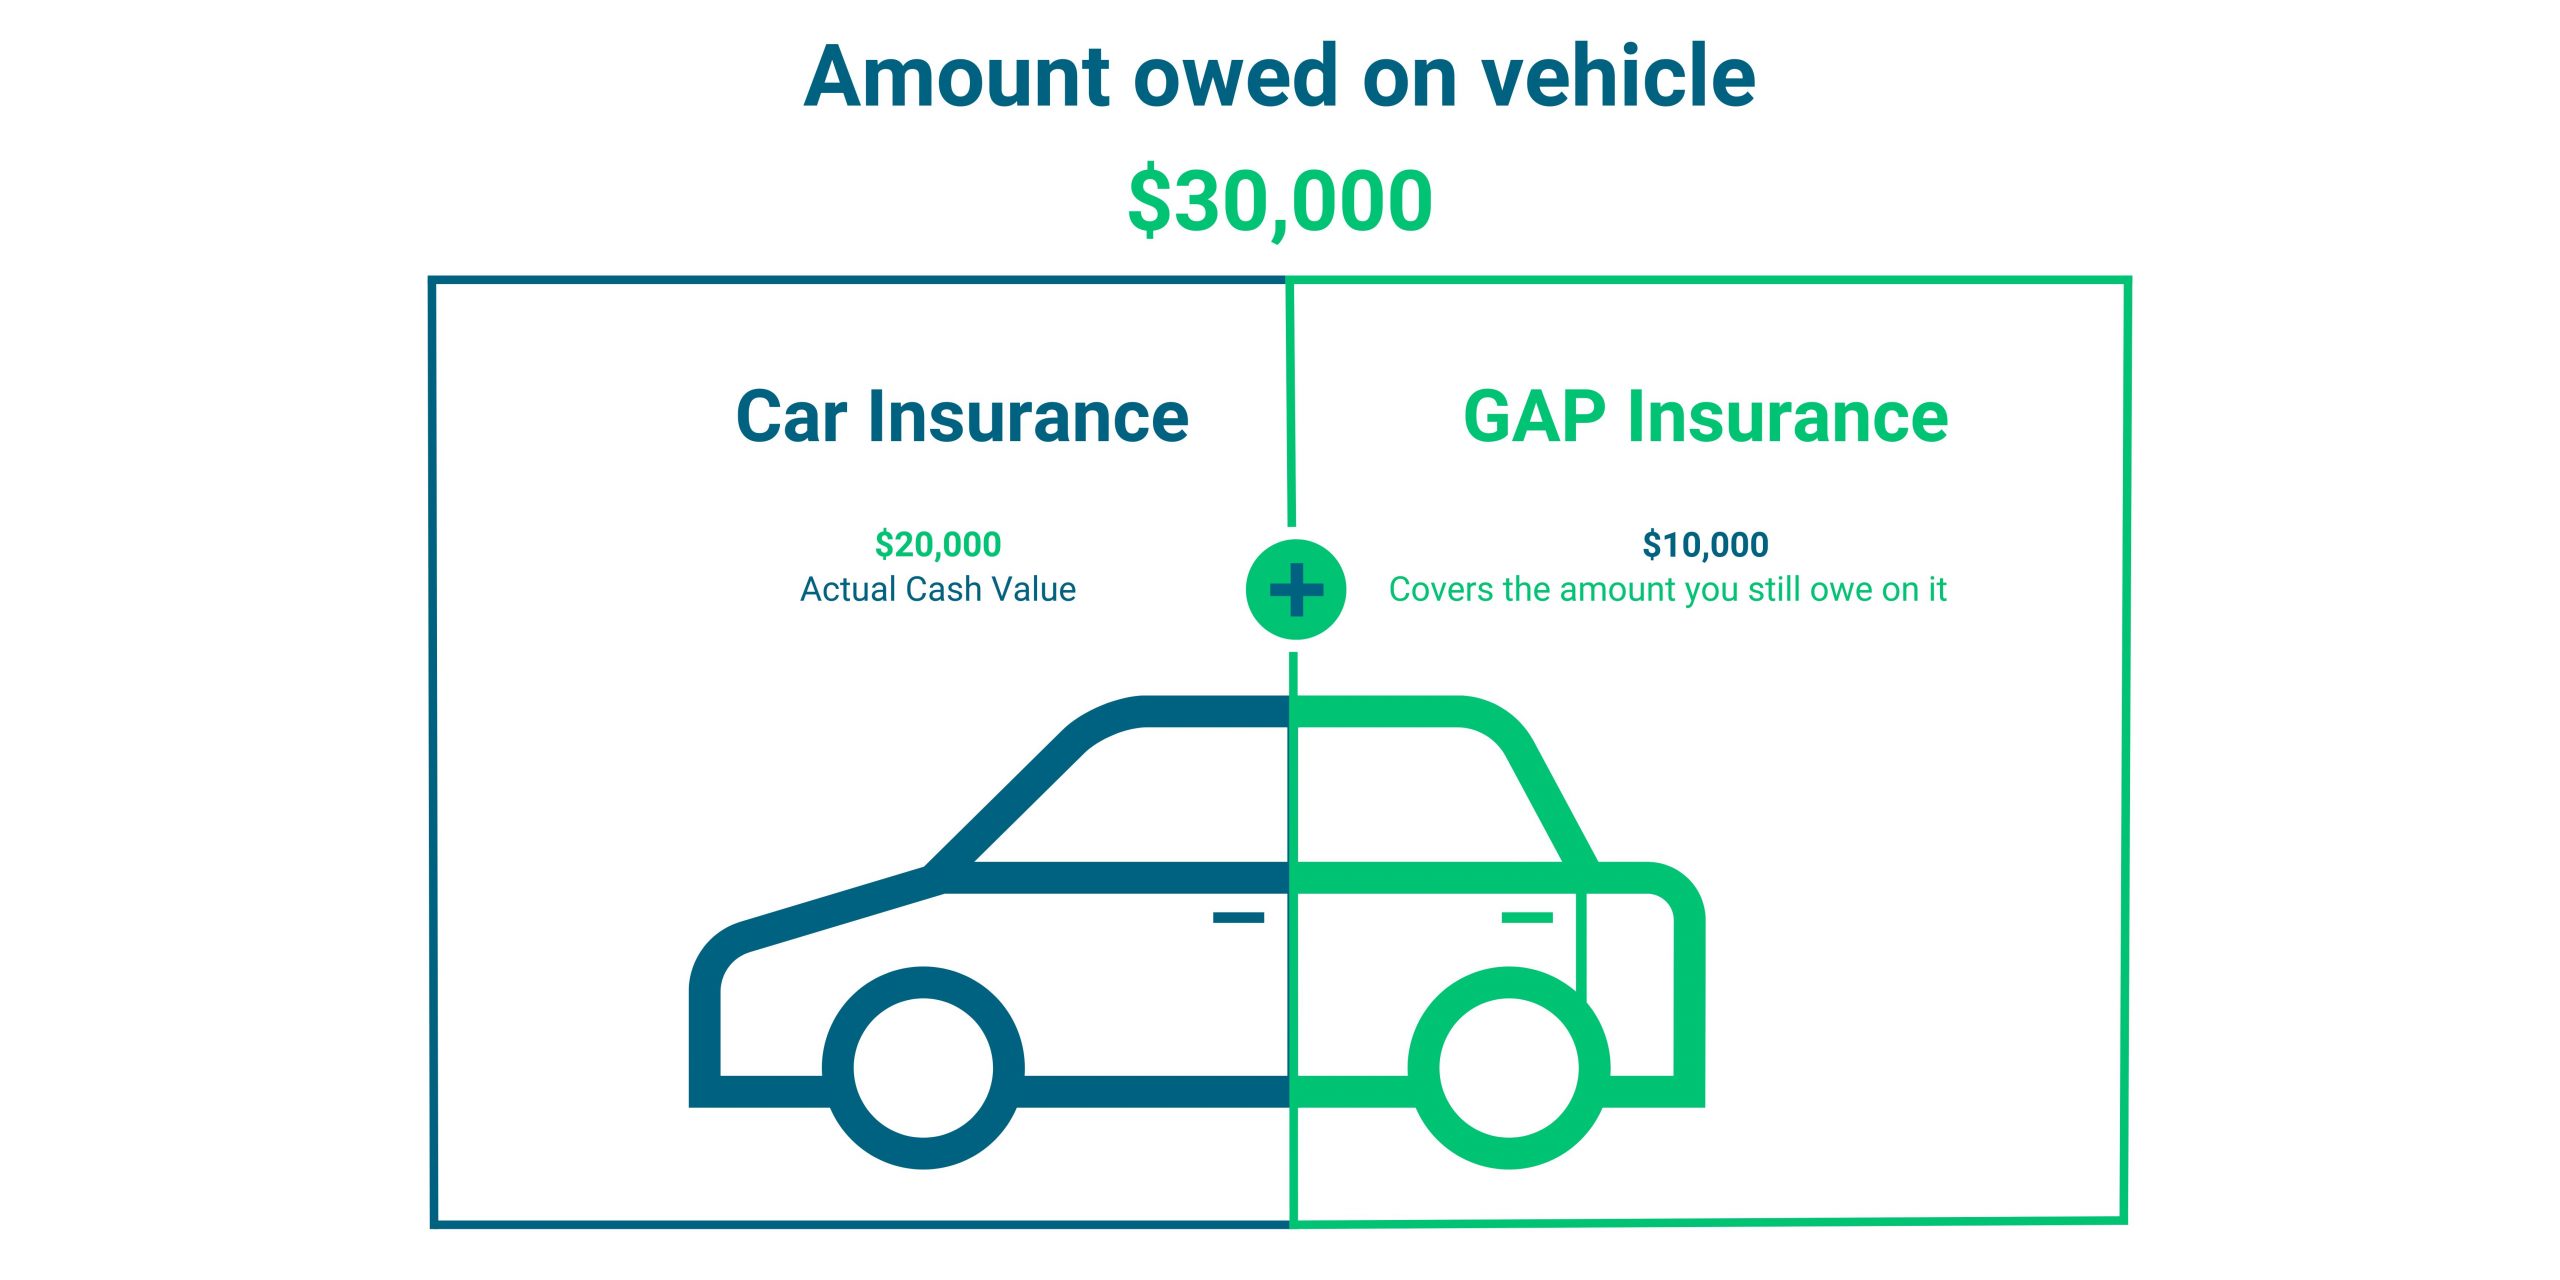
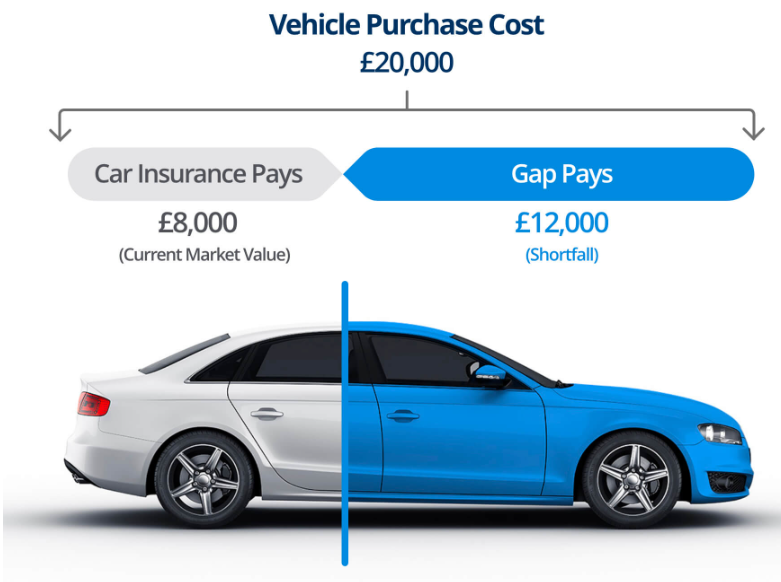
Consider a scenario where you purchased a professional-grade drone for $5,000 six months ago. Due to depreciation, its current market value might be closer to $4,000. If the drone is damaged beyond repair, your insurance might only cover that $4,000, leaving you with a $1,000 shortfall to purchase a new, comparable model. This is where the “gap” in coverage emerges, and where gap insurance aims to provide a solution.
Depreciation: The Silent Killer of Asset Value
The most significant factor contributing to this coverage gap is depreciation. Unlike a new car that loses a substantial portion of its value the moment it’s driven off the lot, drones, while also subject to depreciation, often maintain a higher resale value for a longer period. However, their value still diminishes over time due to technological advancements and general wear and tear. When making an insurance claim, insurers often refer to depreciation schedules to determine the payout. For a drone that might be considered “used” after even a few flights, this depreciation can significantly impact the amount you receive.
The Limitations of Standard Policies
Many standard insurance policies are not designed to cover the unique risks associated with drone operation. They might exclude coverage for accidents occurring while flying, damage caused by operator error, or loss due to theft while in transit for a shoot. Furthermore, if your drone is used for commercial purposes, such as aerial photography for real estate or events, it almost certainly requires specialized commercial drone insurance. Even with such policies, the depreciation clause can still leave a significant gap between what you receive and what it costs to replace your equipment with a new, up-to-date model.
What is Gap Insurance for Drones?
Gap insurance, often associated with auto loans, is a type of coverage that pays the difference between the actual cash value of a damaged or stolen item (as determined by your primary insurer) and the amount you still owe on a loan or, in the context of drones, the cost to replace it with a new, equivalent model. For drone owners, gap insurance acts as a supplementary policy that bridges the financial void left by depreciation and the limitations of standard insurance payouts.
How it Works in Practice
Imagine you purchased a $3,000 professional drone with a $1,000 down payment, leaving a $2,000 balance on your financing or a strong desire to replace it with a brand-new unit. Your drone is subsequently involved in an accident and is deemed a total loss by your primary insurer. This insurer assesses the drone’s actual cash value at $2,200 after accounting for depreciation.
Without gap insurance, you would receive $2,200. If you had a remaining loan balance of $2,000, you could theoretically pay it off. However, to acquire a new, equivalent drone, you would need to spend $3,000 (the cost of a new one), leaving you with a $800 out-of-pocket expense ($3,000 – $2,200).
With gap insurance for your drone, this $800 shortfall would be covered. The gap insurance policy would pay out the difference between the actual cash value settlement ($2,200) and the replacement cost of a new drone ($3,000), effectively covering the $800 gap and allowing you to replace your drone without incurring additional personal expense. It’s important to note that gap insurance typically covers the replacement cost of a new drone, not just the remaining loan balance.
Key Features and Benefits
The primary benefit of gap insurance is financial peace of mind. It protects you from the unexpected costs associated with replacing a lost or damaged drone. Other key features and benefits include:
- Protection Against Depreciation: The core function is to mitigate the financial impact of your drone losing value over time.
- New for Old Replacement: Many gap insurance policies for drones are designed to facilitate a “new for old” replacement, meaning you get a brand-new drone, not a used or refurbished one.
- Reduced Out-of-Pocket Expenses: It significantly minimizes or eliminates the money you’d have to spend to replace your drone after a claim.
- Adaptability to Financing: If you financed your drone, gap insurance ensures that even if the drone is totaled, you won’t be left paying for a vehicle you can no longer use, a common issue with auto gap insurance.
- Comprehensive Coverage for Specialized Equipment: Given the high cost of advanced drone technology, gap insurance is a logical extension of standard coverage for these sophisticated tools.
When is Gap Insurance Most Relevant for Drones?
The decision to purchase gap insurance for your drone should be based on several factors, primarily relating to the value of your drone, how it’s financed, and your risk tolerance.
High-Value Drone Investments
If you’ve invested in a professional-grade drone, such as a DJI Inspire series, a Matrice, or a specialized cinematic platform, the initial cost can be substantial. These drones are often equipped with advanced imaging systems, powerful processors, and proprietary software that make them expensive to replace. For such high-value assets, gap insurance is a prudent investment. The potential depreciation on a $5,000+ drone can easily create a gap that gap insurance can effectively cover.
Drones Financed Through Loans or Leases
As with automobiles, if your drone purchase was financed through a loan or lease agreement, gap insurance becomes particularly valuable. If the drone is declared a total loss, your primary insurance payout might not cover the outstanding balance on your loan or lease. Gap insurance ensures that you are not left owing money on a lost asset. This protects your credit and prevents a significant financial burden.
Drones Used for Commercial Purposes
Commercial drone operators often face higher risks and operate more frequently, increasing the likelihood of an incident. If your drone is your primary income-generating tool, any downtime or unexpected replacement cost can have a significant impact on your business. Gap insurance, combined with robust commercial drone insurance, provides an extra layer of financial security, ensuring you can quickly get back to operational status with minimal business disruption.
Operator’s Risk Tolerance and Financial Situation
Ultimately, the decision to purchase gap insurance also comes down to your personal financial situation and your comfort level with risk. If you have a substantial emergency fund and can easily absorb the cost of replacing your drone out-of-pocket should the need arise, gap insurance might be less critical. However, for many, the relatively small cost of a gap insurance policy provides significant peace of mind, protecting against a potentially large, unexpected expense.
Navigating Drone Insurance Policies and Gap Coverage
Acquiring the right insurance for your drone can feel complex, but understanding the nuances of coverage, especially gap insurance, is key to making informed decisions.
Types of Drone Insurance Available
Before considering gap insurance, it’s essential to understand the primary insurance options for drones:
- Hull Insurance: This covers physical damage to the drone itself, whether from an accident, crash, or theft. This is the most common type of coverage and what your gap insurance would supplement.
- Liability Insurance: This covers third-party damages or injuries caused by your drone. This is crucial for commercial operations and increasingly important for hobbyists to protect against accidental damage to property or injury to individuals.
- Payload Insurance: This can cover damage to the camera or other equipment attached to the drone.
Where to Find Gap Insurance for Drones
Gap insurance for drones is not as universally available as it is for automobiles. It is typically offered by:
- Specialized Drone Insurance Providers: Many companies that offer hull and liability insurance for drones also offer optional gap coverage as an add-on to their policies.
- Financing Companies: If you financed your drone through a specific lender, they may offer their own gap insurance product, similar to auto loan gap coverage.
- Independent Insurance Brokers: Some independent brokers may have access to specialized gap insurance policies for high-value equipment.

Key Questions to Ask Your Insurer
When exploring gap insurance for your drone, be sure to ask your insurance provider the following questions:
- What is the exact definition of “replacement cost” in your policy? Does it cover a brand-new drone of equivalent make and model?
- What is the maximum payout for the gap coverage? Is there a limit to how much the gap insurance will cover?
- What is the deductible for the gap insurance claim? Does it apply in addition to or separately from the hull insurance deductible?
- Are there any exclusions for specific types of damage or operating conditions? For instance, does it cover damage during racing or acrobatic maneuvers?
- How long does the gap insurance coverage last? Is it a one-time purchase or an annual renewal?
- What is the process for filing a gap insurance claim? What documentation will be required?
By understanding these elements, drone operators can make informed decisions about protecting their valuable assets and ensuring that a costly accident or loss doesn’t lead to significant financial strain. Gap insurance, when properly understood and applied, is a vital tool in the comprehensive insurance strategy for any serious drone pilot.