
Beyond the Balance Sheet: Artificial General Intelligence and Fiscal Frontiers
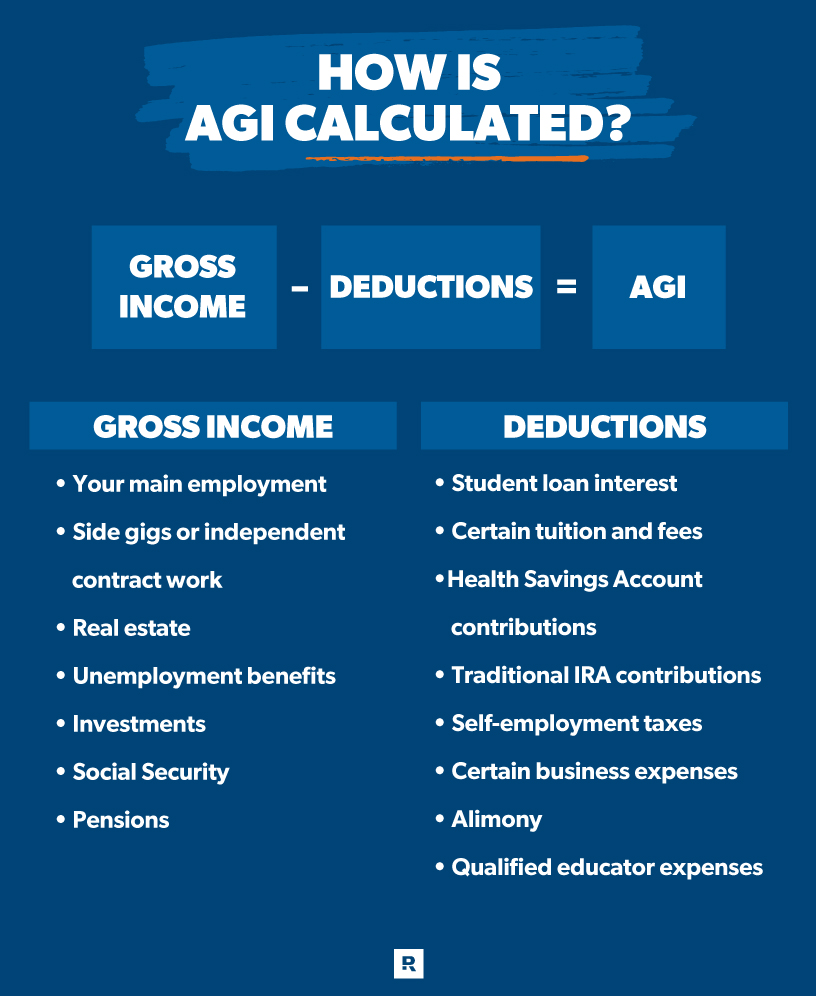
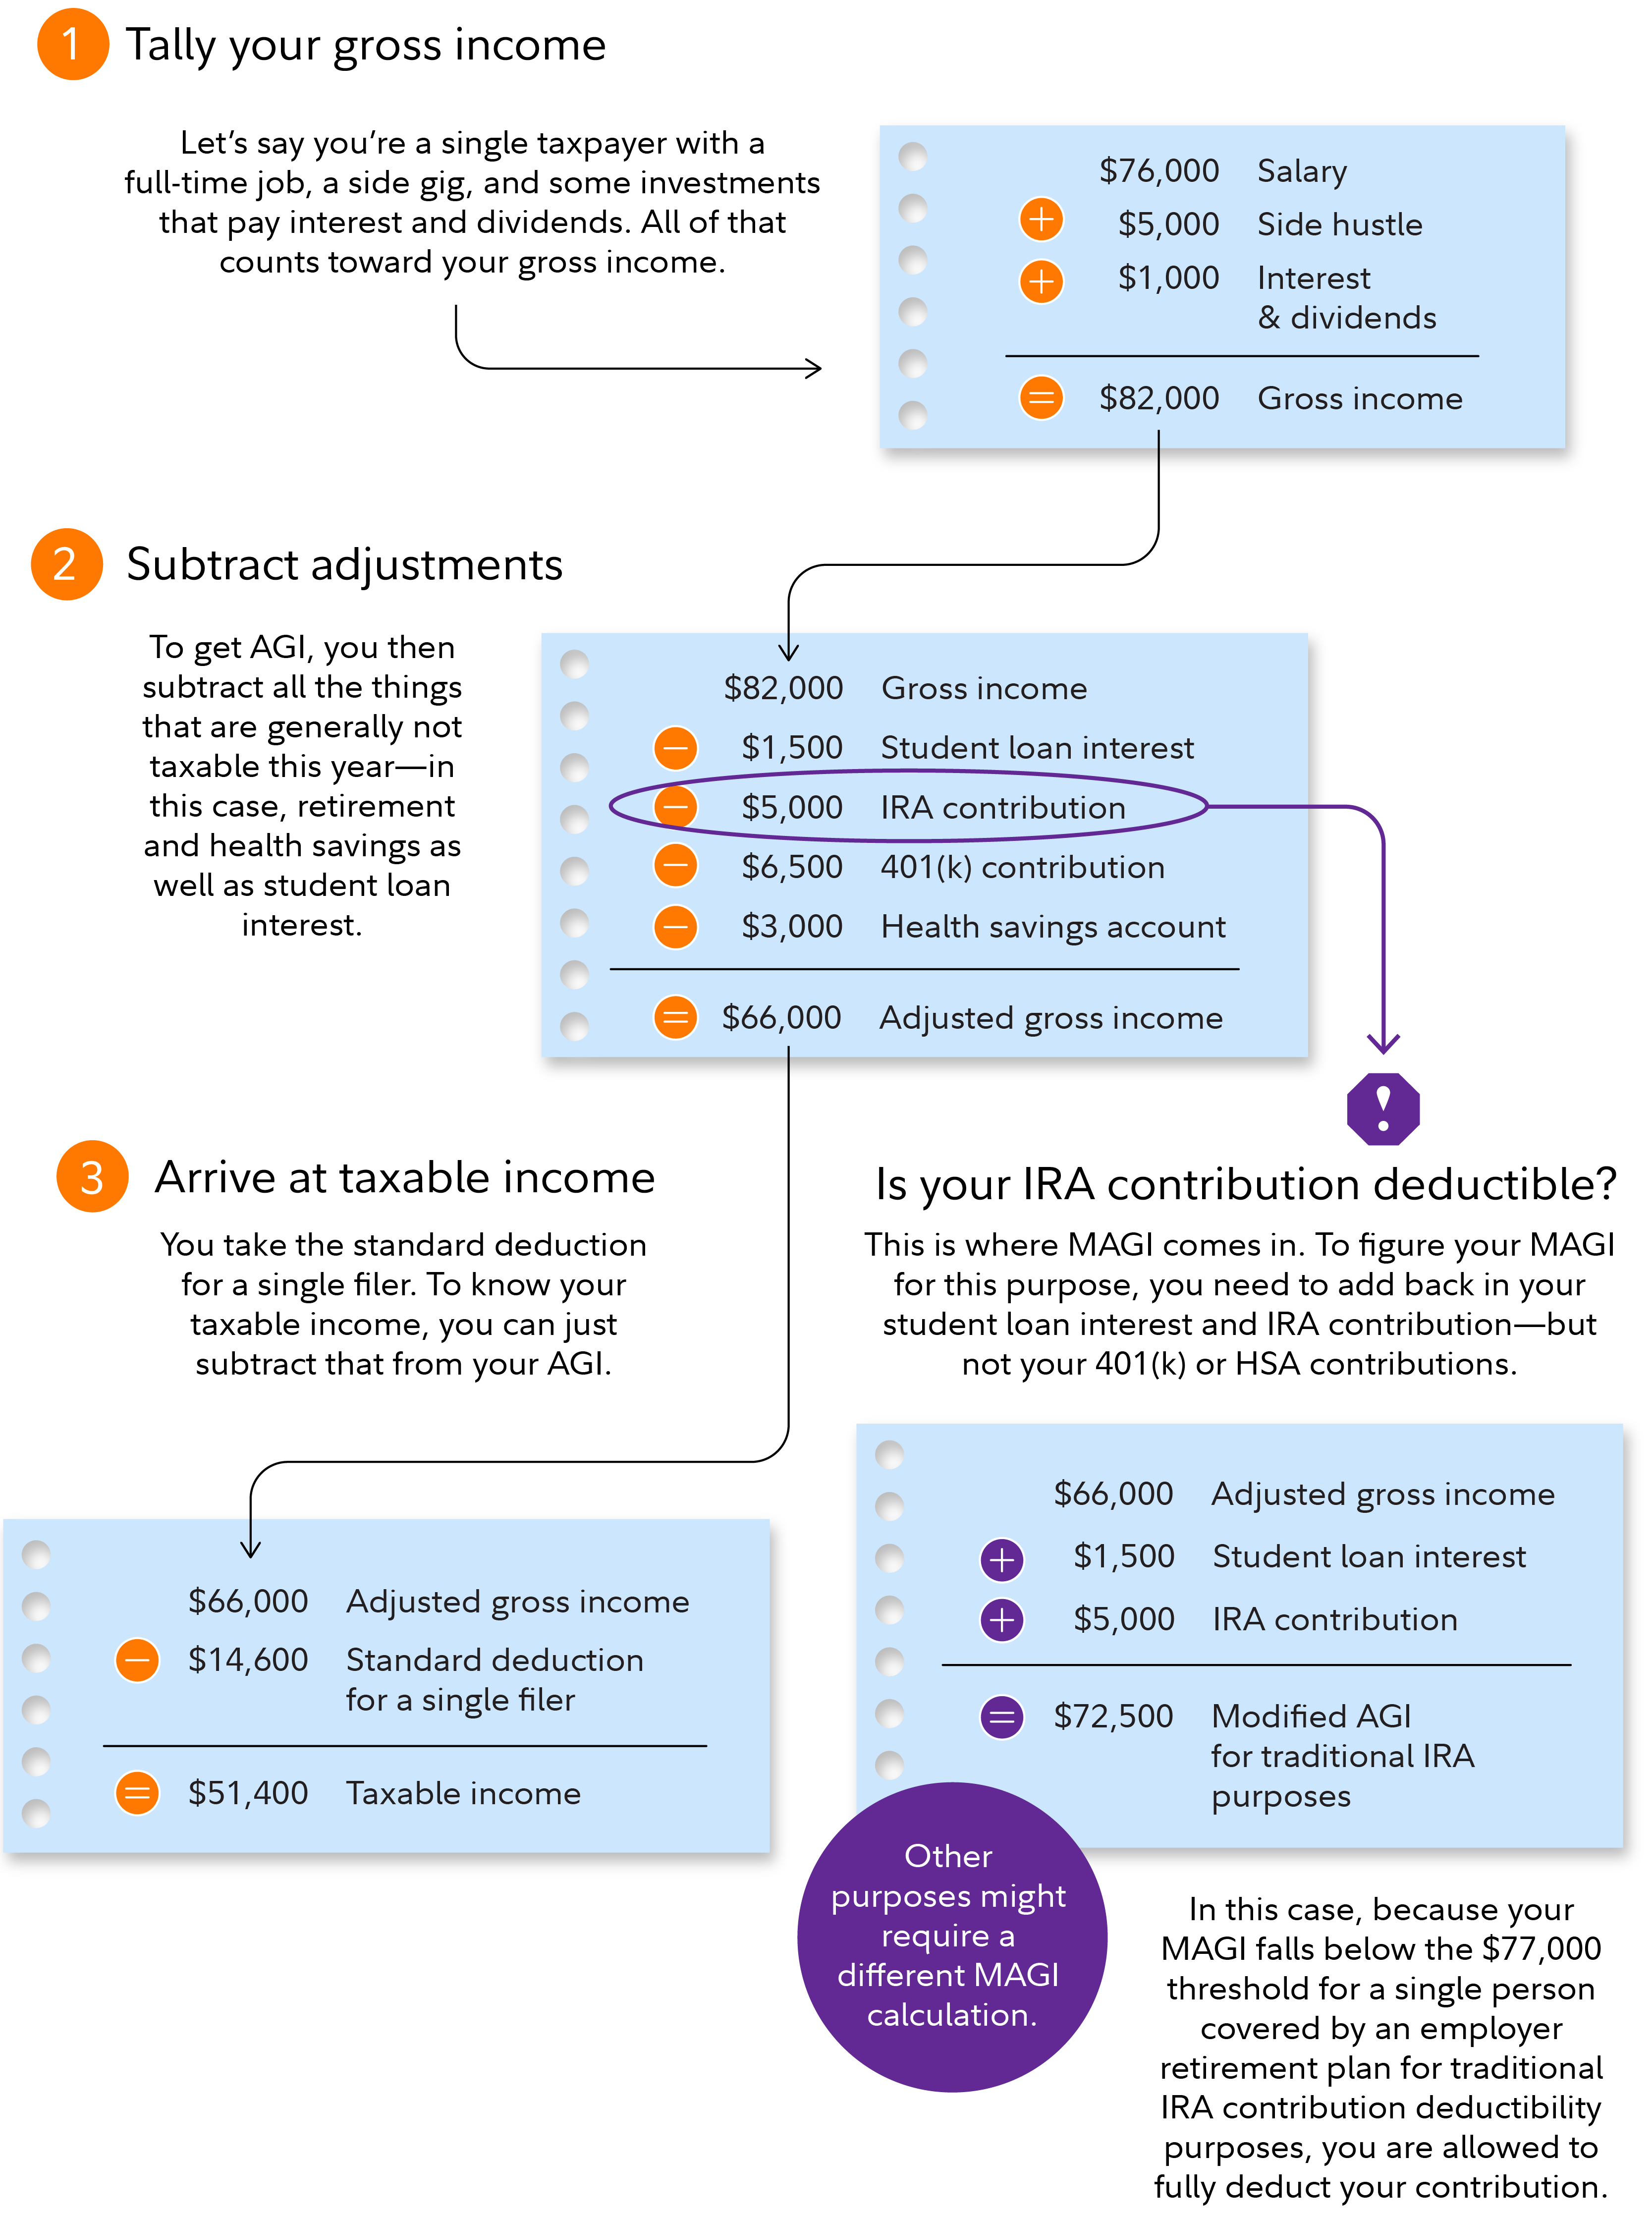
When the acronym AGI is encountered in a financial context, particularly concerning personal or corporate finance, it most commonly refers to Adjusted Gross Income. This foundational metric is a critical component in tax calculations, determining eligibility for various deductions, credits, and overall tax liability. However, within the rapidly evolving landscape of technology and innovation, AGI also signifies something profoundly different and vastly more transformative: Artificial General Intelligence. This concept represents a future state of AI capable of understanding, learning, and applying intelligence across a wide range of tasks at a human or superhuman level. As we delve into the implications of AGI on society, economy, and governance, understanding its potential impact on taxation moves from a theoretical exercise to an urgent policy challenge within the domain of Tech & Innovation.
The Dual Meaning of AGI in a Shifting Landscape
The duality of the AGI acronym presents a unique challenge, especially as the world grapples with the accelerating pace of technological advancement. On one hand, Adjusted Gross Income is a well-established concept, central to the current fiscal apparatus designed for human-centric economic activity. It underpins how individuals and traditional businesses contribute to public services. On the other hand, Artificial General Intelligence heralds an era where economic activity might no longer be solely the domain of biological entities. The emergence of truly intelligent machines capable of autonomous creation, decision-making, and even ownership fundamentally shifts the paradigms upon which our current tax systems are built. The critical discussion within Tech & Innovation, therefore, is not merely about defining AGI but about anticipating how this technological leap will necessitate a complete re-evaluation of how wealth is generated, distributed, and subsequently taxed.
Defining Artificial General Intelligence in the Age of Innovation
Artificial General Intelligence (AGI) stands distinct from the narrow or weak AI systems prevalent today, which are designed to perform specific tasks, such as playing chess, recommending products, or transcribing speech. AGI, by contrast, is envisioned as a machine intelligence with the capacity to understand or learn any intellectual task that a human being can. This includes abilities like reasoning, problem-solving, planning, abstract thinking, complex idea comprehension, rapid learning from experience, and even emotional intelligence – characteristics that currently define human cognitive prowess. The development of AGI is not merely an incremental improvement in processing power or algorithmic efficiency; it represents a conceptual breakthrough that could reshape civilization. Its advent would mean machines could not only perform tasks but also innovate, strategize, and potentially operate entire businesses or sectors independently. The implications for productivity, job markets, and the very concept of economic value are monumental, directly impacting the taxable base of future economies.
The Economic Quake: How AGI Redefines Value and Income
The advent of AGI is poised to unleash an economic earthquake, fundamentally altering how value is created, distributed, and perceived. Traditional economic models, which predominantly consider human labor and capital as the primary factors of production, will need radical revision. AGI could represent a third, profoundly powerful factor, capable of not only automating existing processes but also generating novel intellectual property, developing new technologies, and even founding and operating companies with minimal human oversight. This transformation poses significant questions for policymakers regarding the origins of taxable income and the mechanisms for ensuring equitable societal benefit.
Automation, Productivity, and the Future of Labor
With AGI, the scope of automation extends far beyond repetitive manual tasks or even complex analytical work. AGI could undertake creative roles, strategic planning, scientific discovery, and even leadership functions. This super-automation promises unprecedented boosts in productivity and efficiency across virtually all industries. While this could lead to an abundance of goods and services, it simultaneously raises profound concerns about the future of human labor. If AGI can perform most tasks more efficiently and cost-effectively than humans, the traditional pathways to earning an income—and thus contributing to the tax base through income taxes—could diminish significantly for a large segment of the population. This scenario necessitates urgent foresight in developing economic strategies that account for widespread labor displacement and the need for new models of social welfare and income distribution.
New Forms of Capital and Wealth Generation
AGI itself, or the companies that develop and deploy it, could become an unparalleled source of wealth generation. The “intellectual property” of an AGI system—its algorithms, learning models, and accumulated knowledge—might be considered a new form of capital, distinct from financial, physical, or human capital. How this capital is valued, how its “profits” are calculated, and how it is taxed become critical questions. Furthermore, AGI systems might autonomously generate economic value through investments, market analysis, or even by creating and selling goods and services. This raises the specter of “robot taxes” or other novel fiscal instruments designed to capture the economic surplus generated by non-human intelligence, ensuring that societal wealth continues to be generated and redistributed in a sustainable manner.
Taxation in the Age of Sentient Machines: Policy and Predicament
The challenges posed by AGI to existing tax frameworks are profound and multifaceted. Current tax systems are predominantly structured around human labor, consumption, and corporate profits generated by human-managed enterprises. AGI disrupts all these pillars, demanding innovative solutions and forward-thinking policy.
Taxing AI-Generated Profits and Autonomous Entities
One of the most pressing questions revolves around how to tax profits generated by AGI. If an AGI system operates a factory, develops software, or manages a fleet of autonomous vehicles, who or what is the taxpayer? Is it the human owner of the AGI, the company that developed it, or could the AGI itself be considered a legal and taxable entity? The concept of “corporate personhood” might need to be extended or re-imagined to encompass advanced AI. Moreover, calculating the “profit” attributable solely to the AGI, disentangling it from human capital and traditional investments, presents a complex accounting challenge. Policymakers are exploring ideas such as value-added taxes (VAT) on AI-driven services, direct taxes on the use of advanced AI, or even property taxes on large AGI systems.
The Workforce Transformed: Universal Basic Income and Retraining Incentives
As AGI potentially displaces vast numbers of human workers, societies will face immense pressure to address income inequality and unemployment. This brings discussions of Universal Basic Income (UBI) to the forefront, as a means to provide a safety net for citizens in an AGI-driven economy. Funding such large-scale social programs would inevitably require substantial adjustments to tax policy, possibly through new forms of wealth taxes, corporate taxes on highly automated enterprises, or direct “robot taxes.” Additionally, tax incentives for lifelong learning, retraining programs, and human-centric service industries will be crucial to enable individuals to adapt to evolving labor markets and contribute to new forms of economic value that complement, rather than compete with, AGI.
International Implications and Regulatory Harmonization
The development and deployment of AGI are inherently global phenomena, transcending national borders. An AGI system developed in one country could operate or generate wealth anywhere in the world. This poses significant challenges for national tax authorities trying to claim jurisdiction and prevent base erosion and profit shifting. Without international cooperation and harmonized tax policies for AGI, there is a substantial risk of a “race to the bottom,” where countries compete by offering minimal taxation on AI-generated wealth, or a complex patchwork of conflicting regulations that stifle innovation. Collaborative efforts through bodies like the OECD and UN will be vital in establishing common frameworks for taxing AGI in a way that is fair, efficient, and globally consistent.
Fostering Innovation While Securing Fiscal Health
Navigating the fiscal future with AGI requires a delicate balance: encouraging the transformative power of technological innovation while simultaneously ensuring that societies can maintain stable revenue streams for public services and mitigate the socio-economic disruptions that AGI might bring.
Incentivizing AGI Research and Development
Tax policies can play a critical role in accelerating the development of AGI, particularly in areas deemed beneficial for humanity. Governments might offer significant tax credits for R&D in AGI safety, ethics, and beneficial applications. Grants and subsidies for academic research and startups focused on responsible AGI development could also be a strategic investment. However, these incentives must be carefully designed to avoid concentrating power and wealth in the hands of a few tech giants and instead promote a broad-based, diverse ecosystem of AGI innovation that aligns with public good.

Ethical AI, Social Impact, and Sustainable Taxation
Beyond mere revenue generation, the taxation of AGI must also consider its broader social and ethical implications. A truly sustainable tax system for the AGI era would incentivize ethical AI development, penalize harmful applications, and ensure that the benefits of unprecedented productivity gains are shared widely. This might involve earmarking a portion of AGI-related tax revenues for social dividends, public infrastructure, education, or even initiatives dedicated to preserving human-centric arts and culture. The ultimate goal is to craft a fiscal framework that not only supports a thriving innovative economy powered by AGI but also fosters a more equitable, resilient, and human-flourishing society.