
Understanding the California Use Tax: A Vital Component of State Revenue
California’s economy thrives on a complex system of taxation, designed to fund essential public services and infrastructure. While sales tax is widely recognized and collected at the point of purchase for tangible personal property, a less understood but equally important levy is the use tax. This tax is specifically designed to capture revenue on goods purchased outside of California for use within the state, thereby ensuring a level playing field for in-state businesses and maintaining the state’s revenue stream.
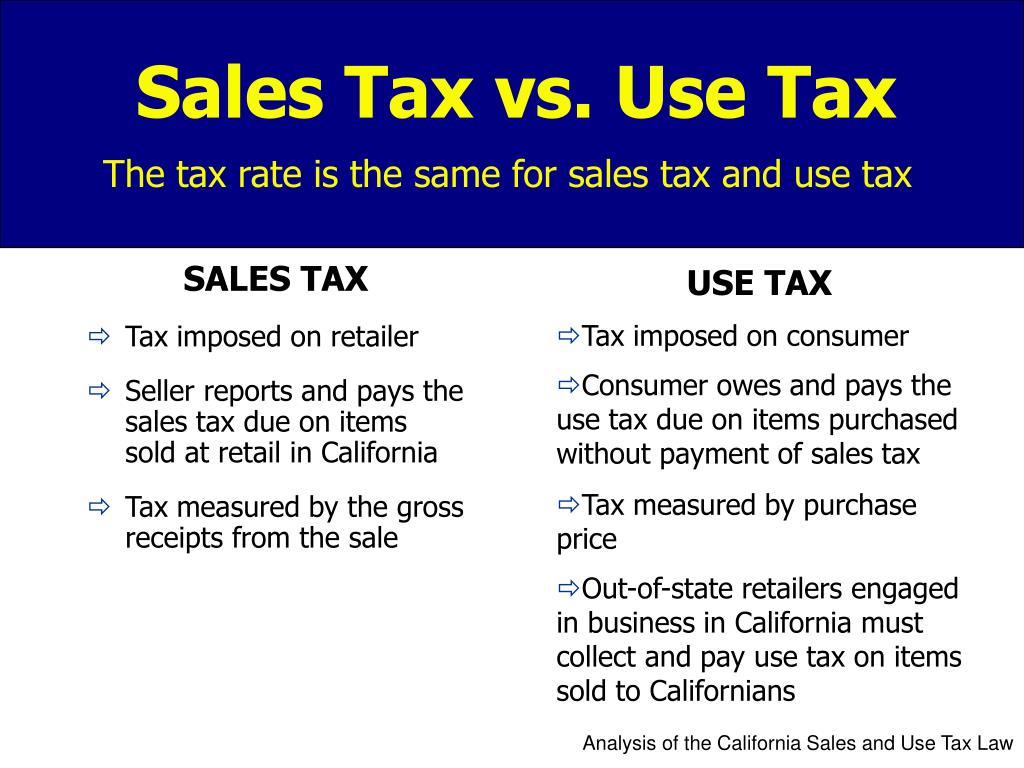
The fundamental principle behind the use tax is to complement the sales tax. When a resident or business in California purchases an item from an out-of-state vendor, especially through online retailers, mail order catalogs, or direct shipments, California sales tax is typically not collected at the time of sale. Without a use tax, these transactions would effectively escape taxation, creating an unfair advantage for out-of-state sellers and a disadvantage for California retailers who are obligated to collect sales tax. The use tax acts as a safeguard against this potential revenue loss and tax avoidance.
The Nexus Requirement: When Does Use Tax Apply?
The application of California’s use tax is not automatic for every out-of-state purchase. A key concept governing its imposition is the nexus. Nexus, in this context, refers to a sufficient connection or link between the seller and the state of California that allows the state to assert its taxing authority. Traditionally, nexus was established through a physical presence in the state, such as having a store, warehouse, or employees.
However, the landscape of nexus has evolved significantly, particularly with the rise of e-commerce. The landmark U.S. Supreme Court decision in South Dakota v. Wayfair, Inc. (2018) dramatically altered the interpretation of nexus, moving beyond physical presence to include economic nexus. Under economic nexus rules, a seller can be deemed to have nexus with California if their sales into the state exceed certain thresholds, even without a physical presence. For California, these thresholds are generally defined by an annual dollar amount of sales or a specific number of separate transactions into the state. This shift has broadened the reach of the use tax to encompass a much larger volume of online transactions.
Once nexus is established, a seller is generally required to register with the California Department of Tax and Fee Administration (CDTFA) and begin collecting and remitting the applicable use tax on sales made to California customers. This collected tax is then remitted to the state.
Who is Responsible for Paying Use Tax?
The primary obligation for paying use tax falls on the consumer or user of the tangible personal property purchased from an out-of-state vendor. This means that if a California resident or business purchases an item from an out-of-state seller and that seller does not collect the use tax at the time of sale, the buyer is legally responsible for self-reporting and remitting the use tax to the CDTFA. This is often done annually when filing state income tax returns, or through separate reporting mechanisms for businesses.
The rate of the use tax is generally the same as the combined state and local sales tax rate in effect at the location where the property is first used in California. This ensures that the tax burden is equivalent to what would have been paid if the item had been purchased within the state. For example, if an item is purchased online from a seller in another state and then brought to Los Angeles for use, the use tax rate would be the combined sales tax rate for Los Angeles.
It’s crucial for individuals and businesses to understand this self-reporting obligation. Failure to do so can result in penalties and interest when the underreporting is discovered by the CDTFA. The state employs various methods to identify non-compliance, including data matching and audits.
Exemptions and Exclusions from Use Tax
While the use tax is broadly applicable, there are specific exemptions and exclusions designed to address certain situations. Understanding these exceptions is vital to correctly determining tax liability.
Previously Taxed Property
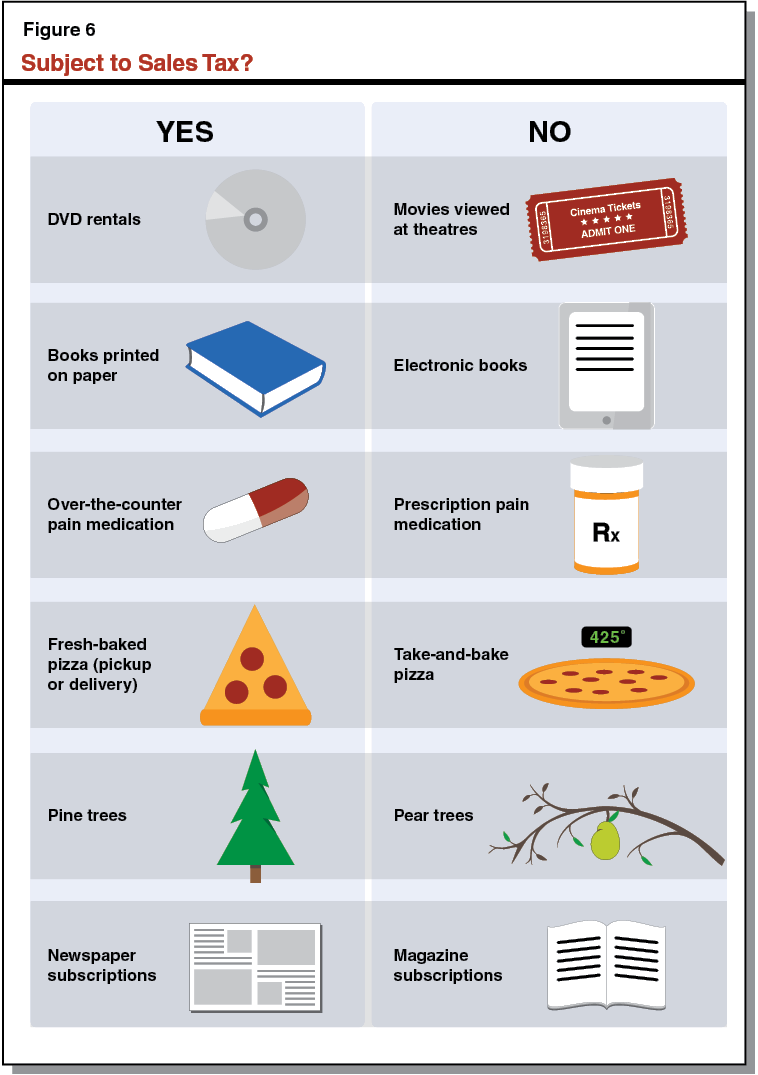
Perhaps the most significant exemption is for property that has already been subjected to a sales or use tax in another state. If you purchase an item in another state and pay sales tax to that state, and then bring that item into California for use, you are generally entitled to a credit for the tax paid. This credit can offset the California use tax liability, preventing double taxation. However, this exemption typically applies only up to the amount of California use tax due. If the sales tax paid in the other state is lower than the California use tax rate, the difference would still be due to California.
Certain Types of Property and Transactions
California law also exempts specific types of property or transactions from the use tax. These can include:
- Property for Resale: Goods purchased for the purpose of resale in the regular course of business are generally exempt from use tax, as they will be subject to sales tax when sold to the final consumer.
- Materials Consumed in Manufacturing: Certain raw materials or components that become part of a manufactured product intended for sale may be exempt.
- Property Used in Interstate or Foreign Commerce: Goods that are demonstrably and primarily used in activities that constitute interstate or foreign commerce might qualify for exemptions.
- Certain Agricultural Products: Specific agricultural products or inputs may be subject to exemptions.
- Gifts and Inheritances: Items received as bona fide gifts or through inheritance are typically not subject to use tax, as there was no purchase transaction.
It is essential to consult the specific regulations and publications from the CDTFA or seek professional tax advice to determine if a particular purchase qualifies for an exemption. The definition of “use” and the specific criteria for each exemption can be nuanced.
The Role of E-commerce and Online Retailers
The advent of the internet and the explosion of e-commerce have profoundly impacted the collection and administration of sales and use taxes. Before Wayfair, many out-of-state online retailers, lacking a physical presence in California, did not collect sales tax. This left California consumers with the responsibility of self-reporting and remitting use tax, a process that often went overlooked.
Following the Wayfair decision and subsequent legislation and regulations in California, online retailers that meet certain economic nexus thresholds are now required to register and collect the use tax from their California customers. This has significantly increased the compliance of out-of-state sellers and improved California’s ability to capture revenue that was previously lost.
For consumers, this shift means that many purchases made from online marketplaces or directly from out-of-state e-commerce sites will now have the California use tax automatically calculated and collected at checkout. This simplifies the tax compliance process for many individuals and businesses. However, it remains important to be aware of the tax when purchasing from smaller vendors or through platforms where tax collection might not be uniformly applied.
Compliance and Enforcement
The California Department of Tax and Fee Administration (CDTFA) is the primary agency responsible for administering and enforcing the state’s sales and use tax laws. The CDTFA employs a range of strategies to ensure compliance, including:
- Audits: The CDTFA conducts audits of businesses and individuals to verify the accuracy of reported sales and use tax liabilities. These audits can be triggered by various factors, including industry trends, data analysis, or referrals.
- Information Sharing: The agency engages in data sharing agreements with other state tax agencies and federal entities to identify potential non-compliance.
- Public Awareness Campaigns: The CDTFA periodically conducts campaigns to educate taxpayers about their sales and use tax obligations, particularly concerning the use tax and the importance of self-reporting.
- Enforcement Actions: For instances of deliberate tax evasion or significant underreporting, the CDTFA has enforcement powers that can include the assessment of penalties, interest, and, in severe cases, legal action.
For businesses operating in or selling to California, maintaining accurate records of all purchases, sales, and tax payments is paramount. This includes documenting any claims for exemptions or credits. For individuals, diligently reviewing purchase receipts and tax forms can help ensure that use tax obligations are met.
Conclusion: A Cornerstone of California’s Fiscal Health
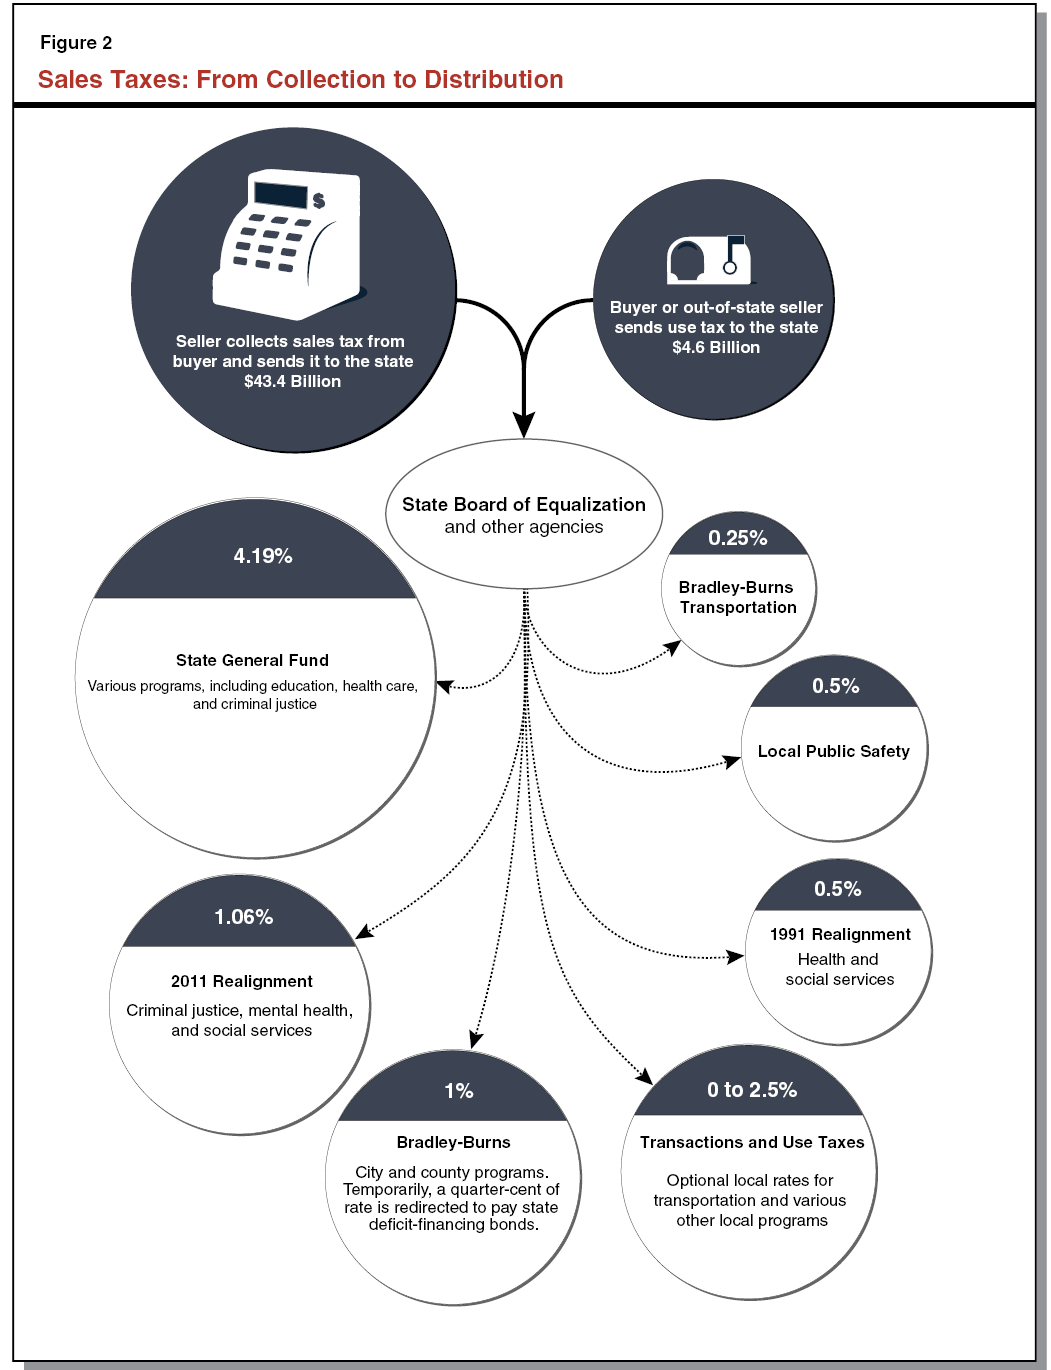
The California use tax, though often less visible than its sales tax counterpart, is a critical mechanism for maintaining the state’s revenue base and promoting fair competition within its borders. By ensuring that goods consumed in California are taxed, regardless of where they were purchased, the use tax contributes essential funds for education, transportation, public safety, and a myriad of other services that benefit all Californians. Understanding its principles, recognizing when it applies, and diligently fulfilling reporting obligations are vital for both individuals and businesses operating within the Golden State. As the economy continues to evolve, particularly with the ongoing growth of e-commerce, the significance of the use tax in California’s fiscal landscape will only continue to be amplified.