
The automatic stay is a powerful injunction that takes effect automatically the moment a bankruptcy petition is filed in the United States. It is a fundamental protection under U.S. bankruptcy law, designed to provide immediate relief to debtors by halting most collection actions by creditors. This legal shield gives debtors a crucial breathing room, allowing them time to reorganize their finances or liquidate assets without the relentless pressure of ongoing collection efforts. Understanding the scope and limitations of the automatic stay is essential for anyone considering bankruptcy or dealing with a debtor who has filed.
The Immediate Impact and Purpose of the Automatic Stay
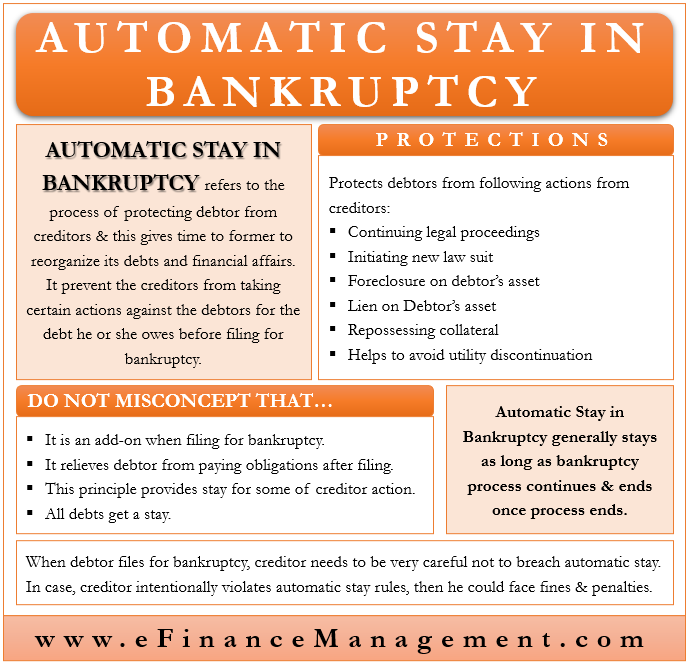
Upon the filing of a bankruptcy petition—whether Chapter 7, Chapter 11, Chapter 12, or Chapter 13—the automatic stay immediately comes into force under Section 362 of the U.S. Bankruptcy Code. Its primary purpose is twofold: to protect the debtor and to ensure the orderly administration of the bankruptcy estate.
Protection for the Debtor
For an individual or business facing overwhelming debt, the automatic stay is often the most immediate and tangible benefit of filing for bankruptcy. It stops creditors dead in their tracks, preventing them from taking any further action to collect debts. This cessation of collection activities alleviates immense stress and allows the debtor to focus on the bankruptcy process itself. Without this protection, creditors could continue to seize assets, garnish wages, or harass the debtor, undermining the very purpose of bankruptcy relief.
Orderly Administration of the Bankruptcy Estate
Beyond debtor protection, the automatic stay serves a critical role in preserving the bankruptcy estate. It creates a temporary moratorium on individual creditor actions, ensuring that all creditors are treated fairly and equitably according to the Bankruptcy Code. Without the stay, a “race to the courthouse” could ensue, where creditors vie to seize the debtor’s assets, leading to chaotic distribution and potentially leaving some creditors with nothing. The stay prevents this free-for-all, allowing the bankruptcy trustee or debtor-in-possession to gather all assets, assess liabilities, and develop a plan for distribution or reorganization under the supervision of the bankruptcy court.
Scope of the Automatic Stay: What it Stops
The automatic stay is broad in its application, preventing a wide array of creditor actions. Its reach extends to most types of collection activities, regardless of whether the debt is secured or unsecured.
Halting Collection Actions
The stay stops virtually all efforts by creditors to collect on debts incurred before the bankruptcy filing. This includes:
- Lawsuits and judgments: Creditors cannot initiate new lawsuits or continue existing ones to collect debts. Any pre-existing judgments cannot be enforced.
- Wage garnishments: Employers must cease withholding a portion of the debtor’s wages to satisfy a debt.
- Bank account levies: Creditors are prohibited from seizing funds from the debtor’s bank accounts.
- Foreclosures and repossessions: Actions to foreclose on a home or repossess a vehicle are halted.
- Collection calls and letters: Creditors must stop all communication aimed at debt collection, including phone calls, emails, and physical mail.
- Utility shut-offs: Utility companies generally cannot disconnect service for unpaid pre-petition bills (though debtors may need to provide adequate assurance of future payments).
- Evictions: In most cases, if a debtor is facing eviction, the automatic stay will temporarily halt the process, though specific rules apply depending on the stage of the eviction and state law.
Exceptions to the Automatic Stay
While powerful, the automatic stay is not absolute. The Bankruptcy Code outlines several significant exceptions where certain actions are not stopped or can proceed despite the bankruptcy filing. These exceptions primarily concern matters deemed more urgent or those that do not directly involve the debtor’s pre-petition financial obligations.
Common exceptions include:
- Criminal proceedings: The stay does not apply to criminal actions against the debtor.
- Child support and alimony: Actions to establish, modify, or collect domestic support obligations (child support or alimony) are generally not stayed.
- Certain tax proceedings: While some tax collection efforts are stayed, certain audits, assessments, and demands for tax returns may continue.
- Perfection of liens: In some cases, a creditor can take action to “perfect” a lien (e.g., filing a document to secure their interest) without violating the stay, provided certain conditions are met.
- Actions by government regulatory bodies: Government units exercising their police or regulatory power (e.g., environmental enforcement actions, licensing revocations) may not be stayed.
- Repeated bankruptcy filings: If a debtor has filed multiple bankruptcy cases within a short period, the automatic stay may be limited in duration or not apply at all, reflecting concerns about abuse of the system.
It is crucial for debtors to understand these exceptions, as they can still face legal actions in these specific areas even after filing for bankruptcy.
Duration and Termination of the Automatic Stay

The automatic stay is temporary. Its duration varies depending on the chapter of bankruptcy, the type of debt, and the specific circumstances of the case.
Typical Duration
- Chapter 7 (Liquidation): The stay typically remains in effect until the case is closed, dismissed, or the debtor receives a discharge. For specific property, it may terminate sooner if the property is no longer considered part of the bankruptcy estate (e.g., if a secured creditor is granted relief from the stay).
- Chapter 13 (Reorganization): In Chapter 13 cases, the stay generally remains in effect as long as the debtor is making payments under their confirmed repayment plan or until the case is closed or dismissed.
Relief from the Automatic Stay
Creditors who believe their interests are unduly harmed by the automatic stay can petition the bankruptcy court for “relief from stay.” This is a common occurrence, particularly for secured creditors like mortgage lenders or car loan companies.
Reasons a court might grant relief from stay include:
- Lack of adequate protection: If the creditor’s collateral (e.g., a house or car) is decreasing in value and the debtor is not making payments to compensate for this depreciation, the court may find the creditor lacks “adequate protection” of their interest.
- Lack of equity: If there is no equity in the property (i.e., the debt owed on it is greater than its value), and the property is not necessary for an effective reorganization (relevant in Chapter 11/13), the court may grant relief.
- No reasonable prospect of reorganization: In business bankruptcies, if there’s no realistic chance the business can successfully reorganize, the stay might be lifted to allow creditors to pursue their claims.
- Bad faith filings: If the court determines the bankruptcy petition was filed in bad faith, solely to delay creditors, it may lift the stay.
If a court grants relief from the automatic stay, the creditor is then permitted to resume collection actions against the specific property or debt outlined in the court’s order. This often leads to foreclosure, repossession, or continuation of lawsuits.
Impact of Serial Filings
The Bankruptcy Abuse Prevention and Consumer Protection Act of 2005 (BAPCPA) introduced provisions to address perceived abuses of the automatic stay, particularly by debtors who repeatedly file for bankruptcy.
- Second filing within one year: If a debtor files a second bankruptcy case within one year of a previous case being dismissed, the automatic stay is automatically limited to 30 days unless the debtor files a motion and convinces the court to extend it, demonstrating that the new filing is in good faith.
- Third or subsequent filing within one year: If a debtor files a third or subsequent bankruptcy case within one year of the dismissal of two prior cases, the automatic stay does not go into effect at all unless the debtor files a motion and convinces the court that the filing is in good faith.
These provisions aim to prevent debtors from using successive bankruptcy filings solely to invoke the automatic stay and repeatedly delay creditors without genuinely pursuing debt relief.
Consequences of Violating the Automatic Stay
The automatic stay is a court order, and violating it can have serious repercussions. Creditors who knowingly disregard the stay can face significant penalties.
Penalties for Creditors
If a creditor takes action to collect a debt in violation of the automatic stay, the debtor can ask the bankruptcy court to enforce the stay. The court can:
- Order the creditor to return seized property: Any assets improperly taken must be returned to the debtor.
- Award actual damages: This includes financial losses incurred by the debtor due to the violation (e.g., lost wages from garnishment, legal fees).
- Award punitive damages: In cases of egregious or willful violations, the court may impose punitive damages to punish the creditor and deter similar conduct in the future.
- Impose contempt of court: The creditor could be held in contempt of court, leading to fines or even imprisonment in extreme cases.
It’s important to note that the creditor must have knowledge of the bankruptcy filing for damages to typically be awarded. However, the stay is effective upon filing, even if the creditor has not yet received official notice. Once a creditor is aware of the bankruptcy, they must cease all collection activity.
Conclusion
The automatic stay is a cornerstone of U.S. bankruptcy law, providing an indispensable shield for debtors and a mechanism for the orderly administration of bankruptcy cases. While it offers immediate and broad protection from most collection activities, it is not without exceptions and limitations. Debtors must understand its scope, duration, and potential for relief from stay, while creditors must respect its authority to avoid severe penalties. Navigating the complexities of the automatic stay often requires the expertise of a qualified bankruptcy attorney, ensuring that both debtors’ rights and creditors’ obligations are appropriately managed within the legal framework.