
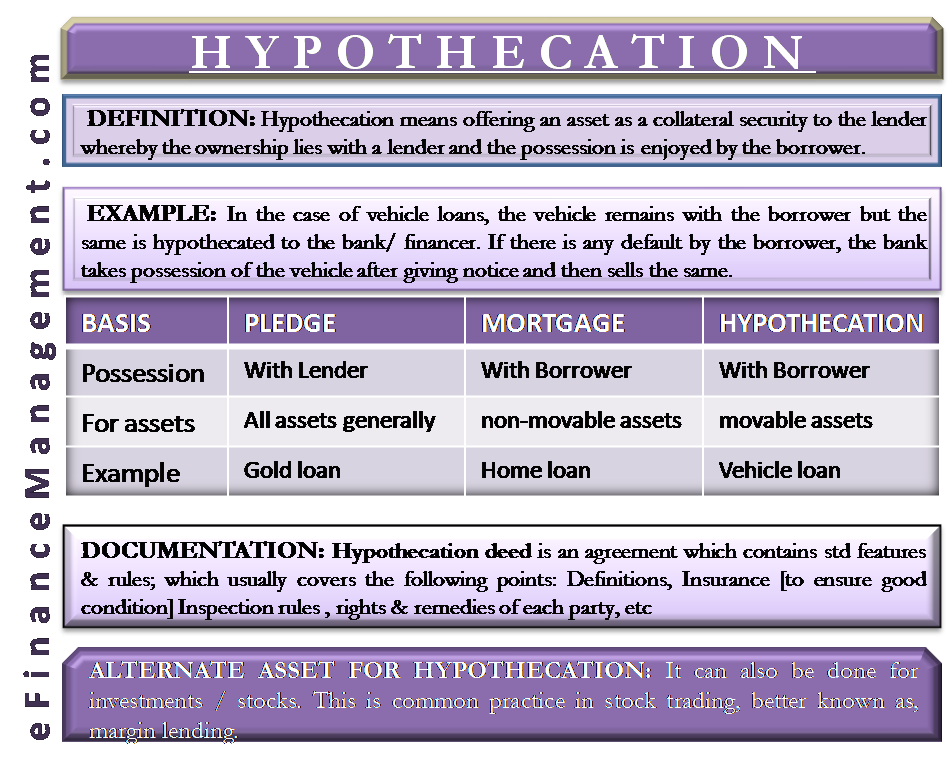
Hypothecation, while not a term commonly found in everyday real estate parlance, is a fundamental concept that underpins much of the financial machinery driving property transactions. It’s a crucial element for anyone involved in property investment, lending, or even purchasing a home with a mortgage. At its core, hypothecation refers to the act of pledging an asset as collateral for a loan, without giving up possession of that asset. In the context of real estate, this means using a property as security for a loan, typically a mortgage, while the borrower continues to occupy, use, and benefit from the property. Understanding this distinction is vital, as it differentiates hypothecation from other forms of security where the lender takes physical possession of the asset.
The Mechanics of Hypothecation in Property Ownership
The real estate market relies heavily on the ability of individuals and entities to leverage their assets to acquire more. Hypothecation is the mechanism that makes this possible for property. When a buyer seeks financing to purchase a property, the lender, usually a bank or financial institution, will require security for the loan. This security is the property itself.
Pledging Property as Collateral
The process begins with a borrower agreeing to hypothecate their property to the lender. This agreement is legally documented, typically through a mortgage deed or a deed of trust, depending on the jurisdiction. This document outlines the terms of the loan, the amount borrowed, the interest rate, the repayment schedule, and crucially, the lender’s rights in the event of default.
- Legal Framework: The legal framework surrounding hypothecation ensures that the lender has a secured interest in the property. This means that if the borrower fails to meet their loan obligations, the lender has the legal right to initiate foreclosure proceedings to recover their invested capital.
- Possession vs. Security Interest: A key characteristic of hypothecation is that the borrower retains possession and the right to use the property. They can live in it, rent it out, or otherwise benefit from its use. The lender, while holding a security interest, does not have immediate physical control. This is a crucial difference from, for instance, a pawn shop where the item pledged is held by the pawnbroker.
- The Mortgage as the Hypothecation Instrument: In most residential and commercial real estate transactions, the mortgage agreement serves as the primary instrument of hypothecation. The borrower mortgages their property to the lender.
The Role of Lenders and Borrowers
Hypothecation creates a symbiotic relationship between lenders and borrowers in the real estate sector.
- For Borrowers: Hypothecation enables individuals and businesses to acquire properties that would otherwise be financially out of reach. It unlocks the equity in an existing property to finance new acquisitions or other ventures. For example, a homeowner can take out a home equity loan, hypothecating their current home to secure the funds for a down payment on another property or for significant renovations.
- For Lenders: Hypothecation reduces the risk for lenders. By having the property as collateral, lenders have a tangible asset to fall back on if the borrower defaults. This security allows lenders to offer loans with more favorable terms, such as lower interest rates and longer repayment periods, than they might offer for unsecured loans. It facilitates the flow of capital into the real estate market, making property ownership more accessible.
Distinguishing Hypothecation from Other Security Interests
While hypothecation is about pledging an asset without giving up possession, other forms of security involve a transfer of possession or a different type of lien. Understanding these distinctions clarifies the unique nature of hypothecation in real estate.
Hypothecation vs. Pledge
The most common point of confusion is between hypothecation and a pledge.
- Hypothecation: As established, the borrower retains possession of the asset. The lender’s claim is registered against the asset, creating a charge or lien. Examples include mortgages on real estate and the use of shares as collateral for a loan where the borrower continues to hold the shares.
- Pledge: In a pledge, the borrower (pledgor) delivers the possession of the asset to the lender (pledgee) as security. The pledgee has physical control of the asset until the debt is repaid. Examples include pawning jewelry or using movable goods as collateral. In real estate, a pledge scenario would be highly unusual and impractical.
Hypothecation vs. Lien
While hypothecation creates a lien (a legal claim or right against a property to secure payment of a debt), the term “lien” itself is broader and can arise in various circumstances, not always through a voluntary hypothecation agreement.
- Voluntary Liens: A mortgage is a voluntary lien, meaning the property owner agrees to it to obtain a loan. Hypothecation is the act that creates this voluntary lien.
- Involuntary Liens: Other types of liens can be placed on a property without the owner’s consent. Examples include:
- Tax Liens: Placed by government authorities for unpaid property taxes.
- Mechanic’s Liens: Filed by contractors or suppliers who have performed work or supplied materials for a property but have not been paid.
- Judgment Liens: Issued by a court when someone owes a debt and the creditor obtains a court judgment against them.
In these involuntary scenarios, the lien holder has a claim on the property, but it’s not a result of the property owner voluntarily hypothecating the asset for a loan.
Hypothecation in Various Real Estate Scenarios
The principle of hypothecation is applicable across a wide spectrum of real estate transactions, from individual homeownership to large-scale commercial development.
Residential Mortgages
The most common example of hypothecation is the residential mortgage. When you take out a mortgage to buy a home, you hypothecate that home to the lender. You get to live in the house, but the lender has a security interest in it. If you stop making payments, the lender can foreclose and sell the house to recover their money. This allows millions of people to achieve homeownership by providing lenders with the necessary security to offer substantial loans.
Commercial Real Estate Loans
Hypothecation is equally crucial in commercial real estate. Businesses often use their existing properties, or the property they intend to purchase, as collateral to secure loans for expansion, development, or operational capital. A developer might hypothecate a parcel of land to secure construction financing. The land remains in their possession for development, but the lender has a claim against it.
Home Equity Loans and Lines of Credit (HELOCs)
These financial products are direct applications of hypothecation. Homeowners leverage the equity they have built up in their homes by borrowing against it.
- Home Equity Loan: A lump-sum loan secured by your home. You hypothecate the equity in your home to receive the funds.
- Home Equity Line of Credit (HELOC): A revolving credit line, similar to a credit card, secured by your home’s equity. You can draw funds as needed, up to a certain limit. Again, the home serves as collateral through hypothecation.
Refinancing Properties
When a property owner refinances their existing mortgage, they are essentially taking out a new loan, often with different terms, and using the property as collateral for this new loan. The original mortgage is paid off by the proceeds of the new loan, and the property is then hypothecated to the new lender.
The Importance of Understanding Hypothecation
For property owners, investors, and those seeking to enter the real estate market, a clear understanding of hypothecation is paramount. It demystifies the financial underpinnings of property ownership and borrowing.
Risk Management for Borrowers
Knowing that your property is hypothecated means understanding the implications of default. It underscores the critical importance of timely loan repayments. Defaulting on a hypothecated loan can lead to the loss of the property through foreclosure, a process that can have severe financial and personal consequences. Borrowers should always ensure they fully comprehend the terms and conditions of any loan agreement that involves hypothecation.
Enabling Property Investment and Development
Without the mechanism of hypothecation, the scale of real estate investment and development we see today would be significantly constrained. It provides the essential link between capital availability and property acquisition, fueling economic growth and wealth creation. Investors can acquire multiple properties, developers can undertake ambitious projects, and individuals can achieve the dream of homeownership, all facilitated by the lender’s security interest in the hypothecated asset.

Legal and Financial Implications
The legal documentation associated with hypothecation is extensive and binding. Agreements like mortgages and deeds of trust outline the rights and responsibilities of both the borrower and the lender. Understanding these legal documents, including clauses related to default, prepayment penalties, and the lender’s rights upon sale, is crucial. Financial advisors and legal professionals can provide invaluable guidance in navigating these complexities.
In essence, hypothecation is the invisible force that allows real estate to function as both a tangible asset and a powerful financial tool. It’s the bridge that connects aspirations of property ownership with the necessary capital, making it an indispensable concept in the world of real estate finance.