
The Algorithmic Backbone of Financial Trust
Understanding what constitutes a “decent” credit score fundamentally requires an exploration of the underlying technological frameworks that generate these crucial financial metrics. Far from being arbitrary numbers, credit scores are the output of complex algorithms designed to quantify an individual’s creditworthiness, acting as a predictive tool for lenders. This intricate system, largely invisible to the end-user, represents a significant pillar of modern financial technology and innovation. It processes vast amounts of data to distill a borrower’s financial history into a single, digestible numerical value, streamlining lending decisions and fostering economic stability.
FICO and VantageScore: Proprietary Systems
At the forefront of credit scoring technology are proprietary systems developed by companies like FICO and VantageScore. These models are sophisticated mathematical constructs, continuously refined through data science and statistical analysis. FICO, an acronym for Fair Isaac Corporation, pioneered the standardized credit scoring system, with its various models evolving over decades to incorporate new data points and better predictive capabilities. VantageScore, a more recent innovation developed collaboratively by the three major credit bureaus (Equifax, Experian, and TransUnion), aimed to provide a more consistent and inclusive scoring model, especially for those with thinner credit files.
Both systems leverage advanced algorithms to analyze a consumer’s credit report data. While the exact formulas are closely guarded trade secrets, the general categories of data considered are public knowledge. These include payment history, amounts owed, length of credit history, new credit, and credit mix. The innovation lies not just in the data points themselves, but in how these algorithms weigh and interpret them, identifying patterns and correlations that predict future financial behavior. This predictive analytics engine is the core technological marvel, allowing lenders to assess risk with remarkable efficiency and precision, thereby enabling faster loan approvals and more competitive interest rates based on an individual’s calculated risk profile.
Data Points and Predictive Models
The efficacy of a credit score hinges on the quality and breadth of the data points fed into its predictive models. These data points are meticulously collected and maintained by credit bureaus, forming comprehensive digital financial profiles for billions of individuals. Technologies for data aggregation, secure storage, and real-time updating are critical to the system’s integrity. Every time a consumer applies for credit, makes a payment, or has a debt sent to collections, this information is digitally recorded and processed.
The predictive models employ a blend of statistical methodologies, including regression analysis, machine learning algorithms, and other sophisticated data science techniques. These models are designed to identify the strongest indicators of default risk. For instance, payment history—which accounts for the largest percentage of a score—is analyzed not just for late payments, but also for patterns of on-time payments, frequency of delinquency, and severity of past issues. The “amounts owed” category scrutinizes credit utilization ratios, demonstrating an innovative use of ratios to predict financial stress. A high credit utilization often signals higher risk, even if payments are current.
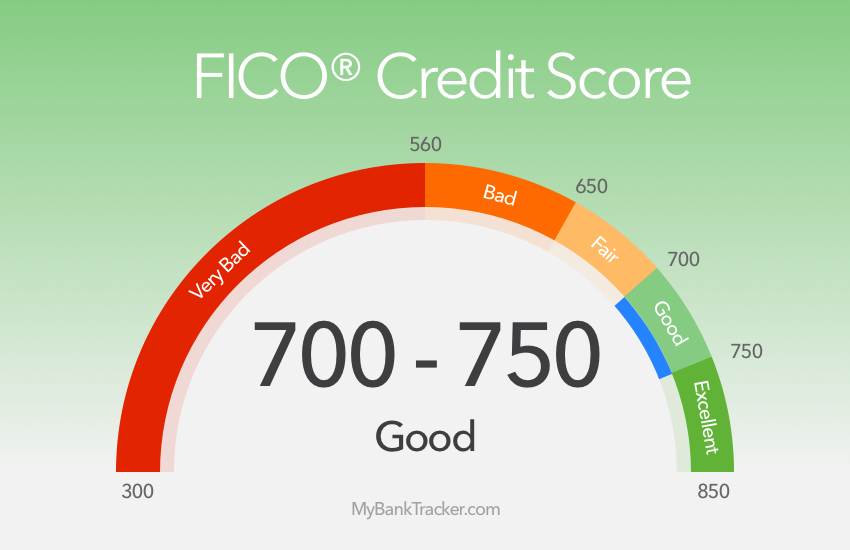
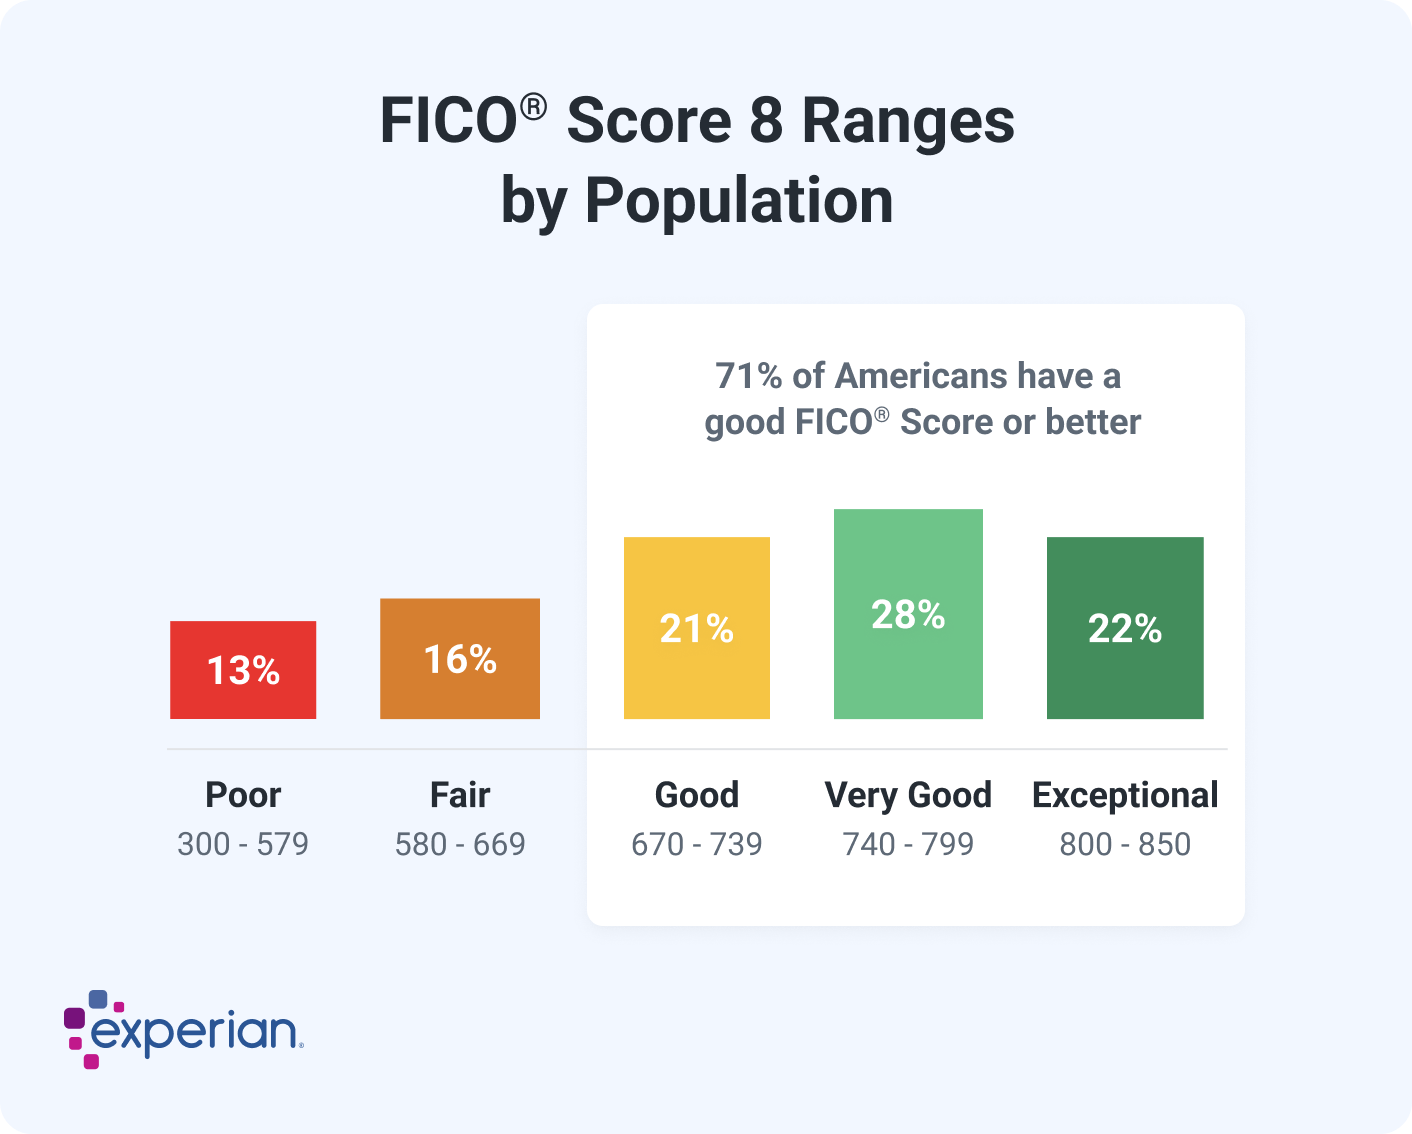
The continuous evolution of these models is a testament to ongoing technological innovation. As financial behaviors shift and new data becomes available, the algorithms are updated to maintain their predictive accuracy. This iterative process, often involving large-scale data testing and validation, ensures that a credit score remains a relevant and reliable indicator of financial trustworthiness in an ever-changing economic landscape. Thus, a “decent” credit score, typically ranging from 670 to 739 for FICO and 661-780 for VantageScore, reflects a strong positive output from these complex, data-driven systems, indicating a low-to-moderate risk for lenders.
Beyond Traditional Metrics: Innovation in Credit Scoring
The landscape of credit scoring is not static; it’s a dynamic field continuously reshaped by technological advancements. While FICO and VantageScore remain dominant, the drive for greater financial inclusion and more granular risk assessment has spurred significant innovation, particularly in the realm of artificial intelligence, machine learning, and the integration of alternative data sources. These innovations aim to provide a more holistic view of an individual’s financial health, moving beyond the limitations of traditional credit reports and potentially redefining what constitutes a “decent” score for a broader segment of the population.
Artificial Intelligence and Machine Learning
Artificial Intelligence (AI) and Machine Learning (ML) are revolutionizing credit scoring by enabling the analysis of more complex datasets and the identification of subtle patterns that traditional statistical models might miss. AI-powered algorithms can process vast quantities of structured and unstructured data much faster and more efficiently than human analysts. This includes not only credit report data but also behavioral patterns, transaction histories, and even psychometric data where legally and ethically permissible.
ML models, especially deep learning networks, can continuously learn and adapt, improving their predictive accuracy over time without explicit programming. This means they can dynamically adjust to new economic conditions, emerging credit behaviors, and evolving fraud patterns. For consumers, this could translate into more personalized credit assessments, where their unique financial habits are better understood, potentially leading to fairer lending decisions. For lenders, it offers enhanced risk management, fraud detection, and the ability to identify creditworthy individuals who might have been overlooked by conventional scoring systems due to thin credit files or past minor blemishes. The innovation here is about creating more intelligent, adaptive, and nuanced scoring mechanisms.
Leveraging Alternative Data Sources
One of the most significant innovations in credit scoring is the integration of alternative data sources. Historically, credit scores have relied almost exclusively on data from credit bureaus. However, a large segment of the population, particularly young adults, immigrants, and those in lower-income brackets, may have “thin” credit files, making it difficult for lenders to assess their creditworthiness. Alternative data aims to bridge this gap.
Technologies are now being developed and deployed to analyze data such as utility bill payments (electricity, water, gas), rent payments, mobile phone payments, bank account transaction data (e.g., consistency of savings, overdraft history), and even employment history or educational attainment. These data points, when integrated into AI/ML models, can provide a more comprehensive picture of an individual’s financial responsibility and stability, even in the absence of traditional credit history.
The technological challenge lies in securely and ethically collecting, standardizing, and integrating these diverse data streams into scoring models. Innovations in data analytics platforms, secure APIs, and consent-based data sharing protocols are crucial for making this possible. By leveraging these alternative data sources, a “decent” credit score could become accessible to millions more, fostering greater financial inclusion and enabling a more equitable lending landscape.
Blockchain and Decentralized Identity
Emerging technologies like blockchain and decentralized identity also hold promise for future innovations in credit scoring. Blockchain, with its immutable and transparent ledger, could potentially offer a new paradigm for managing and sharing credit data. Instead of relying on centralized credit bureaus, individuals could maintain control over their own verified credit history on a blockchain, selectively granting access to lenders. This “self-sovereign identity” approach leverages cryptographic security to ensure data integrity and user privacy.
Decentralized identity systems, often built on blockchain, would allow individuals to aggregate various attestations of their creditworthiness—from bank statements to rental payment histories—into a digital identity they control. This could streamline the credit application process, reduce fraud, and empower consumers with greater control over their financial data. While still in nascent stages for mainstream adoption, the underlying cryptographic and distributed ledger technologies represent a radical innovation that could fundamentally alter how creditworthiness is assessed and verified, potentially offering a more secure, transparent, and user-centric approach to credit scoring in the long term.
The Technological Impact on Accessibility and Fairness
The technological advancements in credit scoring are not just about improving predictive accuracy; they also have profound implications for financial accessibility and fairness. By evolving the way creditworthiness is assessed, technology can either exacerbate existing inequalities or, more hopefully, serve as a powerful tool for promoting inclusion and equity within the financial system.
Expanding Financial Inclusion
One of the most compelling impacts of innovation in credit scoring is its potential to expand financial inclusion. Traditional credit scoring models, while effective for those with established credit histories, often exclude vast populations globally and even within developed economies. This includes individuals with “thin files” (limited credit history), “no files” (no traditional credit history), and those who are new to a country’s financial system.
Technological solutions, particularly those leveraging AI and alternative data, are designed to address this challenge head-on. By incorporating non-traditional data points like utility payments, rental history, and bank transaction data, AI algorithms can identify reliable payment behaviors and financial stability patterns that were previously uncaptured. This allows for the creation of new, predictive credit scores for individuals who would otherwise be deemed “unscoreable” by traditional methods. Companies employing these innovative approaches are helping to bring millions into the formal financial system, providing access to loans, mortgages, and other essential financial products. This expansion of access fundamentally changes what a “decent” credit score means, making it attainable through a broader range of financial behaviors.
Mitigating Bias in Algorithms
While AI and machine learning offer significant advantages, their deployment in credit scoring also presents challenges, particularly concerning algorithmic bias. If the training data for these models reflects existing societal biases or historical discrimination, the algorithms can inadvertently perpetuate or even amplify these biases, leading to unfair outcomes for certain demographic groups. This is a critical area where technological innovation is focused on ethical AI development.
Research and development are underway to create explainable AI (XAI) models that can transparently demonstrate how they arrive at a credit decision, rather than operating as opaque “black boxes.” Furthermore, techniques like debiasing algorithms are being developed to identify and reduce discriminatory patterns within datasets and models. These include fairness metrics that measure disparate impact across different groups and methods to ensure equitable predictive performance. The goal is to build AI systems that are not only accurate but also fair and transparent, ensuring that the technological power of credit scoring is used responsibly. The pursuit of a truly “decent” credit score thus involves not just predictive power, but also the ethical imperative of mitigating unintended biases.
Maintaining a Robust Digital Financial Footprint
In an era defined by advanced financial technology, actively managing one’s digital financial footprint is paramount to achieving and maintaining a decent credit score. The tools and platforms available today, products of ongoing tech and innovation, empower consumers with unprecedented insight and control over their credit health. Understanding and utilizing these resources is key to navigating the complex ecosystem of credit scoring.
Monitoring Tools and Alerts
The proliferation of online credit monitoring tools and alert systems represents a significant technological leap for consumers. Historically, individuals had limited visibility into their credit reports and scores, often only discovering issues when applying for new credit. Today, numerous platforms, many free, leverage sophisticated data aggregation and analysis technologies to provide real-time or near real-time updates.
These tools continuously monitor credit reports from the major bureaus, identifying changes, new accounts opened, inquiries, or potential errors. Automated alerts, delivered via email or mobile app notifications, notify users instantly of any significant activity. This proactive monitoring is invaluable for several reasons: it helps in early detection of identity theft or fraudulent activity, allows for prompt correction of inaccuracies on credit reports (which can negatively impact scores), and provides continuous insight into factors affecting one’s creditworthiness. The technology behind these services involves secure APIs for data access, robust databases for tracking changes, and intelligent algorithms to discern relevant updates from noise. For anyone aiming for or maintaining a decent credit score, these digital sentinels are indispensable.
The Future of Real-Time Scoring
The future of credit scoring is increasingly moving towards more dynamic and real-time assessments, a testament to continuous innovation in data processing and analytics. While traditional scores are updated periodically, typically monthly, the vision is for a more fluid score that reflects an individual’s financial situation with much greater immediacy.
Innovations in open banking APIs and financial data aggregation are paving the way for this future. These technologies allow, with user consent, for the secure sharing of bank transaction data, payment history across various services, and other relevant financial activities directly with lenders or scoring models. This means a lender could potentially gain a real-time snapshot of an applicant’s current income, spending habits, and debt obligations, providing an exceptionally current and accurate risk assessment.
Such real-time scoring could be particularly beneficial for those experiencing rapid improvements in their financial situation, allowing them to benefit from a better score without waiting for monthly reporting cycles. It also opens avenues for more personalized financial products and services, tailored to an individual’s immediate financial standing. While regulatory and privacy considerations are still evolving, the technological capabilities are advancing rapidly, promising a future where a “decent” credit score is not just a static number, but a dynamic reflection of one’s ongoing digital financial health. This continuous innovation ensures that credit scores remain a relevant and powerful tool in the evolving digital economy.