
An appraisal for a house is a crucial step in many real estate transactions, serving as an unbiased, professional opinion of a property’s market value. It’s not merely a guess; it’s a detailed analysis performed by a licensed and certified appraiser who adheres to strict ethical and professional standards, primarily dictated by the Uniform Standards of Professional Appraisal Practice (USPAP) in the United States. The purpose of an appraisal is to provide an informed estimate of what a property would likely sell for on the open market, based on a variety of factors and methodologies. Understanding this process is vital for buyers, sellers, lenders, and even investors.
The Purpose and Importance of a Home Appraisal
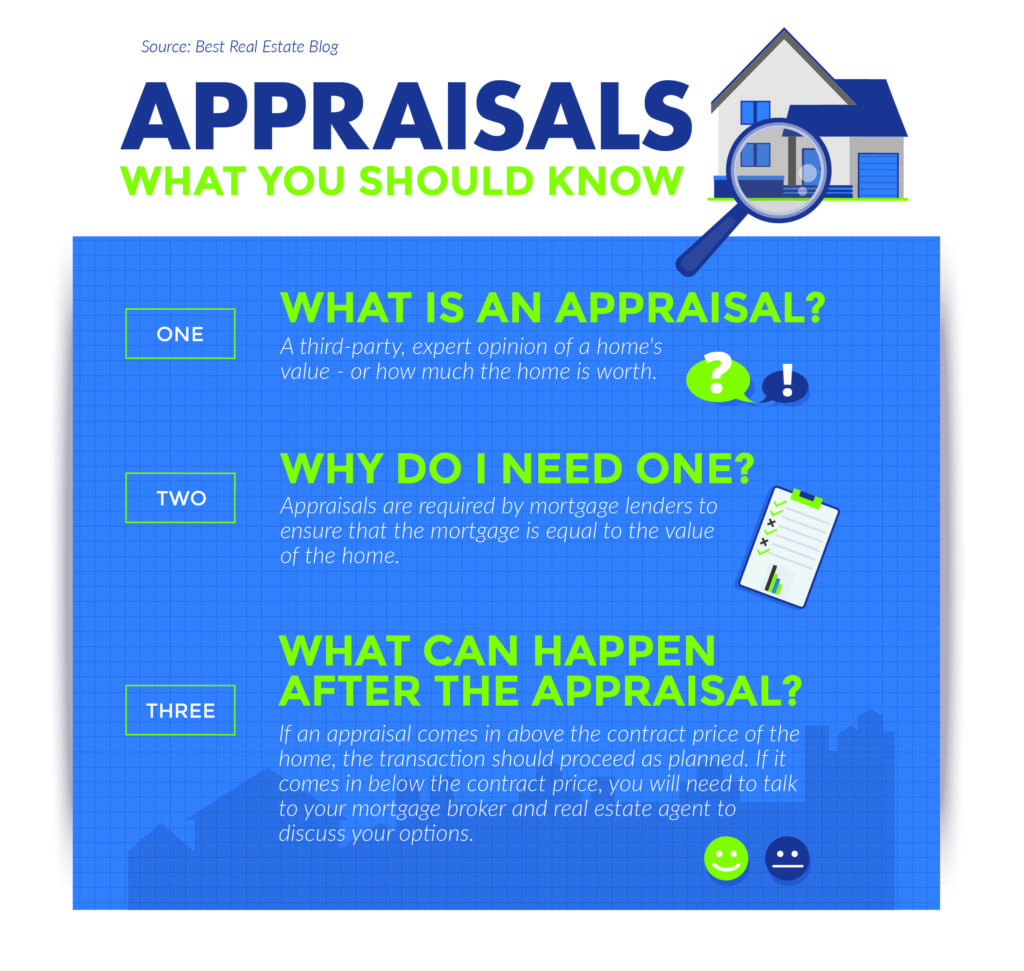
The fundamental purpose of a home appraisal is to establish a property’s fair market value. This value is critical for several key reasons, each impacting different stakeholders in the real estate ecosystem.
Lender Requirements
For most mortgage lenders, an appraisal is a non-negotiable requirement before approving a home loan. The loan amount is directly tied to the property’s value. Lenders use the appraisal to ensure that the amount they are lending is not greater than the value of the property being used as collateral. If the appraised value comes in lower than the agreed-upon purchase price, the lender may refuse to fund the loan for the full amount, potentially jeopardizing the sale. This protects the lender from losing money if they have to foreclose on the property.
Buyer Protection
For buyers, an appraisal acts as a vital layer of protection. It provides an independent verification of the property’s worth, preventing buyers from overpaying for a home. If the appraisal reveals a value significantly lower than the offer price, the buyer has grounds to renegotiate the sale price, request the seller make repairs, or even withdraw from the contract (if the contract includes an appraisal contingency). This contingency clause is a standard safeguard that allows buyers to walk away from a deal if the appraisal doesn’t meet a certain threshold.
Seller Confidence
Sellers also benefit from an appraisal, though often indirectly. While they might be aiming for the highest possible price, an appraisal provides a realistic benchmark. It can help sellers price their home competitively and avoid the frustration of their property lingering on the market if it’s overpriced. In some cases, a seller might even order a pre-listing appraisal to proactively address potential issues and have a clear understanding of their home’s value before putting it on the market.
Other Uses
Beyond purchase transactions, appraisals are essential for:
- Refinancing: When homeowners seek to refinance their existing mortgage, a new appraisal is typically required to determine the current market value of the property, which impacts the loan-to-value ratio.
- Home Equity Loans and Lines of Credit (HELOCs): Lenders assess a home’s value through an appraisal to determine how much equity a homeowner can borrow against.
- Estate Settlement: Appraisals are needed for probate and estate settlement to determine the value of real property for distribution among heirs.
- Tax Assessment Appeals: If a property owner believes their property taxes are too high, an independent appraisal can provide evidence to support an appeal.
- Divorce Proceedings: In divorce settlements, appraisals help determine the fair market value of a shared marital home.
The Home Appraisal Process
The process of a home appraisal is methodical and involves several distinct stages. The appraiser’s goal is to produce a comprehensive and well-supported valuation.
Scheduling and Access
Once a property is slated for appraisal, typically initiated by a lender or a buyer/seller, an appraisal management company (AMC) or directly by the lender will assign a licensed appraiser. The appraiser will then contact the homeowner or their agent to schedule a convenient time for the inspection. During the inspection, the appraiser needs full access to the interior and exterior of the property, including all rooms, the basement, attic, garage, and any outbuildings. They will take detailed notes, measurements, and photographs.
Property Inspection and Data Collection
The appraiser’s site visit is a critical component. They meticulously examine the property’s condition, size, features, and overall quality. This includes:
- Dimensions and Layout: Measuring the square footage of the home and noting the number of bedrooms, bathrooms, and general floor plan.
- Condition: Assessing the physical condition of the structure, including the roof, foundation, walls, plumbing, electrical systems, and HVAC. Signs of wear and tear, necessary repairs, or recent upgrades are all noted.
- Features and Amenities: Documenting specific features like updated kitchens and bathrooms, fireplaces, custom cabinetry, landscaping, decks, patios, swimming pools, and energy-efficient upgrades.
- Quality of Construction: Evaluating the materials used, the craftsmanship, and the overall build quality.
- Site Characteristics: Observing the lot size, topography, views, and any potential issues such as drainage problems or proximity to nuisances.
Photographs are taken to document the condition and features of the property, as well as its neighborhood context.
Developing the Value Opinion: The Sales Comparison Approach
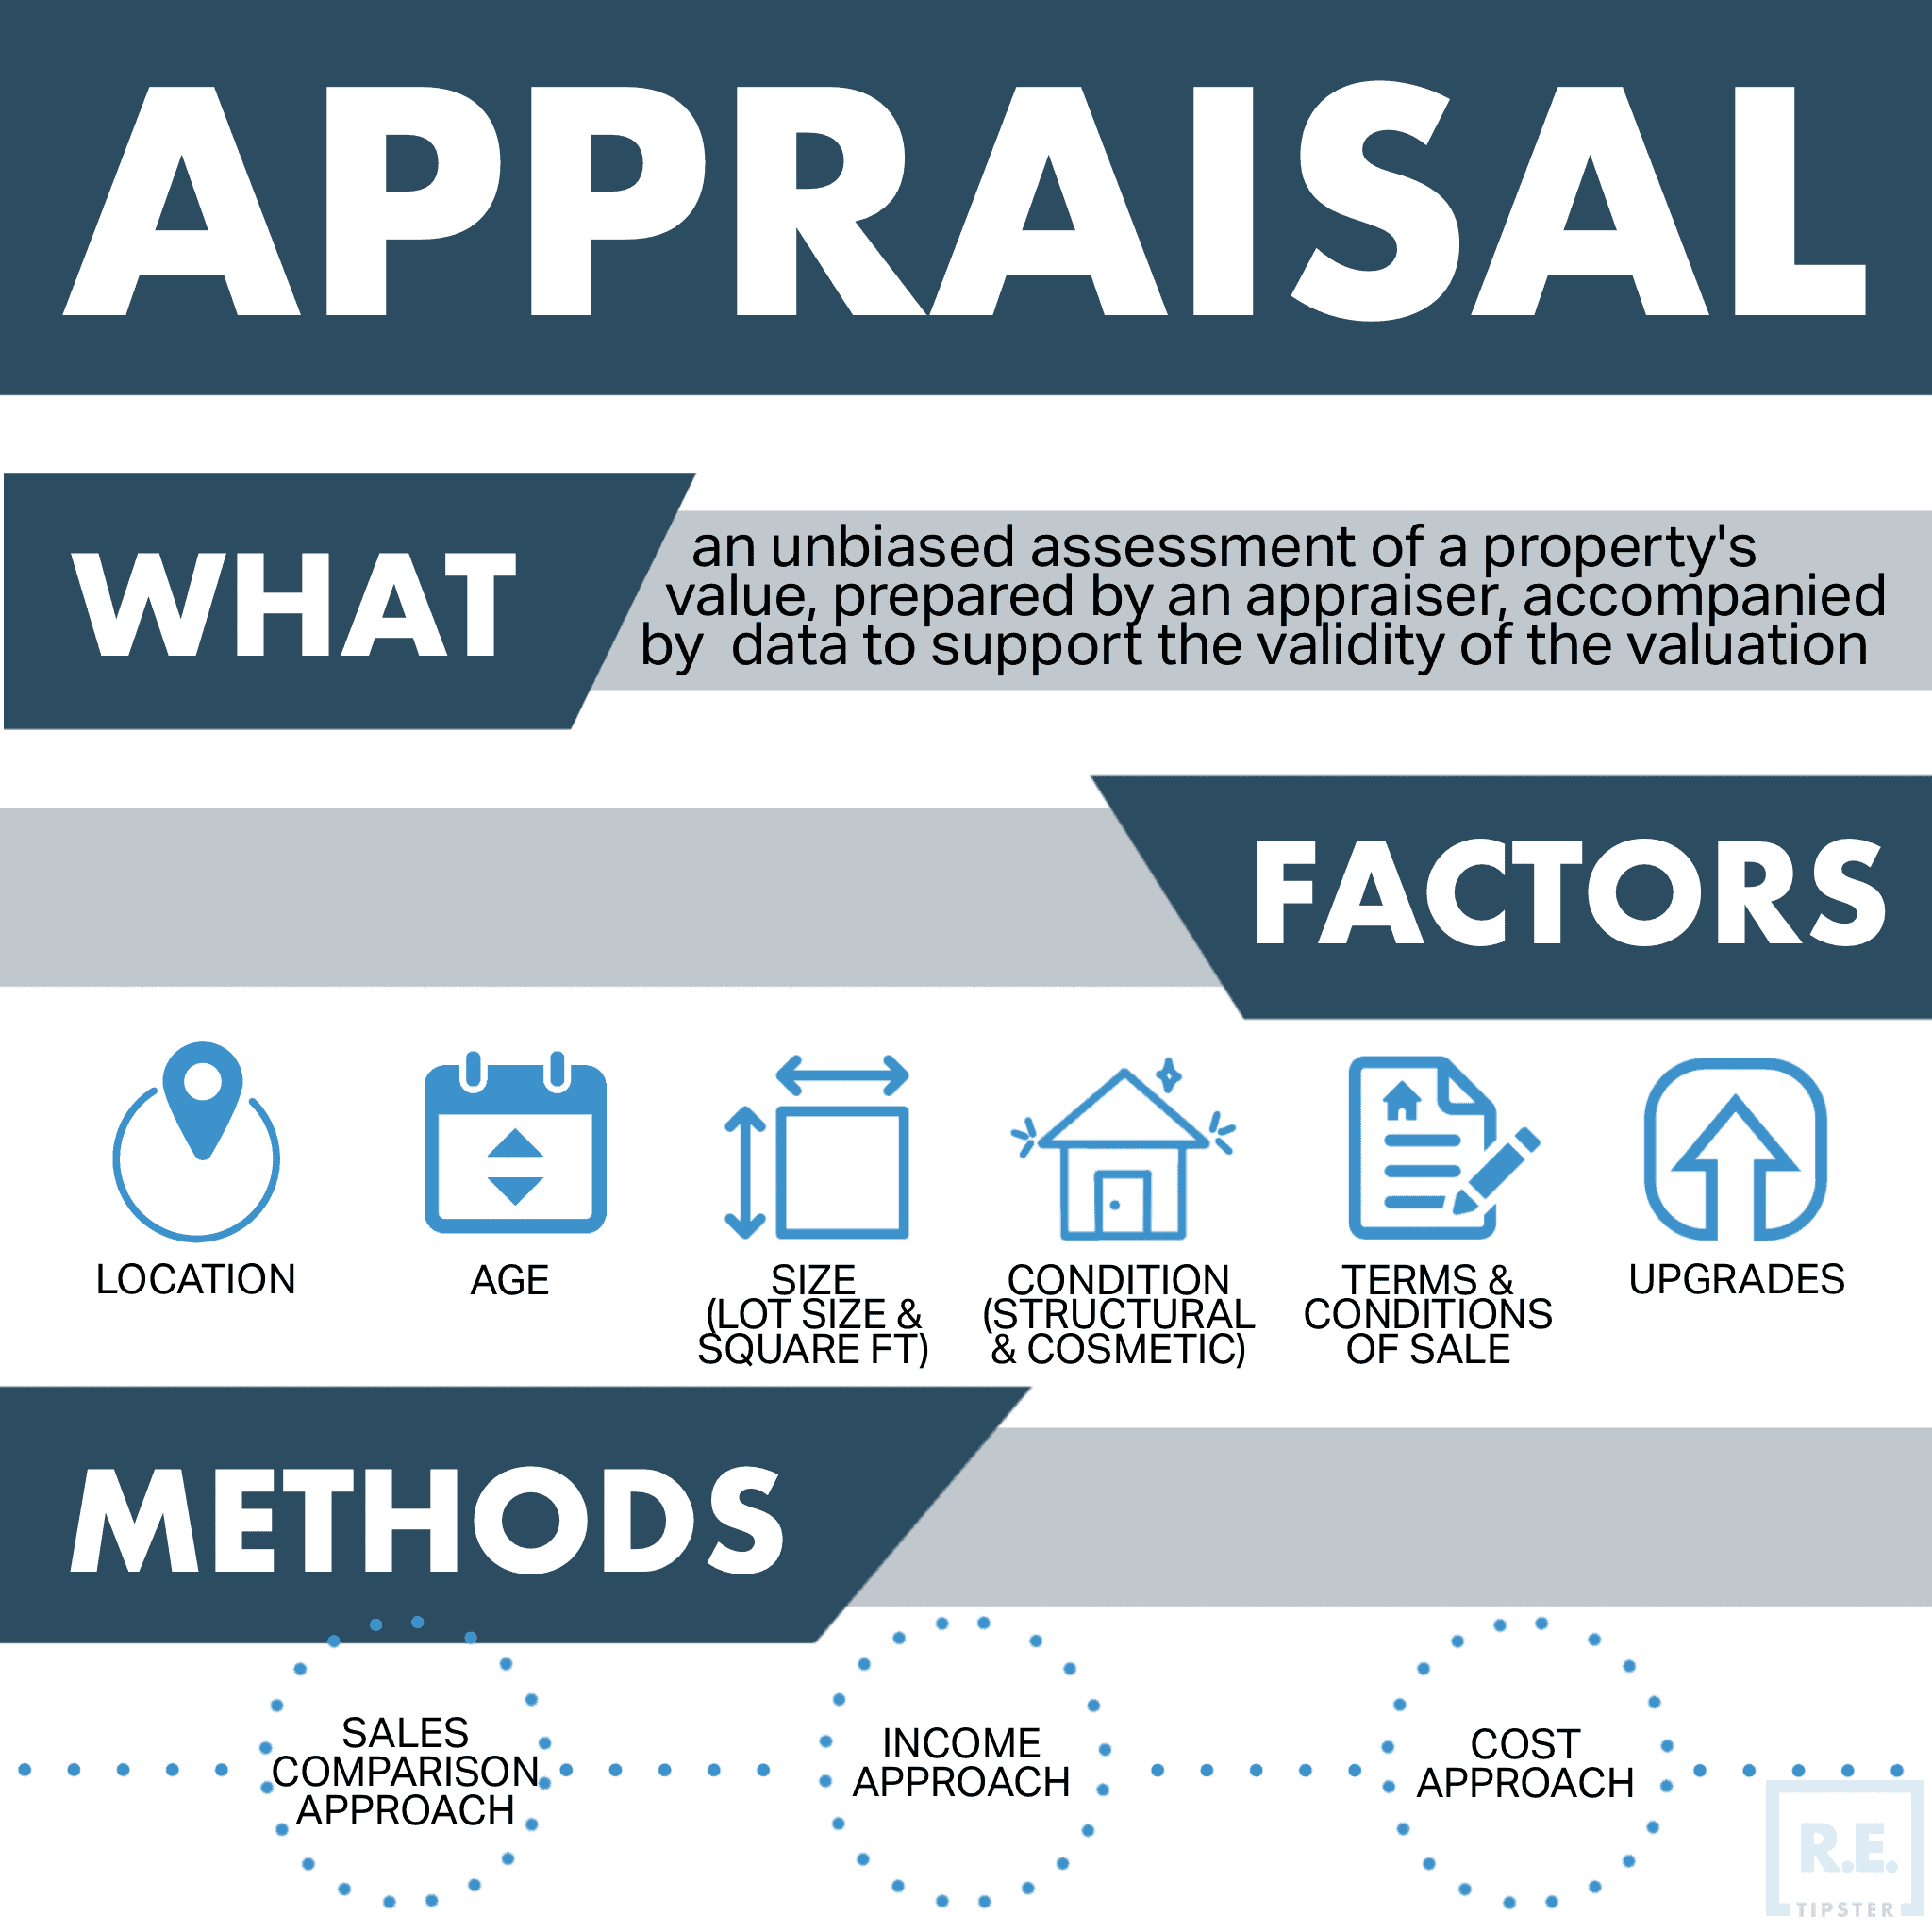
The most common and primary method used in residential appraisals is the Sales Comparison Approach. This method is based on the principle of substitution: a buyer will not pay more for a property than they would for another property that is equally desirable.
The appraiser identifies recently sold properties (comparable sales or “comps”) in the same or a very similar neighborhood that share key characteristics with the subject property. The appraiser then makes adjustments to the sales prices of these comps to account for differences between them and the subject property.
- Finding Comparables: The appraiser looks for properties that have sold within the last 3-6 months, are geographically close, and are similar in size, age, style, and features.
- Making Adjustments: This is where the appraiser’s expertise truly shines. If a comp has one more bedroom than the subject property, the appraiser will subtract the value of that bedroom from the comp’s sale price. Conversely, if a comp has a newer roof, the appraiser will add the value of a new roof to the subject property’s value if its roof is older. Adjustments are made for:
- Date of Sale: Properties sold more recently are generally more relevant.
- Location: Adjustments are made for differences in desirability of the immediate area.
- Physical Characteristics: This includes size, number of bedrooms/bathrooms, age, architectural style, lot size, garage size, and condition.
- Amenities: Features like pools, updated kitchens, fireplaces, and landscaping are considered.
- Financing Terms: Unusual financing for a comp might warrant an adjustment.

After making these adjustments, the appraiser arrives at an adjusted sale price for each comp. These adjusted prices are then analyzed, and the appraiser forms a conclusion about the most probable market value of the subject property.
Other Valuation Methods
While the Sales Comparison Approach is dominant, appraisers may also consider other methods, especially for unique properties or as supporting data:
- Cost Approach: This method estimates the cost to replace the property’s improvements (building) minus depreciation, plus the value of the land. It’s often used for newer construction or special-purpose properties where comparable sales are scarce.
- Replacement Cost New: The cost to build an exact replica of the structure using current materials and standards.
- Depreciation: Accounting for physical deterioration, functional obsolescence (outdated design), and external obsolescence (negative external factors).
- Land Value: The value of the land as if it were vacant.
- Income Approach: This method is primarily used for investment properties (rentals). It estimates the property’s value based on its potential to generate income.
- Gross Rent Multiplier (GRM): A quick estimation tool.
- Capitalization Rate (Cap Rate): A more sophisticated method considering net operating income.
For a typical single-family home, the Sales Comparison Approach will carry the most weight in the final valuation.
The Appraisal Report
The culmination of the appraisal process is the appraisal report. This is a formal document that details the appraiser’s findings, analysis, and final opinion of value. The report’s format can vary depending on the intended use (e.g., lender’s form, individual client report), but it generally includes:
Key Components of an Appraisal Report
- Identification of the Property: Full address, legal description, and property details.
- Purpose of the Appraisal: Stating the reason for the appraisal (e.g., financing, sale).
- Definition of Market Value: The standard definition of market value as understood in the jurisdiction.
- Appraiser’s Qualifications: Information about the appraiser’s license and experience.
- Property Inspection Details: Notes on the condition, features, and any visible defects.
- Neighborhood Analysis: Description of the local market, including trends, amenities, and demographics.
- Sales Comparison Approach: Detailed breakdown of the comparable sales used, including their addresses, sale prices, dates, and the adjustments made.
- Supporting Data: Inclusion of photographs of the subject property, comparables, and the relevant neighborhood.
- Cost and Income Approach (if used): Summaries of these methodologies and their findings.
- Final Opinion of Value: The appraiser’s concluding estimate of the property’s market value, presented with a specific dollar amount.
- Certifications and Signatures: Appraiser’s signature and certification.
Understanding the Appraisal Report’s Limitations
It’s important to remember that an appraisal is an opinion of value at a specific point in time. It is not a guarantee of value. Several factors can influence the final value:
- Appraiser’s Subjectivity: While appraisers strive for objectivity, some level of subjective judgment is involved in making adjustments to comparables.
- Market Fluctuations: Real estate markets are dynamic. The value can change even shortly after an appraisal is completed.
- Undisclosed Defects: Appraisers are trained to identify visible issues, but they are not home inspectors. Hidden problems like foundation cracks not visible from the surface or issues within walls would not be detected.
- Data Availability: The quality and availability of comparable sales data can impact the accuracy of the appraisal.
Common Issues and When to Question an Appraisal
While appraisals are generally reliable, issues can arise. Understanding these can empower homeowners and buyers.
Low Appraisals
Perhaps the most common concern is a low appraisal – one that comes in below the purchase price or the lender’s expectations. This can happen for various reasons:
- Poor Comparables: The appraiser may have used outdated or less relevant comparable sales.
- Market Downturn: The market may have softened since the contract was signed.
- Property Condition: Significant issues with the property’s condition that the appraiser identified could lead to a lower valuation.
- Appraiser Error: Mistakes in measurement, calculation, or adjustment can occur.
What to Do About a Low Appraisal
If a buyer faces a low appraisal that jeopardizes their loan:
- Review the Report: Carefully examine the appraisal report. Are the comparables truly comparable? Are the adjustments logical?
- Discuss with the Lender: Talk to the loan officer about the situation and explore options.
- Request a Re-Appraisal: In some cases, the lender might agree to a re-appraisal, especially if new comparable sales have become available or if a clear error is identified. This often involves paying for a second appraisal, which may be done by a different appraiser.
- Negotiate with the Seller: The buyer can attempt to renegotiate the purchase price with the seller. If the seller agrees, the sale can proceed.
- Pay the Difference: The buyer could choose to cover the difference between the appraised value and the purchase price with their own funds, provided they have the cash and the lender allows it.
- Walk Away: If none of the above are feasible and the appraisal contingency is in place, the buyer may choose to withdraw from the contract and get their earnest money deposit back.
For sellers, a low appraisal might mean revisiting their pricing strategy or considering if they can meet the buyer’s renegotiation demands.
Disputing an Appraisal
While direct “disputes” are not typically how the process works, one can request a review or a new appraisal by presenting new information or evidence of significant errors. This is usually handled through the lender. The appraiser is obligated to provide an unbiased opinion based on the data available.
Conclusion
A home appraisal is a fundamental pillar of the real estate transaction, providing an objective assessment of a property’s value. It serves to protect all parties involved – lenders by securing their investment, buyers by preventing overpayment, and sellers by establishing a realistic market price. The process is detailed, relying on thorough inspection, diligent data collection, and sophisticated analytical methods, primarily the Sales Comparison Approach. While not infallible, the appraisal process, guided by professional standards and conducted by licensed experts, offers a critical insight into the true worth of a home. Understanding its purpose, process, and potential outcomes is essential for anyone navigating the complexities of buying, selling, or financing real estate.