
The world of personal finance and tax preparation can often feel like navigating a dense fog, filled with jargon and complex rules. For individuals seeking to understand their tax obligations and maximize their financial advantages, a foundational concept is the standard deduction. This article will delve into the intricacies of the standard deduction specifically for single individuals, clarifying its purpose, how it’s determined, and its implications for tax planning.
Understanding the Standard Deduction
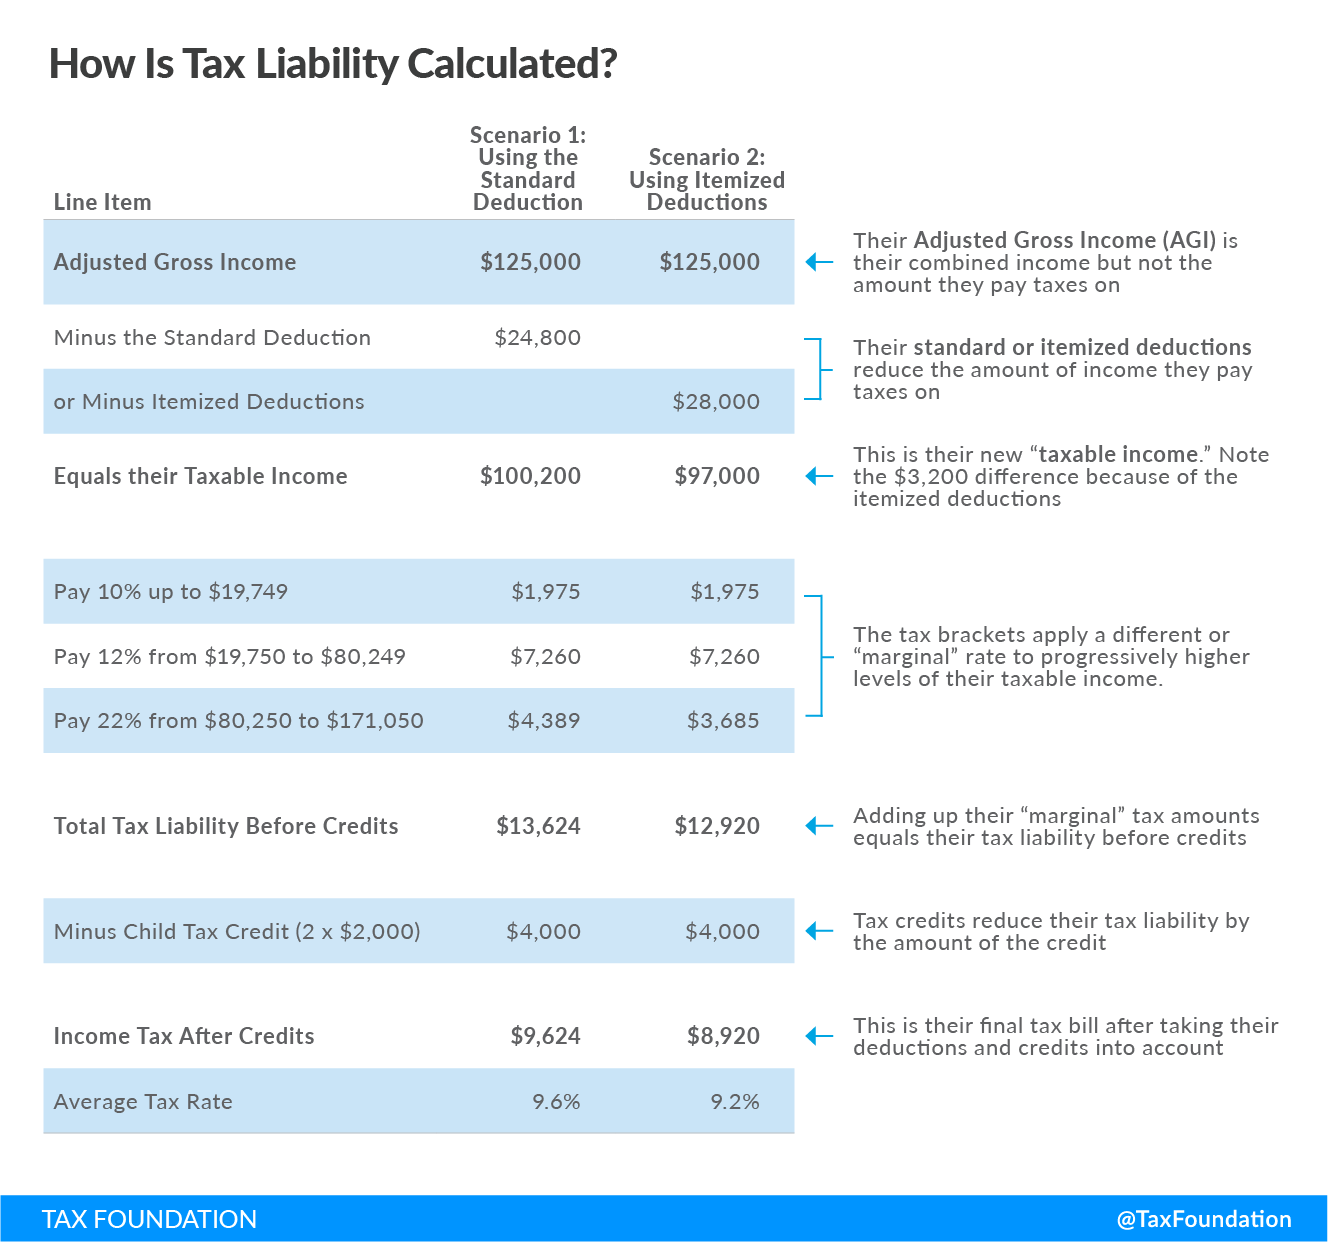
At its core, the standard deduction is a fixed dollar amount that reduces the amount of income subject to federal income tax. It’s an alternative to itemizing deductions, which involves listing out specific deductible expenses such as mortgage interest, state and local taxes, and charitable contributions. The U.S. tax system allows taxpayers to choose whichever method—standard deduction or itemized deductions—results in a lower taxable income, thereby reducing their tax liability.
The primary benefit of the standard deduction is its simplicity. For many taxpayers, especially those with straightforward financial situations, it eliminates the need to meticulously track and document every deductible expense. This streamlined approach saves time and reduces the potential for errors in tax filing. Furthermore, the standard deduction is adjusted annually for inflation, ensuring that its value keeps pace with changes in the cost of living and preventing taxpayers from being pushed into higher tax brackets solely due to inflationary increases in their income.
The Purpose and Mechanics of the Standard Deduction
The standard deduction serves a critical role in the progressive income tax system. By providing a baseline reduction in taxable income, it effectively shields a portion of an individual’s earnings from taxation. This is particularly beneficial for lower and middle-income earners, as it can significantly reduce or even eliminate their tax burden. For instance, if a single person earns $40,000 and has a standard deduction of $13,850 (the 2023 amount), their taxable income becomes $26,150. The tax is then calculated based on this lower amount, rather than the full $40,000.
The mechanics of claiming the standard deduction are straightforward. When filing federal income tax returns (Form 1040), individuals will encounter a section asking whether they choose to itemize or take the standard deduction. For most single filers, the standard deduction will likely be the more advantageous option unless their itemized deductions exceed the standard amount. The Internal Revenue Service (IRS) sets the standard deduction amounts annually, which are influenced by factors such as inflation.
Standard Deduction vs. Itemized Deductions
The choice between taking the standard deduction or itemizing deductions is a crucial decision for every taxpayer. The decision hinges on which method yields a lower taxable income.
When to Itemize
Itemizing deductions becomes beneficial when the sum of an individual’s deductible expenses exceeds the standard deduction amount for their filing status. Common itemized deductions include:
- Medical and Dental Expenses: Expenses that exceed 7.5% of Adjusted Gross Income (AGI).
- State and Local Taxes (SALT): This category includes state and local income taxes or general sales taxes, and property taxes. For federal tax purposes, the SALT deduction is capped at $10,000 per household.
- Home Mortgage Interest: Interest paid on a mortgage for a primary residence and a second home, subject to certain limits on the loan amount.
- Charitable Contributions: Donations made to qualified charitable organizations.
- Other Miscellaneous Deductions: These can include things like unreimbursed employee expenses (though many were eliminated by the Tax Cuts and Jobs Act of 2017), casualty and theft losses (limited to federally declared disaster areas), and gambling losses up to the amount of winnings.
When to Take the Standard Deduction
For many single individuals, the standard deduction proves to be the more practical and beneficial choice due to several factors:
- Lower Overall Expenses: If their deductible expenses are relatively low, they may not meet or exceed the standard deduction amount.
- Simplicity and Time Savings: The effort required to track and document all potential itemized deductions can be substantial. For those with less complex financial lives, the standard deduction offers a quick and easy way to reduce taxable income.
- Changes in Tax Law: The Tax Cuts and Jobs Act of 2017 significantly increased the standard deduction amounts. This change meant that fewer taxpayers found it beneficial to itemize, making the standard deduction the preferred option for a larger segment of the population.
The Standard Deduction for Single Individuals: A Deep Dive
The standard deduction amount varies based on a taxpayer’s filing status. For single individuals, this means the deduction is specifically tailored to their circumstances as an unmarried taxpayer who is not the head of a household or a qualifying widow(er). Understanding the specific amounts and how they are applied is key to accurate tax preparation.
Current Standard Deduction Amounts (and Historical Context)
The standard deduction amounts are updated each year by the IRS to reflect inflation. For the tax year 2023 (filed in 2024), the standard deduction for single individuals is $13,850. For the tax year 2024 (filed in 2025), this amount is set to increase to $14,600.
To provide a broader perspective, let’s look at some historical figures:
- Tax Year 2022: $12,950 for single filers.
- Tax Year 2021: $12,550 for single filers.
- Tax Year 2020: $12,400 for single filers.
- Tax Year 2019: $12,200 for single filers.
- Tax Year 2018: $12,000 for single filers.
The significant jump from 2017 ($6,350) to 2018 ($12,000) was a direct result of the Tax Cuts and Jobs Act (TCJA) of 2017, which nearly doubled the standard deduction for most filing statuses. This was a major tax reform that simplified the tax code for many Americans.
Factors Affecting the Standard Deduction for Single Filers

While the standard deduction amount is set by the IRS for each tax year and filing status, there are specific circumstances that can alter or eliminate it.
Additional Standard Deduction for Age and Blindness
Single individuals who are age 65 or older, or who are blind, are entitled to an additional standard deduction amount. This is designed to provide further tax relief to those who may have higher living expenses due to age or disability.
- Age 65 or Older: If a single individual is 65 or older and not married, they can claim an additional standard deduction amount. For the tax year 2023, this additional amount is $1,850.
- Blindness: If a single individual is blind, they can also claim an additional standard deduction amount. For the tax year 2023, this additional amount is $1,500.
These additional amounts are applied on top of the base standard deduction. For example, a single individual who is 67 years old and blind would receive the base standard deduction for a single filer, plus the additional amount for being age 65 or older, and the additional amount for being blind.
Dependency Status and Other Filing Statuses
It’s crucial to understand that the standard deduction amounts are tied to filing status. A single person who is claimed as a dependent on someone else’s tax return may have a different standard deduction limitation. In such cases, their standard deduction cannot exceed the greater of $1,150 (for tax year 2023) or their earned income plus $400, but it cannot exceed the regular standard deduction for their filing status.
Furthermore, individuals who file as Head of Household or Qualifying Widow(er) have different, generally higher, standard deduction amounts than those who file as single. This is because these filing statuses often reflect situations with greater financial responsibility, such as supporting a child or a dependent.
Claiming the Standard Deduction on Your Tax Return
Claiming the standard deduction is a straightforward process when filing your federal income tax return using Form 1040.
Step-by-Step Process
- Determine Your Filing Status: First, confirm your filing status. For this discussion, we assume you are filing as “Single.”
- Calculate Your Total Income: Sum up all your income sources for the tax year.
- Determine Your Eligibility for Itemizing: Review your potential itemized deductions (medical expenses, SALT, mortgage interest, charitable contributions, etc.). Sum them up.
- Compare Standard Deduction to Itemized Deductions: Compare the sum of your itemized deductions to the standard deduction amount for a single filer for that tax year.
- Choose the Larger Amount: If your itemized deductions are greater than the standard deduction, you will itemize. If the standard deduction is greater, or if you choose not to itemize for simplicity, you will claim the standard deduction.
- Report on Form 1040: On Form 1040, there is a section dedicated to deductions. You will indicate whether you are taking the standard deduction or itemizing. If you take the standard deduction, you will simply enter the applicable amount. If you itemize, you will attach Schedule A (Form 1040) to detail your deductions.
Strategic Implications of the Standard Deduction
While the standard deduction offers simplicity, understanding its role can inform broader financial and tax planning strategies. It’s not just a number on a form; it’s a tool that can impact your overall financial health.
Impact on Taxable Income and Tax Liability
As mentioned, the primary function of the standard deduction is to reduce your taxable income. The lower your taxable income, the less tax you will owe, assuming you are in a tax bracket that requires you to pay taxes. The progressive nature of the U.S. income tax system means that tax rates increase as income rises. By reducing your taxable income, the standard deduction effectively lowers the amount of income that is subject to these higher rates.
For instance, imagine a single individual with $60,000 in taxable income. If they fall into a 22% tax bracket on some of that income, they will pay a significant portion of their taxes on that portion. However, if that same individual has $13,850 in standard deductions, their taxable income drops to $46,150. The tax calculation then applies to this lower figure, resulting in a lower overall tax bill.
The Standard Deduction and Tax Planning
Even though the standard deduction is designed for simplicity, it plays a role in tax planning.
- Bunching Deductions: For individuals who are close to the threshold where itemizing becomes beneficial, “bunching” deductions can be a strategy. This involves strategically timing deductible expenses to occur in a single tax year to exceed the standard deduction amount. For example, if you typically make charitable donations throughout the year, you might consider making a larger donation in a year where you anticipate higher medical expenses or other itemizable costs. This can help you “have a year where you itemize” and then revert to the standard deduction in subsequent years, potentially lowering your tax liability over a two-year period.
- Evaluating Investment Strategies: Certain investments can generate deductions or tax credits that might make itemizing more appealing. For example, investments in tax-deferred accounts or those that offer tax credits can influence the overall tax picture.
- Long-Term Financial Goals: Understanding how the standard deduction interacts with other aspects of your finances, such as retirement planning or homeownership, is important. For example, the decision to own a home often involves considering mortgage interest as a potential itemized deduction.
When to Re-evaluate Your Decision
The decision to take the standard deduction or itemize is not set in stone year after year. Several life events can change which approach is more advantageous:
- Major Medical Expenses: A significant illness or injury can lead to substantial medical bills that exceed the 7.5% of AGI threshold, making itemizing worthwhile.
- Homeownership: Purchasing a home and paying mortgage interest, along with property taxes, can significantly increase itemized deductions.
- Significant Charitable Gifts: Making a large donation to a qualified charity, especially one that provides a tax deduction, can push your itemized deductions over the standard deduction amount.
- Changes in Tax Law: As seen with the TCJA, legislative changes can dramatically alter the landscape of deductions and make the standard deduction more attractive for a larger number of taxpayers.
- Marriage or Divorce: Changes in marital status directly affect filing status and can therefore influence the standard deduction amount and the potential benefits of itemizing.
In conclusion, the standard deduction for a single person is a fundamental component of the U.S. tax system, offering a simplified and often beneficial way to reduce taxable income. While its purpose is to streamline tax filing, understanding its nuances, the potential benefits of itemizing, and how life events can alter your optimal strategy is essential for effective personal finance management. By staying informed and periodically re-evaluating your tax situation, single individuals can ensure they are leveraging all available tax advantages.