
Understanding qualified distributions from a Roth IRA is crucial for maximizing the tax-advantaged growth and withdrawal benefits of this popular retirement savings vehicle. Unlike traditional IRAs, Roth IRAs offer tax-free withdrawals of contributions and earnings in retirement, provided certain conditions are met. These conditions are centered around the concept of a “qualified distribution,” a term that carries significant weight for any Roth IRA holder planning for their financial future. Navigating these rules can seem complex, but a clear understanding empowers you to make informed decisions about your retirement savings, ensuring that your hard-earned money is accessible when you need it, without incurring unexpected tax liabilities.

The primary advantage of a Roth IRA lies in its tax treatment: contributions are made with after-tax dollars, meaning you don’t get an upfront tax deduction. However, in exchange for this, qualified withdrawals in retirement are completely tax-free. This can be a substantial benefit, especially if you anticipate being in a higher tax bracket in retirement than you are during your working years. The IRS defines specific criteria that must be met for a distribution from your Roth IRA to be considered “qualified.” Failing to meet these criteria can result in some or all of your withdrawals being subject to income tax and potentially a 10% early withdrawal penalty. Therefore, a thorough grasp of these requirements is not merely a matter of financial prudence; it’s a fundamental aspect of Roth IRA management.
The Two Pillars of Qualified Distributions
For a distribution from a Roth IRA to be considered qualified, it must satisfy two distinct yet interconnected requirements: the five-year rule and the age or qualifying event rule. Both must be met simultaneously. Missing even one of these conditions means your distribution, or at least the earnings portion of it, may be subject to taxation and penalties.
The Five-Year Rule
The five-year rule is a foundational requirement for all Roth IRA distributions that include earnings. It dictates that at least five years must have passed since January 1st of the first tax year for which you made your initial contribution to any Roth IRA. It’s important to note that this refers to the first contribution made to any Roth IRA you own, not necessarily the specific account from which you are withdrawing.
Tracking Your Five-Year Period:
The clock on the five-year rule begins on January 1st of the year you make your very first Roth IRA contribution. For example, if you made your first Roth IRA contribution on May 15, 2018, your five-year period began on January 1, 2018. Therefore, the earliest your earnings could be eligible for qualified, tax-free withdrawal is January 1, 2023.
- Multiple Roth IRAs: If you have multiple Roth IRAs, the five-year rule applies to each account based on its individual opening date. However, for the purpose of a qualified distribution, it’s the first Roth IRA you ever funded that establishes the five-year clock for all your Roth IRAs.
- Conversions from Traditional IRAs: If you convert funds from a traditional IRA to a Roth IRA, a separate five-year rule applies to the converted amount. This rule states that the converted amount cannot be withdrawn tax-free or penalty-free for five years from the date of the conversion. This is in addition to the original five-year rule for your Roth IRA. This means that if you convert funds and then later want to withdraw them, you might need to satisfy two separate five-year rules.
The five-year rule is designed to ensure that Roth IRAs are primarily used for long-term retirement savings, rather than short-term savings or investment vehicles. It prevents individuals from making a quick contribution, earning some interest, and then immediately withdrawing it tax-free.
The Age or Qualifying Event Rule
In addition to satisfying the five-year rule, your Roth IRA distribution must also meet one of the following conditions:
- Age 59½: You have reached the age of 59½. This is the most common trigger for qualified distributions, aligning with traditional retirement ages.
- Disability: You become disabled. The IRS defines disability as a condition that prevents you from engaging in any substantial gainful activity due to a medically determinable physical or mental impairment that can be expected to result in death or has lasted or can be expected to last for a continuous period of not less than 12 months.
- Death: The account holder dies. In this case, beneficiaries can typically withdraw the funds without being subject to the 10% early withdrawal penalty. However, income tax may still apply to the earnings if the five-year rule hasn’t been met by the deceased.
- Qualified First-Time Home Purchase: You use the funds for a qualified first-time home purchase. This allows for a withdrawal of up to $10,000 in earnings from the Roth IRA to help purchase a first home. The individual purchasing the home, their spouse, or a child or grandchild must be the first-time buyer. The withdrawal must be used within 60 days of being distributed. The five-year rule must still be satisfied for the earnings portion of this withdrawal to be tax-free.
Understanding “Distribution”:
A distribution is any withdrawal of funds from your Roth IRA. This includes not only cash but also assets you take possession of. The IRS treats contributions and earnings separately when calculating taxes on non-qualified distributions.
Withdrawals of Contributions vs. Earnings
A key aspect of Roth IRA distributions is the distinction between withdrawing your contributions and withdrawing your earnings. This distinction is fundamental to understanding tax implications.
Withdrawing Contributions
One of the most powerful features of a Roth IRA is that you can withdraw your original contributions at any time and for any reason without tax or penalty. This is because you already paid taxes on this money when you contributed it.
- Order of Withdrawal: The IRS presumes that you withdraw your contributions first, then conversions, and finally earnings. This “first-in, first-out” (FIFO) approach benefits the account holder, as it means your earliest contributions are considered to be withdrawn first, making them tax and penalty-free.
- Tracking Contributions: While the IRS has this presumption, it is crucial for you, the account holder, to keep accurate records of your contributions. This is especially important if you have made multiple withdrawals or conversions over the years. Most financial institutions provide statements that detail your contribution history.
This ability to access your contributions freely provides a significant layer of flexibility, making a Roth IRA a more liquid retirement savings option compared to a traditional IRA, particularly in emergency situations before retirement age.
Withdrawing Earnings
Earnings on your Roth IRA investments are where the qualified distribution rules come into play. To withdraw earnings tax-free and penalty-free, you must meet both the five-year rule and one of the qualifying event conditions (age 59½, disability, death, or qualified first-time home purchase).
- Taxable Portion: If you withdraw earnings before meeting both the five-year rule and a qualifying event, those earnings will be subject to ordinary income tax.
- 10% Early Withdrawal Penalty: In addition to income tax, the earnings will also be subject to a 10% early withdrawal penalty unless an exception applies (such as disability, death, or a qualified first-time home purchase).
- Pro-Rata Rule for Conversions: It’s important to remember the separate five-year rule for Roth conversions. If you withdraw converted amounts before five years have passed since the conversion, those converted amounts will be treated as if they were from your original Roth IRA contributions. This means they would be tax- and penalty-free. However, any earnings withdrawn before satisfying both the account’s five-year rule and a qualifying event, and after the five-year period for the conversion, would be subject to tax and penalty.
The distinction between contributions and earnings is critical for strategic Roth IRA planning. Maximizing tax-free growth and ensuring the ability to access earnings without penalty requires adherence to the IRS’s qualified distribution guidelines.
Exceptions to the Rules
While the five-year rule and age/qualifying event criteria are the primary determinants of a qualified distribution, there are certain circumstances where the 10% early withdrawal penalty on earnings may be waived, even if the distribution is not considered fully qualified from a tax perspective. These exceptions allow access to funds for specific life events without the typical penalty, though income tax may still apply to the earnings.
Waiving the 10% Early Withdrawal Penalty
The following situations allow for the withdrawal of earnings without the 10% early withdrawal penalty, provided the five-year rule for the account has been met. If the five-year rule for the account has not been met, then income tax will apply to the earnings, but the penalty will be waived:
- Substantially Equal Periodic Payments (SEPP): Also known as the “72(t) exception” (referencing section 72(t) of the IRS code), this allows you to take a series of substantially equal annual payments from your IRA. These payments must be made at least annually for the longer of five years or until you reach age 59½. There are specific calculations and strict rules that must be followed to set up and maintain SEPPs. Deviating from the rules can trigger the penalty on all prior withdrawals.
- Unreimbursed Medical Expenses: If you pay for qualified unreimbursed medical expenses that exceed 7.5% of your Adjusted Gross Income (AGI) for the year. You can withdraw earnings without penalty up to the amount of these expenses.
- Health Insurance Premiums: While unemployed, you can withdraw earnings without penalty to pay for health insurance premiums. You must have received unemployment compensation for 12 consecutive weeks.
- Higher Education Expenses: Funds can be withdrawn for qualified higher education expenses for yourself, your spouse, children, or grandchildren. This includes tuition, fees, books, supplies, and equipment required for enrollment or attendance at an eligible educational institution. Room and board may also be included under certain circumstances.
- Qualified First-Time Home Purchase: As previously mentioned, up to $10,000 of earnings can be withdrawn penalty-free for a first-time home purchase. This amount is also tax-free if the five-year rule is met.
- Birth or Adoption Expenses: Distributions made within one year of the birth of your child or the placement of a child for adoption are allowed. The maximum withdrawal is $5,000 per child. This applies to the birth or adoption of a child to you, your spouse, or a person for whom you are the legal guardian.
- IRS Levies: If the IRA is subject to a levy by the IRS.
- Qualified Military Reservists: Members of the U.S. Armed Forces Reserve called to active duty.
It is crucial to understand that while these exceptions waive the 10% penalty, they do not necessarily make the earnings tax-free if the five-year rule has not been met. For instance, if you withdraw earnings due to disability, the 10% penalty is waived, but if your five-year clock hasn’t started yet, those earnings will still be subject to ordinary income tax.
Strategic Planning for Qualified Distributions
Understanding the nuances of qualified distributions is not just about avoiding penalties and taxes; it’s about strategically leveraging your Roth IRA for long-term financial security. Planning ahead ensures that your retirement funds are accessible when you need them, in the most tax-efficient manner possible.
When to Consider Taking Distributions
The decision of when to take distributions from your Roth IRA should be based on your individual financial circumstances, retirement goals, and projected tax bracket in retirement.
- Early Retirement: If you plan to retire before age 59½, understanding the implications of non-qualified withdrawals is critical. While you can always withdraw contributions tax-free, accessing earnings will likely trigger taxes and penalties, unless an exception applies. Strategic planning with SEPPs or other penalty-waiving exceptions can be invaluable.
- Income Planning in Retirement: For those in retirement, a Roth IRA can be a powerful tool for managing taxable income. Since qualified distributions are tax-free, they don’t count towards your Adjusted Gross Income (AGI), which can be beneficial for maintaining eligibility for certain tax deductions, credits, or Medicare premiums.
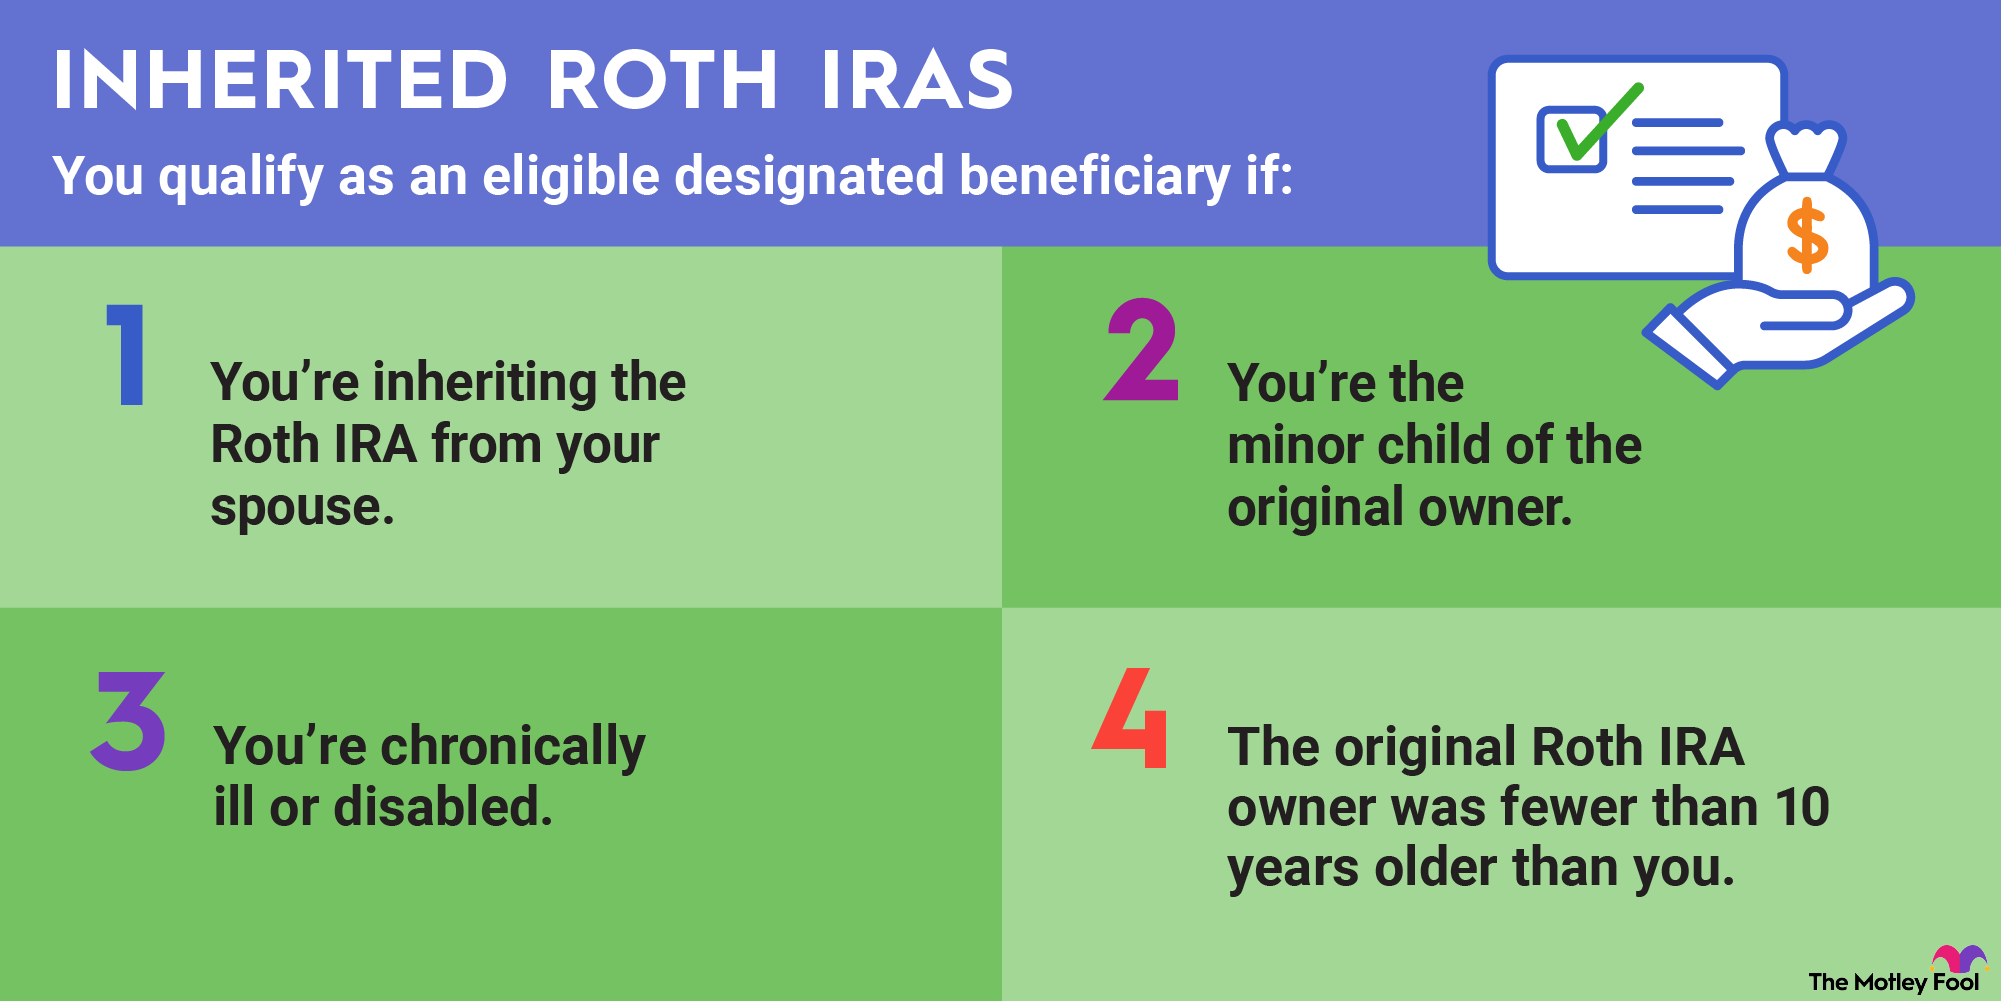
- Estate Planning: Upon death, Roth IRAs can pass to beneficiaries tax-free (provided the five-year rule was met by the original owner or is met by the beneficiary within the required timeframe). This can be a significant inheritance advantage. Beneficiaries generally must take distributions within a specified period, often 10 years, but these distributions are typically tax-free.

Record Keeping and Professional Advice
Meticulous record-keeping is paramount when managing a Roth IRA, especially when it involves multiple contributions, conversions, or withdrawals.
- Contribution Tracking: Maintain records of all contributions, including dates and amounts. This is essential for accurately determining your basis in the Roth IRA.
- Withdrawal Records: Keep detailed records of all withdrawals, noting the date, amount, and whether it was a contribution or earnings withdrawal.
- Conversion Records: If you have made Roth conversions, track the date and amount of each conversion. Remember the separate five-year rule for conversions.
- Consult a Financial Professional: Given the complexities of tax laws and retirement planning, it is highly advisable to consult with a qualified financial advisor or tax professional. They can help you understand your specific situation, navigate the rules, and develop a personalized strategy to ensure your Roth IRA distributions are qualified and meet your financial objectives. They can also help you understand the implications of Roth IRA rules in conjunction with other retirement accounts and income sources.
By diligently adhering to the rules and engaging in thoughtful planning, you can unlock the full potential of your Roth IRA, ensuring it serves as a reliable and tax-advantaged source of income throughout your retirement years.