
The world of retirement savings can often feel like navigating a complex maze. Among the various investment vehicles available, the Roth 401(k) has emerged as a popular and powerful tool for individuals looking to secure their financial future. Unlike its traditional counterpart, the Roth 401(k) offers a distinct advantage in how your contributions and earnings are taxed, potentially leading to significant long-term savings. Understanding the nuances of this retirement plan is crucial for making informed decisions about your nest egg.
Understanding the Core Concept: Tax-Deferred vs. Tax-Free Growth
At its heart, the difference between a traditional 401(k) and a Roth 401(k) boils down to the timing of taxation. Both are employer-sponsored retirement savings plans that allow you to contribute a portion of your income towards retirement. However, the way taxes are applied to these contributions and the subsequent growth differs fundamentally.
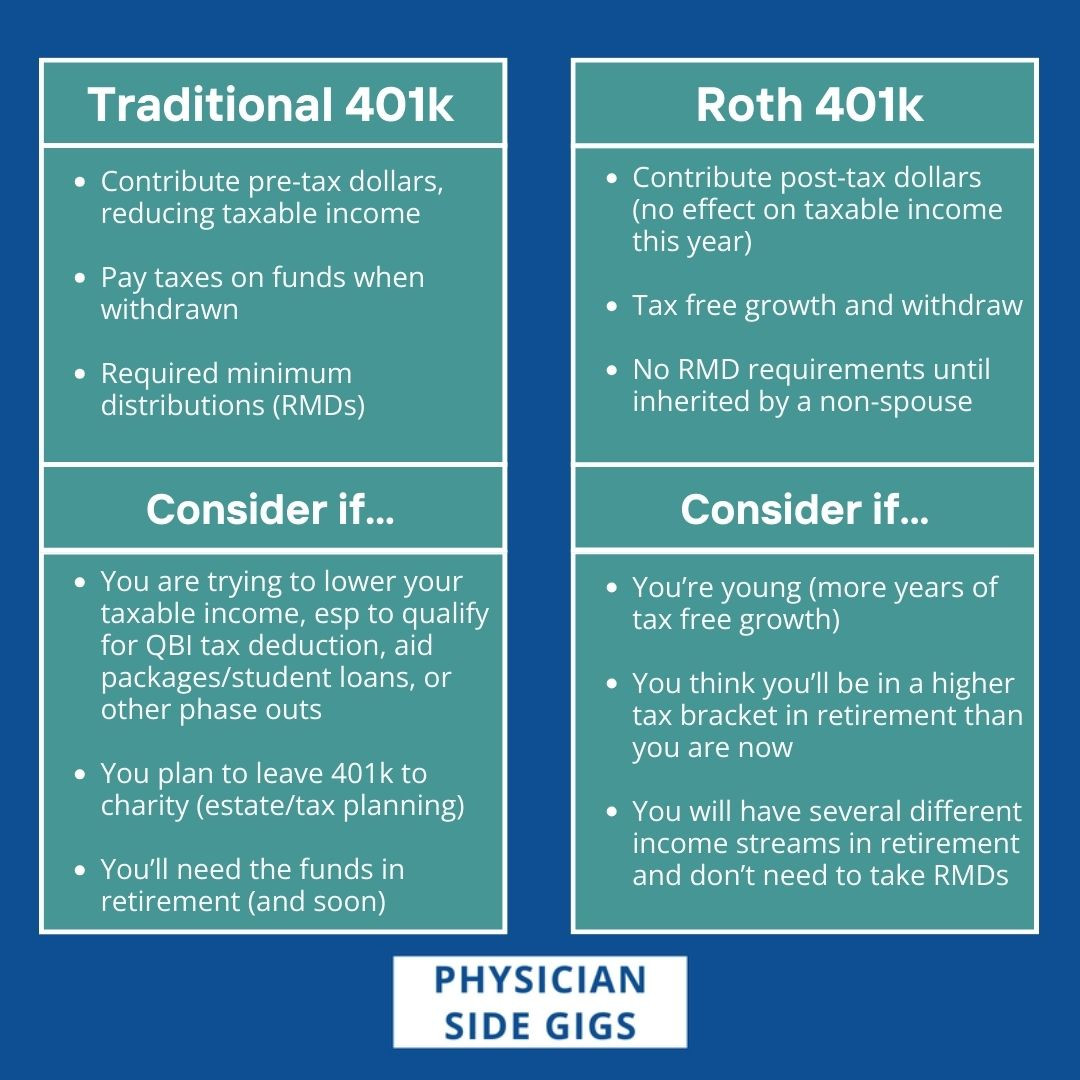
Traditional 401(k): Tax Deductions Now, Taxes Later
In a traditional 401(k), your contributions are made on a pre-tax basis. This means that the money you contribute is deducted from your taxable income in the year you earn it. For instance, if you earn $50,000 and contribute $5,000 to a traditional 401(k), your taxable income for that year is reduced to $45,000. This can lead to immediate tax savings, making it an attractive option for those who anticipate being in a lower tax bracket in retirement or who need to reduce their current tax liability.
The investments within a traditional 401(k) grow on a tax-deferred basis. This means you don’t pay any taxes on the earnings (interest, dividends, capital gains) as they accrue year after year. However, when you withdraw money in retirement, both your contributions and the earnings are taxed as ordinary income. This is often referred to as “paying taxes later.”
Roth 401(k): Taxes Now, Tax-Free Later
The Roth 401(k) operates on an entirely different tax principle. Your contributions to a Roth 401(k) are made with after-tax dollars. This means that the money you contribute does not reduce your current taxable income. If you earn $50,000 and contribute $5,000 to a Roth 401(k), your taxable income remains $50,000 for that year. While this means no immediate tax break, the significant benefit comes in retirement.
The magic of the Roth 401(k) lies in its tax-free withdrawals in retirement. Once you reach age 59½ and have held the account for at least five years, all your qualified withdrawals – including both your contributions and all the earnings generated over the years – are completely tax-free. This “pay taxes now, enjoy tax-free in retirement” approach can be incredibly advantageous, especially if you anticipate being in a higher tax bracket in your later years or if you believe tax rates will generally increase in the future.
Key Features and Benefits of a Roth 401(k)
The Roth 401(k) offers a compelling set of features that make it a cornerstone of many retirement planning strategies. Understanding these benefits can help you determine if it’s the right choice for your financial journey.
Tax-Free Withdrawals in Retirement
This is the undisputed champion benefit of the Roth 401(k). The ability to withdraw all your retirement savings – principal and earnings – without owing a single penny in federal income tax is a powerful incentive. This predictability can simplify retirement budgeting and provide peace of mind, as your income stream will not be subject to the whims of future tax legislation.
Tax Diversification
Having both pre-tax (traditional 401(k), IRAs) and after-tax (Roth 401(k), Roth IRAs) retirement accounts provides valuable tax diversification. In retirement, you can strategically withdraw from different account types to manage your tax liability. If tax rates are high, you can draw from your Roth accounts. If tax rates are low, you might opt for traditional accounts. This flexibility allows you to optimize your after-tax income throughout your retirement years.
No Required Minimum Distributions (RMDs) for the Original Owner
Unlike traditional 401(k)s and traditional IRAs, which are subject to Required Minimum Distributions (RMDs) starting at a certain age (currently 73, rising to 75 in 2033), Roth 401(k)s do not have RMDs for the original owner. This means you are not forced to take withdrawals from your Roth 401(k) if you don’t need the money, allowing it to continue growing tax-free for as long as you live. This can be particularly beneficial for estate planning, as you can pass on the account to your beneficiaries, who will then be subject to RMD rules (though withdrawals for beneficiaries are typically tax-free as well).
It’s important to note that while the original owner doesn’t face RMDs, Roth 401(k)s do have RMDs if they remain in the employer’s plan and are not rolled over. However, a common strategy is to roll over a Roth 401(k) into a Roth IRA upon leaving an employer, thereby eliminating RMDs for the original owner entirely.
Potential for Higher Tax Brackets in Retirement
If you are currently in a lower tax bracket and expect your income and tax rates to increase in retirement, paying taxes on your contributions now through a Roth 401(k) can be more financially advantageous than paying taxes on potentially larger withdrawals in a higher tax bracket later. This is a common scenario for young professionals or those early in their careers who anticipate significant salary growth.
Contribution Limits
The IRS sets annual contribution limits for 401(k) plans, which apply to both traditional and Roth 401(k) contributions combined. For 2023, the employee contribution limit is $22,500, with an additional $7,500 catch-up contribution allowed for individuals aged 50 and over. These limits ensure that while the Roth 401(k) offers significant tax benefits, it is still subject to government regulations regarding the amount of tax-advantaged savings one can accumulate.
Who Benefits Most from a Roth 401(k)?
The Roth 401(k) is not a one-size-fits-all solution. Its effectiveness hinges on your individual financial circumstances, age, income, and future tax expectations.
Young Professionals and Early Career Individuals
Those who are early in their careers often find the Roth 401(k) particularly appealing. Their current income may be lower, placing them in a lower tax bracket. This means the tax savings from a traditional 401(k) are less substantial, and paying taxes now on their contributions is a relatively smaller burden. Furthermore, they have a longer time horizon for their investments to grow tax-free, potentially accumulating a substantial tax-free nest egg by retirement.
Individuals Expecting Higher Tax Rates in Retirement

If you anticipate your income in retirement will be higher than your current income, or if you believe overall tax rates will rise significantly in the future, a Roth 401(k) becomes a very attractive option. You’re effectively locking in today’s tax rates on your contributions, avoiding potentially higher taxes on your earnings in a future with increased tax burdens.
High Earners Who Want Tax-Free Income in Retirement
While it might seem counterintuitive for high earners to opt for an after-tax contribution, it can be a strategic move. High earners in their peak earning years might be in their highest tax brackets. While they would forgo an immediate tax deduction, the guarantee of tax-free income in retirement can be invaluable, especially if they plan to maintain a high standard of living and need significant, predictable income streams. The ability to have a large pool of tax-free assets can provide immense flexibility and reduce financial stress in their golden years.
Those Seeking Estate Planning Advantages
The lack of RMDs for the original owner and the ability to pass on tax-free growth to beneficiaries make the Roth 401(k) a powerful estate planning tool. Heirs can inherit the Roth 401(k) and generally withdraw the funds tax-free (subject to their own RMD rules). This allows wealth to be transferred to the next generation with a reduced tax impact.
Roth 401(k) vs. Roth IRA: Understanding the Distinctions
While both Roth 401(k)s and Roth IRAs offer the benefit of tax-free withdrawals in retirement, they are distinct retirement savings vehicles with different rules and advantages.
Employer Sponsorship and Availability
The most significant difference is that a Roth 401(k) is an employer-sponsored plan. This means it is only available if your employer offers it. Not all employers provide a Roth 401(k) option. A Roth IRA, on the other hand, is an individual retirement arrangement that anyone with earned income can open, regardless of their employer’s offerings.
Contribution Limits
As mentioned earlier, 401(k) plans (including Roth 401(k)s) have significantly higher annual contribution limits than IRAs. For 2023, the 401(k) limit is $22,500 (plus catch-up), while the Roth IRA limit is $6,500 (plus catch-up). This makes the Roth 401(k) a better option for those who want to save a larger amount of money for retirement within a tax-advantaged account.
Income Limitations
Roth IRAs have income limitations for contributions. If your modified adjusted gross income (MAGI) exceeds certain thresholds, you may be prohibited from contributing directly to a Roth IRA or your contribution amount may be reduced. Roth 401(k)s, however, do not have income limitations for contributions. This means high-income earners can contribute to a Roth 401(k) even if they are phased out of Roth IRA contributions.
Investment Options
Employer-sponsored 401(k) plans typically offer a curated menu of investment options, often limited to a selection of mutual funds chosen by the plan administrator. While this can simplify choices, it may not always include the broadest range of investment opportunities. Roth IRAs, on the other hand, typically offer a much wider array of investment choices, including individual stocks, bonds, ETFs, mutual funds, and more, allowing for greater customization of an investment portfolio.
Rollover Considerations
A key advantage of the Roth 401(k) is its ability to be rolled over into a Roth IRA when you leave your employer. This consolidation can simplify account management and, importantly, convert the Roth 401(k) into a Roth IRA that is not subject to RMDs for the original owner.
Making the Choice: Roth 401(k) or Traditional 401(k)?
Deciding between a Roth 401(k) and a traditional 401(k) involves a careful assessment of your current financial situation and your projections for the future.
Evaluate Your Current and Future Tax Bracket
The most significant factor in this decision is your anticipated tax bracket in retirement compared to your current tax bracket. If you believe you are in a lower tax bracket now and will be in a higher one in retirement, the Roth 401(k) is likely the superior choice. Conversely, if you are in a high tax bracket now and expect to be in a lower one in retirement, the immediate tax savings of a traditional 401(k) might be more appealing.
Consider Your Age and Time Horizon
Younger individuals with many years until retirement have more time for their Roth 401(k) investments to grow tax-free. This long-term compounding effect can be incredibly powerful. Older individuals closer to retirement may prioritize immediate tax relief from a traditional 401(k) or may not have as much time to benefit from the tax-free growth of a Roth.
Assess Your Need for Current Tax Deductions
If reducing your current taxable income is a high priority, perhaps due to other financial goals or a desire to lower your immediate tax bill, the traditional 401(k) offers that benefit. If you can afford to pay taxes on your contributions now, the long-term tax-free growth of the Roth 401(k) might be a better strategy.
Think About Tax Diversification
Even if one option seems clearly superior based on your primary assessment, consider the value of tax diversification. Holding both traditional and Roth accounts provides flexibility in retirement planning, allowing you to strategically draw from different pools of money to manage your tax liability. Many employers allow you to contribute to both a traditional and a Roth 401(k) simultaneously, up to the combined annual limit.

Conclusion
The Roth 401(k) is a sophisticated retirement savings tool that offers the compelling benefit of tax-free withdrawals in retirement. By understanding its mechanics, features, and who it best serves, individuals can make a more informed decision about how to build a secure and financially resilient future. Whether it’s the promise of tax-free income, the advantage of tax diversification, or the power of long-term tax-free compounding, the Roth 401(k) stands as a vital component in the modern retirement planning arsenal.