
Understanding the documentation required to establish a new bank account is a fundamental step in personal finance management. Whether you’re a seasoned professional looking to streamline your financial operations, an entrepreneur launching a new venture, or an individual embarking on your financial journey, having the correct identification is paramount. This guide will demystify the process, outlining the types of identification generally accepted by financial institutions and offering insights into why these specific documents are necessary.
Understanding the Purpose of Identification in Banking
Financial institutions operate within a highly regulated environment. The primary reason for requiring identification is to comply with stringent “Know Your Customer” (KYC) and Anti-Money Laundering (AML) regulations. These regulations are designed to prevent financial crimes, including money laundering, terrorist financing, and identity theft.

Know Your Customer (KYC) Principles
KYC is a process that banks and other financial services companies use to verify the identity of their clients. It involves collecting and verifying information about a customer to ensure they are who they claim to be. This not only protects the bank from fraud but also safeguards the customer’s assets and personal information. The core principles of KYC include:
- Customer Identification Program (CIP): This is the cornerstone of KYC. Banks must establish procedures to verify the identity of anyone opening an account. This involves collecting specific identifying information, such as name, date of birth, and address.
- Customer Due Diligence (CDD): Once a customer is identified, banks conduct due diligence to understand the nature of their business and the risk associated with their account. This might involve assessing transaction patterns and the source of funds.
- Enhanced Due Diligence (EDD): For higher-risk customers (e.g., politically exposed persons or those involved in high-value transactions), banks may apply EDD, which involves more rigorous verification and ongoing monitoring.
Anti-Money Laundering (AML) Compliance
AML regulations are a set of laws and rules designed to prevent criminals from disguising illegally obtained funds as legitimate income. Banks are obligated to report suspicious transactions to regulatory authorities. The identification process is crucial for AML compliance because it helps to:
- Establish Legitimacy: By verifying a customer’s identity, banks can be more confident that the individual or entity is not attempting to use the account for illicit purposes.
- Trace Transactions: In the unfortunate event of financial crime, verified identification allows authorities to trace the flow of funds and identify the parties involved.
- Prevent Account Abuse: Stolen or synthetic identities can be used to open accounts for fraudulent activities. Robust ID checks make this much harder.
The rigorousness of these requirements underscores why banks cannot simply open accounts based on verbal confirmation or unsubstantiated claims. The documentation serves as tangible proof of identity and, in many cases, residency.
Primary Identification Documents
When opening a bank account, financial institutions will typically require one or more forms of primary identification. These documents are generally government-issued and contain a photograph, making them difficult to forge. The specific requirements can vary slightly between banks and jurisdictions, but the following are almost universally accepted:
Government-Issued Photo Identification
This is the most critical piece of documentation. It serves as proof of your identity and often includes your legal name, date of birth, and a photograph.
- Driver’s License: In most countries, a valid driver’s license is the most common form of identification. It’s widely recognized and contains all the necessary personal details. Ensure that your license is not expired and that the address listed on it is current or you have a secondary document to prove your current address.
- Passport: A passport is an internationally recognized form of identification and is often required for non-residents or for individuals seeking to open accounts with specific international banks. It provides a high level of assurance regarding your identity. Like a driver’s license, it must be current.
- National Identity Card: Many countries issue national identity cards that serve as a primary form of identification. These cards typically bear a photograph and essential personal data. The validity and acceptance of national ID cards can depend on the issuing country and the bank’s policies.
- State or Military ID: For individuals who do not drive or possess a passport, state-issued identification cards (similar to driver’s licenses but without driving privileges) or military identification cards are often acceptable. These are issued by government entities and carry significant weight in verification processes.
Key Features of Primary Identification
When presenting your primary identification, banks look for several key features to ensure authenticity and accuracy:
- Photograph: A clear, recent photograph that reasonably matches your current appearance.
- Full Legal Name: The name must match other documents precisely.
- Date of Birth: This is a crucial identifier to distinguish individuals.
- Issuing Authority: The document must be issued by a recognized government body.
- Expiration Date: The identification must be valid and not expired.
- Unique Identification Number: Such as a driver’s license number or passport number.
It’s imperative to have your identification documents in order and ensure they are up-to-date before visiting a bank or initiating an online account opening process.
Secondary Identification and Proof of Address
In addition to primary photo identification, banks often require secondary identification and proof of your residential address. This is to further corroborate your identity and confirm your physical location.
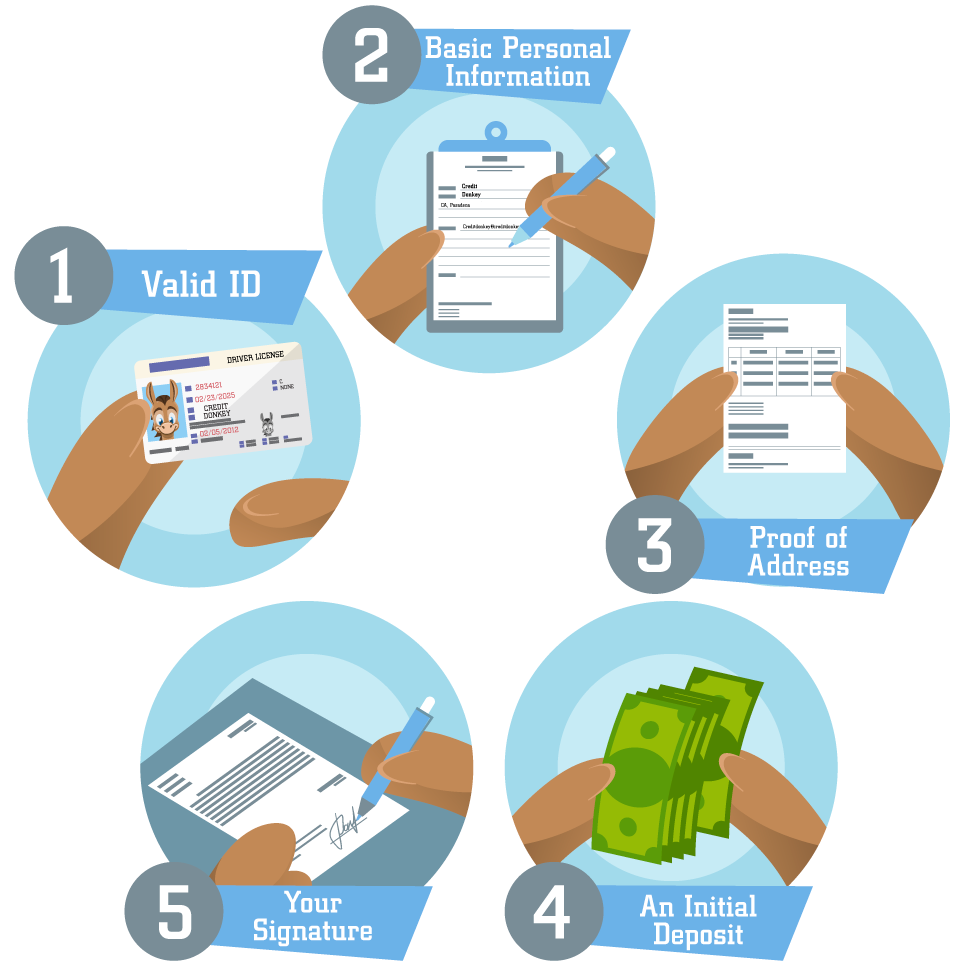
Proof of Address Documents
This documentation confirms where you reside. It’s essential for banks to have a reliable address for correspondence, sending bank statements, and for regulatory purposes.
- Utility Bills: Recent utility bills (e.g., electricity, gas, water, internet) are commonly accepted. These bills must typically be dated within the last three months and show your name and current residential address.
- Bank or Credit Card Statements: Statements from other financial institutions can serve as proof of address, provided they contain your name and current address and are recent (usually within the last three months).
- Lease Agreement or Mortgage Statement: If you rent or own your home, a current lease agreement or a recent mortgage statement can be used as proof of address.
- Government-Issued Mail: Official correspondence from government agencies, such as tax notices or social security statements, bearing your name and address, can also be accepted.
- Voter Registration Card: In some jurisdictions, a valid voter registration card can be used to confirm your address.
Secondary Identification (if primary is insufficient or for specific situations)
While primary photo ID is usually sufficient, some situations might necessitate secondary identification, especially if the primary ID is not a government-issued document or if there are concerns about authenticity.
- Social Security Card (or equivalent national insurance number): While not a photo ID, a social security card is a critical document that confirms your national identification number. It’s often used in conjunction with other forms of ID.
- Birth Certificate: A certified copy of your birth certificate can be used as proof of identity, particularly for individuals who may not have readily available government-issued photo ID.
- Marriage Certificate: This document can be relevant if your name has changed due to marriage and you are presenting identification under your former name.
- Student ID Card (with limitations): Some banks might accept a student ID card, but it’s usually only as a secondary form of ID, and often only for students opening specific types of accounts, and it must be accompanied by a primary ID.
It’s important to check with the specific bank about their accepted forms of secondary identification and proof of address, as policies can vary.
Special Considerations for Different Applicant Types
The documentation required can differ depending on your status as an applicant, such as being a minor, a non-resident, or representing a business.
Opening an Account for a Minor
When opening a bank account for a child, the requirements often involve the parent or legal guardian.
- Child’s Identification: This may include a birth certificate, Social Security card, or passport.
- Parent/Guardian’s Identification: The parent or legal guardian will need to provide their primary photo identification (driver’s license, passport) and proof of address.
- Guardianship Documentation: In cases where the applicant is not the parent but a legal guardian, official documentation proving guardianship will be required.
Non-Residents and Foreign Nationals
For individuals who are not citizens or residents of the country where they wish to open an account, the requirements can be more stringent.
- Passport: A valid, unexpired passport is almost always required.
- Visa or Immigration Documents: Proof of legal status in the country, such as a visa, residency permit, or work permit, will likely be necessary.
- Proof of Foreign Address: Documentation proving your address in your home country might be requested.
- Secondary Identification: Additional forms of identification from your home country might be requested.
- Employer Letter: Some banks may ask for a letter from your employer confirming your employment status and the duration of your stay.
Business Accounts
Opening a bank account for a business involves different documentation than for personal accounts, as you are verifying the identity of the business and its authorized signatories.
- Business Registration Documents: This includes your Certificate of Incorporation or Registration, Articles of Incorporation, or Partnership Agreement.
- Employer Identification Number (EIN) or Tax Identification Number: This is a unique number issued by the tax authorities for the business.
- Business License: Any relevant licenses required to operate the business.
- Identification for Authorized Signatories: Each individual authorized to operate the account will need to provide their primary photo identification and proof of address, similar to opening a personal account.
- Proof of Business Address: Utility bills or lease agreements in the business’s name.
- Resolution of the Board of Directors: A formal document authorizing the opening of the bank account and specifying who has the authority to sign checks and make transactions.
Banks have specific checklists for business account openings, so it’s advisable to contact the business banking division beforehand to understand their exact requirements.

Tips for a Smooth Account Opening Process
Navigating the process of opening a bank account can be straightforward if you come prepared. Here are some tips to ensure a smooth experience:
- Contact the Bank in Advance: Before visiting a branch or starting an online application, check the bank’s website or call them to inquire about their specific identification requirements. This will save you time and potential disappointment.
- Gather All Documents: Ensure you have all necessary original documents (and potentially copies, though originals are usually preferred for verification). Double-check expiration dates on all identification.
- Ensure Consistency: Make sure your name and address are consistent across all documents. Any discrepancies can cause delays or require further verification.
- Be Prepared for Verification: Banks may use various methods to verify your information, including checking credit bureaus or government databases.
- Ask Questions: If you are unsure about any requirement or the process, don’t hesitate to ask bank staff for clarification.
- Consider Online vs. In-Person: Many banks now offer online account opening. While convenient, ensure you have your digital documents ready and understand their verification process. In-person applications can sometimes be more straightforward for complex situations.
Opening a bank account is a crucial step towards managing your finances effectively. By understanding the types of identification required and being well-prepared, you can ensure a swift and hassle-free process. The emphasis on rigorous identification procedures by financial institutions ultimately serves to protect both the customer and the integrity of the financial system.