
Understanding the Ramifications of Defaulting on Federal Student Loans
Defaulting on student loans is a serious financial event with far-reaching consequences, primarily impacting federal loan borrowers. The definition of default varies slightly between loan types, but generally, it occurs when a borrower fails to make payments for a specified period, typically 270 days for federal Direct Loans and Perkins Loans. For Federal Family Education Loan (FFEL) Program loans, default can occur after 360 days of delinquency. The consequences of this financial misstep are significant and can linger for years, affecting an individual’s creditworthiness, income, and even their ability to access essential services.
The Immediate Impact on Your Credit Score
One of the most immediate and damaging effects of defaulting on student loans is the severe negative impact on your credit score. When you miss payments and eventually go into default, your loan servicer will report this delinquency to the major credit bureaus: Experian, Equifax, and TransUnion. This negative information will remain on your credit report for seven years from the date of the original delinquency, significantly lowering your credit score. A lower credit score makes it harder to:
- Obtain new credit cards or loans.
- Secure favorable interest rates on mortgages, auto loans, or personal loans.
- Rent an apartment or secure housing.
- Obtain certain types of employment, especially those requiring a credit check.
- Even secure a mobile phone contract or utility services without a substantial deposit.
The longer a loan remains in default, the more it will depress your credit score, creating a compounding negative effect on your financial life. Rebuilding a damaged credit score is a long and arduous process, requiring consistent positive financial behavior over an extended period.
Government Actions and Collections
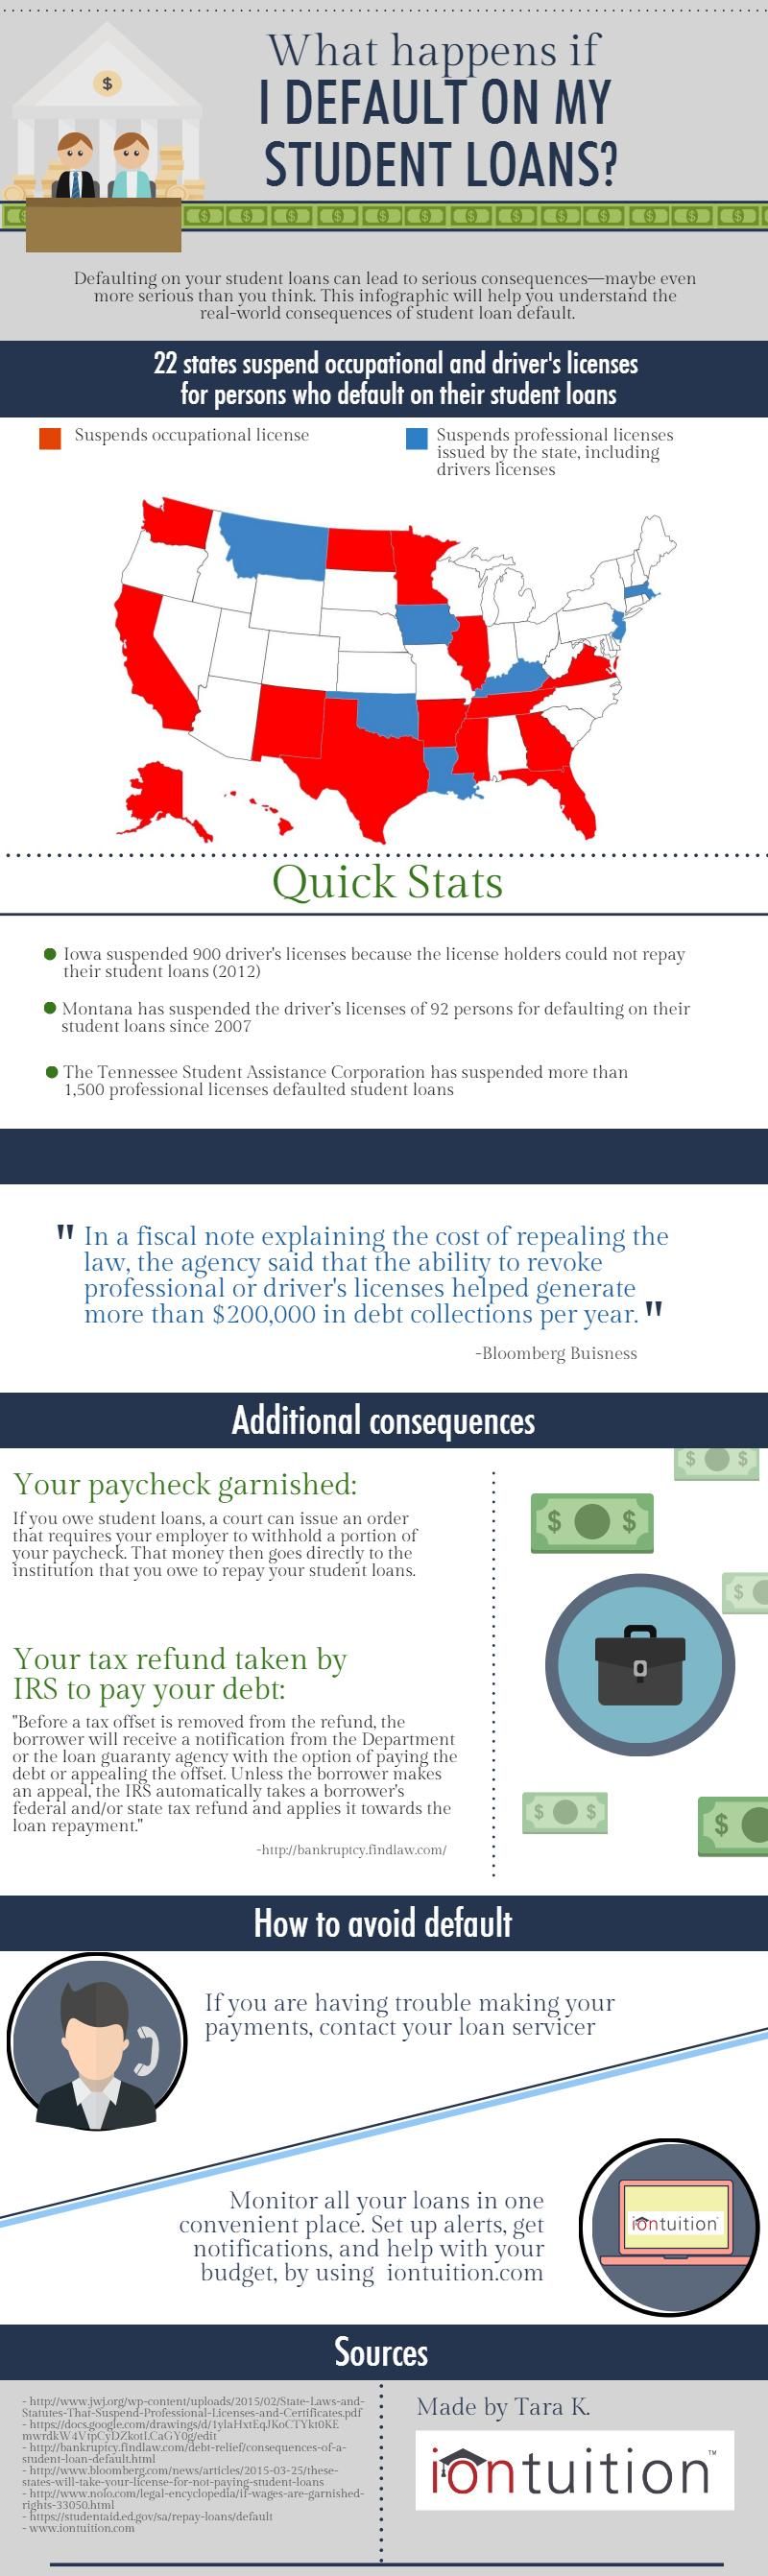
Once your federal student loan enters default, the U.S. Department of Education has several powerful tools at its disposal to recover the outstanding debt. Unlike private loans, federal loans are backed by the government, which provides them with significant collection powers that do not require going to court. These actions can include:
Wage Garnishment
The most common and impactful collection action is wage garnishment. The Department of Education can order your employer to withhold a portion of your wages – up to 15% of your disposable pay for student loans – and send it directly to the government to repay the defaulted loan. This garnishment can occur without a court order, meaning you may not have advance notice. The garnishment can continue until the loan is paid in full, including accrued interest and fees. This can significantly reduce your monthly income, making it even more challenging to meet your other financial obligations.
Tax Refund Offset
Another powerful collection tool is the Treasury Offset Program. This allows the government to intercept and seize your federal and state tax refunds. If you are due a refund, it will be redirected to your defaulted student loan account. This can be a substantial financial blow, especially if you rely on your tax refund for essential expenses. The government can also offset other federal payments, such as Social Security benefits (though there are some protections for a portion of these benefits).
Loss of Professional Licenses
For certain professions, defaulting on federal student loans can lead to the suspension or revocation of professional licenses. This can have a devastating impact on your career, making it impossible to practice your chosen profession. This consequence is particularly relevant for individuals in fields like teaching, nursing, or law, where professional licensing is a requirement.
Ineligibility for Further Federal Aid
If you default on federal student loans, you will become ineligible for any further federal student aid. This means you will not be able to receive Pell Grants or take out new federal student loans to finance future education. This can be a significant barrier to pursuing higher education or returning to school for advanced degrees or retraining.
Accrual of Fees and Interest
When a student loan goes into default, it’s not just the original principal amount that you owe. The debt continues to grow significantly due to the accrual of interest and the imposition of various fees. These can include:
- Late Fees: Charged for each missed payment.
- Collection Costs: Fees associated with the government’s efforts to collect the debt, which can include attorney fees and other administrative expenses.
- Default Fees: Some loan programs may impose additional fees specifically for defaulting.
The interest that continues to accrue on the outstanding balance, combined with these added fees, can dramatically increase the total amount you owe, making repayment even more daunting. In some cases, the total debt could be substantially higher than the original loan amount.

Options for Federal Loan Borrowers Facing Default
While the consequences of default are severe, there are often options available to borrowers to avoid or resolve default. It is crucial to act quickly if you are struggling to make payments.
1. Contact Your Loan Servicer Immediately
The first and most important step is to communicate with your student loan servicer as soon as you realize you might miss a payment or are already behind. They can explain your options and guide you through the process of finding a solution. Ignoring the problem will only make it worse.
2. Loan Consolidation
Federal Direct Consolidation Loans allow you to combine multiple federal student loans into a single new loan with a single monthly payment. This can simplify your repayment and may lower your monthly payment, but it typically extends the repayment period, meaning you may pay more interest over time. Importantly, consolidating a defaulted loan can remove the default status and restore your eligibility for federal student aid. However, it’s crucial to understand that consolidation does not eliminate the debt; it merely restructures it.
3. Income-Driven Repayment (IDR) Plans
These plans, such as Income-Based Repayment (IBR), Pay As You Earn (PAYE), and Revised Pay As You Earn (REPAYE), tie your monthly loan payments to your income and family size. If your income is low, your monthly payment can be significantly reduced, making it more manageable. After a certain number of years (typically 20 or 25) of making payments under an IDR plan, the remaining balance may be forgiven. However, it’s important to note that any forgiven amount may be considered taxable income in the year it is forgiven.
4. Deferment and Forbearance
While not a long-term solution, deferment and forbearance can temporarily postpone your loan payments.
- Deferment: Allows you to temporarily stop making payments on your federal student loans. Interest may or may not accrue during deferment, depending on the loan type. Deferment is generally available for specific situations, such as returning to school, unemployment, or economic hardship.
- Forbearance: Also allows you to temporarily stop or reduce your loan payments for a limited time. However, interest typically continues to accrue on all loan types during forbearance, meaning your loan balance will increase. Forbearance is often an option when you are facing short-term financial difficulties.
Entering deferment or forbearance can prevent immediate default, but it’s vital to understand the interest implications and have a plan for resuming payments.
5. Rehabilitation
Loan rehabilitation is a process specifically designed to help defaulted federal student loans get back on track. By making a certain number of on-time, reasonable payments (usually nine on-time payments within a 10-month period), you can bring your loan out of default. Once rehabilitated, the negative credit reporting associated with the default is removed, and you regain eligibility for federal student aid. This is often the preferred method for clearing a default because it removes the negative mark from your credit report.
The Unique Case of Private Student Loans
While this discussion primarily focuses on federal student loans, it’s important to acknowledge private student loans. The consequences of defaulting on private loans are generally less severe in terms of government collection powers. However, private lenders can and will pursue legal action to collect the debt. This can lead to:
- Lawsuits: The lender can sue you for the outstanding debt.
- Judgments: If the lender wins the lawsuit, they can obtain a court judgment against you.
- Wage Garnishment (Court-Ordered): A court judgment can allow the lender to garnish your wages, but this requires a judicial process.
- Bank Levy: A court order could allow the lender to seize funds from your bank accounts.
- Property Liens: The lender could place a lien on your assets, such as your home or car.
Unlike federal loans, there are typically no income-driven repayment plans or loan rehabilitation options for private loans. Forgiveness programs are also extremely rare. Working with a private lender to find a solution before default is paramount, as their collection powers can still have a significant and lasting impact on your financial well-being.
Preventing Default: Proactive Measures
The best strategy regarding student loans is to prevent default altogether. This requires diligent financial planning and open communication with your loan servicers. Key preventive measures include:
- Budgeting: Create a realistic budget that accounts for your student loan payments.
- Understanding Your Loans: Know the types of loans you have, their interest rates, and their repayment terms.
- Exploring Repayment Options Early: If you anticipate financial difficulties, research and apply for income-driven repayment plans or explore deferment/forbearance options before you miss a payment.
- Seeking Financial Counseling: Non-profit credit counseling agencies can provide valuable advice and assistance in managing your debt.
- Prioritizing Loan Payments: Treat your student loan payments as a critical financial obligation.
Defaulting on student loans can create a cascade of negative financial consequences that can take years to overcome. By understanding the potential ramifications and proactively exploring available options, borrowers can navigate the challenges of student loan repayment and avoid the devastating impact of default.