
The world of finance, like many specialized fields, is rife with acronyms and jargon that can leave even the most seasoned professional scratching their head. Among these, the term “CD” in banking is a particularly common and important one to understand. Far from being a digital storage medium or a musical format, in the context of finance, “CD” unequivocally stands for Certificate of Deposit. While seemingly straightforward, the nuances of Certificates of Deposit, their benefits, risks, and how they function within a broader financial strategy, are worthy of in-depth exploration. This article will demystify the CD, providing a comprehensive overview for individuals and businesses alike seeking to understand this foundational banking product.
Understanding the Certificate of Deposit
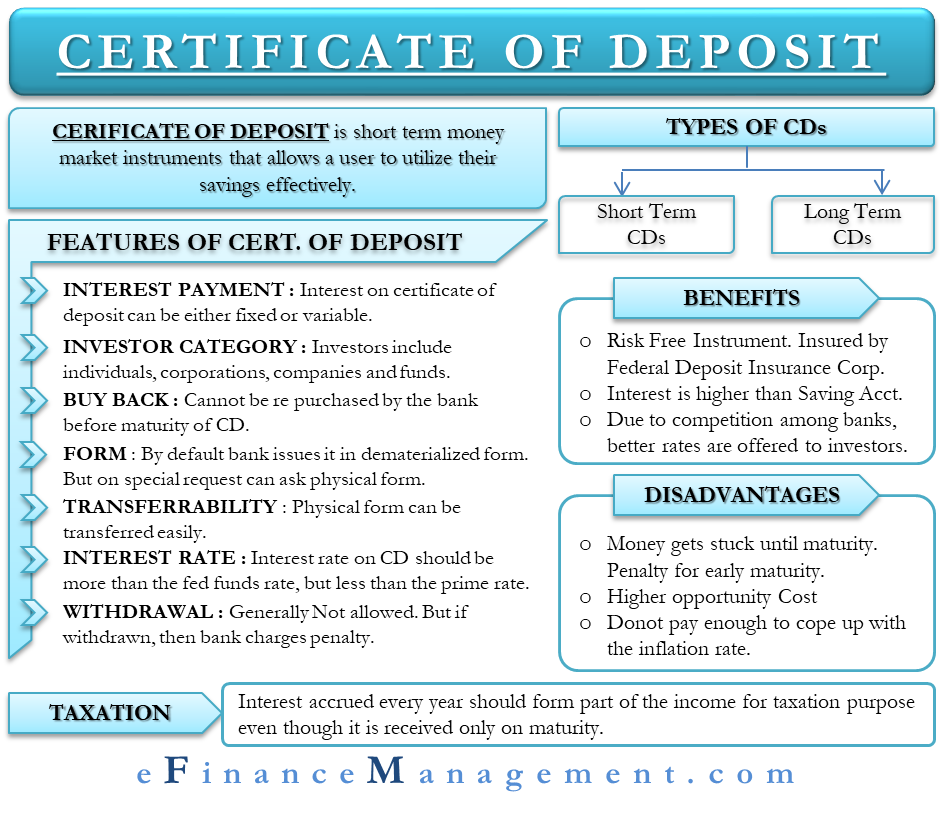
At its core, a Certificate of Deposit is a savings product offered by banks and credit unions that pays a fixed interest rate on a lump sum of money over a predetermined period. This period, known as the term or maturity date, can range from a few months to several years. In exchange for depositing funds for this specified duration, the financial institution typically offers a higher interest rate than what would be available through a standard savings or checking account. This inherent trade-off – locking away funds for a set time in return for a better yield – is the defining characteristic of a CD.
Key Features and Mechanics
Several key components define a Certificate of Deposit:
- Principal Amount: This is the initial sum of money deposited into the CD. There are often minimum deposit requirements, though these can vary significantly between institutions and account types.
- Interest Rate: This is the rate of return offered on the principal amount. CD interest rates are typically fixed for the entire term, providing predictability in earnings. They are often expressed as an Annual Percentage Yield (APY), which reflects the total interest earned over a year, including the effects of compounding.
- Term (Maturity Date): This is the duration for which the money is deposited. Common terms include 3 months, 6 months, 1 year, 2 years, 3 years, 5 years, and sometimes longer. The longer the term, generally the higher the interest rate offered, reflecting the increased commitment of funds by the depositor.
- Early Withdrawal Penalty: One of the most crucial aspects of a CD is the penalty for withdrawing funds before the maturity date. This penalty typically involves forfeiting a portion of the accrued interest, and in some cases, a small portion of the principal. The exact penalty structure varies by bank, but it’s designed to discourage early access to funds.
- Automatic Renewal: Upon maturity, most CDs will automatically renew for a similar term at the prevailing interest rate at that time, unless the depositor instructs the bank otherwise. This process, known as “rollover,” is important to be aware of, as failing to act can lead to the CD renewing at a potentially less favorable rate.
Types of Certificates of Deposit
While the fundamental concept of a CD remains consistent, various types cater to different financial goals and risk appetites:
- Standard CDs: These are the most common type, offering a fixed interest rate for a fixed term with a standard early withdrawal penalty.
- Jumbo CDs: These CDs typically require significantly higher minimum deposits (often $100,000 or more) but usually come with slightly higher interest rates than standard CDs.
- No-Penalty CDs: As the name suggests, these CDs allow you to withdraw your principal and earned interest without incurring a penalty, usually after an initial waiting period (e.g., 7 days). While offering flexibility, their interest rates are often lower than traditional CDs.
- Callable CDs: These are less common and are designed for the bank, not necessarily the depositor. A callable CD allows the issuing bank to redeem the CD before its maturity date, usually when interest rates have fallen significantly. If called, the depositor receives their principal and accrued interest up to that point, but loses out on potential future higher earnings.
- Variable-Rate CDs: Unlike standard CDs with fixed rates, variable-rate CDs have interest rates that can fluctuate over the term, typically tied to a benchmark interest rate. This offers potential upside if rates rise but also carries the risk of lower earnings if rates fall.
- Bump-Up CDs: These CDs allow the depositor to “bump up” their interest rate to the bank’s current offering if rates increase during the CD’s term. This provides some protection against rising interest rate environments.
Benefits of Investing in Certificates of Deposit
Certificates of Deposit offer several compelling advantages for investors looking for safety, predictability, and a reasonable return on their savings.
Safety and Security
One of the primary attractions of CDs is their inherent safety. Deposits in banks and credit unions are insured by the Federal Deposit Insurance Corporation (FDIC) or the National Credit Union Administration (NCUA), respectively. This insurance typically covers up to $250,000 per depositor, per insured bank, for each account ownership category. This government backing provides a significant layer of security, making CDs a very low-risk investment option, especially when compared to the stock market or other more volatile assets. Investors can rest assured that their principal is protected, even if the financial institution were to fail.
Predictable Returns
In an environment of economic uncertainty, the predictability of a CD’s return is highly valued. The fixed interest rate means that investors know precisely how much interest their money will earn over the life of the CD. This allows for effective financial planning, enabling individuals to set aside funds for specific future goals, such as a down payment on a house, a significant purchase, or retirement income. The absence of market fluctuations means that the earnings are guaranteed, providing peace of mind.
Higher Interest Rates Than Traditional Savings Accounts
Generally, CDs offer higher interest rates than regular savings accounts or money market accounts. This is because the bank benefits from having access to your funds for a defined period, allowing them to lend it out with more certainty. For those who have funds they don’t need immediate access to, a CD can be an effective way to grow their savings more quickly than simply letting it sit in a liquid account. The difference in interest earned can be substantial, especially on larger principal amounts or over longer terms.
Diversification of Investment Portfolio
While often considered a conservative investment, CDs play a vital role in diversifying an investment portfolio. A well-rounded portfolio typically includes a mix of assets with varying risk and return profiles. For investors who have allocated a significant portion of their assets to higher-risk investments like stocks, including CDs can help balance the overall risk of the portfolio. They provide a stable anchor, ensuring that some portion of the investment capital is protected from market downturns.
Considerations and Potential Drawbacks of CDs
Despite their numerous benefits, Certificates of Deposit are not without their limitations and potential downsides that investors must carefully consider.

Liquidity Constraints (Early Withdrawal Penalties)
The most significant drawback of CDs is their illiquidity. By definition, you are agreeing to keep your money deposited for a set term. Attempting to access these funds before the maturity date will almost always result in a penalty. These penalties are typically calculated as a forfeiture of a certain number of months’ worth of interest. For example, a common penalty might be three months’ interest on a one-year CD. If interest rates are low, or if the CD has not accrued much interest yet, this penalty could eat into your principal, resulting in a net loss on your investment. This makes CDs unsuitable for funds that may be needed unexpectedly or for emergency savings.
Inflation Risk
While CDs offer fixed returns, they can be vulnerable to inflation. If the rate of inflation outpaces the interest rate earned on the CD, the purchasing power of your money will actually decrease over time. For instance, if a CD offers a 3% APY and inflation is running at 4%, your money is effectively losing 1% of its purchasing power each year. This is a critical consideration, especially in periods of high inflation, where the “real” return (nominal return minus inflation) can be negative.
Opportunity Cost in Rising Interest Rate Environments
When interest rates are on the rise, investing in a fixed-rate CD can lead to an opportunity cost. If you lock in a CD at a 3% rate and then a year later, similar CDs are offering 5%, you are essentially missing out on those higher potential earnings. While you can’t predict interest rate movements with certainty, it’s a factor to weigh, particularly when considering longer-term CDs in an environment where rates are expected to increase.
Interest Rate Sensitivity
The value of a CD is inversely related to interest rate movements, particularly if you were to sell it before maturity in a secondary market (though this is less common for retail CDs). If interest rates rise, the market value of an existing CD with a lower fixed rate will fall, as new CDs are offering better returns. Conversely, if interest rates fall, the market value of an existing CD with a higher fixed rate would rise. However, for most individual investors holding CDs to maturity, this market fluctuation is not a primary concern, as they will receive the principal and stated interest.
How to Choose and Utilize Certificates of Deposit Effectively
Given the characteristics of Certificates of Deposit, strategic selection and utilization are key to maximizing their benefits while mitigating their drawbacks.
Assessing Your Financial Goals and Timeline
The first step in considering a CD is to honestly assess your financial goals and the timeline associated with them.
- Short-Term Goals (0-2 years): For funds needed within a short timeframe, such as for an upcoming vacation or a down payment in the near future, shorter-term CDs (e.g., 6 months to 1.5 years) are generally more appropriate. These offer a better return than standard savings accounts without the significant liquidity risk of longer terms.
- Medium-Term Goals (2-5 years): If you have funds you won’t need for a few years, medium-term CDs can provide a good balance of yield and commitment. The interest rates for these terms are typically higher than short-term options.
- Long-Term Goals (5+ years): For money that is truly set aside for the distant future, such as retirement savings that are not in a tax-advantaged account, longer-term CDs can offer more competitive rates. However, it’s crucial to weigh this against the potential for inflation and the opportunity cost in a rising rate environment.
Comparing Rates and Terms Across Institutions
The interest rate offered on a CD can vary significantly from one bank or credit union to another. It is essential to shop around and compare rates. Online banks, in particular, often offer more competitive rates than traditional brick-and-mortar institutions due to lower overhead costs.
- APY is Key: Always look at the Annual Percentage Yield (APY), which includes the effect of compounding interest, rather than just the simple interest rate.
- Consider Fees: While less common for CDs themselves, be aware of any account service fees that might erode your earnings.
- Read the Fine Print: Pay close attention to the early withdrawal penalty terms, the renewal policy, and any other specific conditions of the CD.
Laddering CDs
A popular strategy for mitigating the liquidity risk and interest rate sensitivity of CDs is called “CD laddering.” This involves dividing your investment funds into several CDs with staggered maturity dates. For example, instead of putting $10,000 into one 5-year CD, you might divide it into five $2,000 CDs, each maturing one year apart.
The benefits of laddering include:
- Regular Access to Funds: As each CD matures, you have a portion of your money become available, providing liquidity.
- Opportunity to Reinvest at Current Rates: When a CD matures, you can reinvest that portion at the prevailing interest rates. If rates have risen, you benefit from the higher yields. If rates have fallen, you still have other CDs locked in at potentially higher historical rates.
- Reduced Impact of Early Withdrawal Penalties: If you need access to a portion of your funds, you can withdraw from the shortest-term CD in your ladder without incurring a penalty on the entire sum.

Utilizing CDs for Specific Financial Needs
- Building an Emergency Fund (with caution): While not ideal due to penalties, some may opt for very short-term CDs (e.g., 3-6 months) for a portion of their emergency fund if they are confident they won’t need the funds and want to earn slightly more than a savings account. However, truly liquid savings accounts are generally preferred for emergency funds.
- Saving for a Down Payment: CDs are excellent for saving for a down payment on a home or for a large purchase expected in 1-5 years. The fixed rate ensures the principal grows predictably.
- Retirement Income (Short-Term): For individuals nearing or in retirement, CDs can provide a stable and predictable income stream for funds not invested in more volatile assets.
In conclusion, the Certificate of Deposit, or CD, is a cornerstone of conservative banking and investing. It offers a secure avenue for growth with predictable returns, making it an attractive option for a variety of financial objectives. By understanding its mechanics, benefits, drawbacks, and employing strategic approaches like laddering, individuals can effectively incorporate CDs into their financial plans to achieve security and steady wealth accumulation.