
The Innovation of Individual Retirement Accounts in Modern Finance
The landscape of personal finance has been dramatically reshaped by a confluence of technological advancements and innovative financial product design. Among the most pivotal developments are the Individual Retirement Accounts (IRAs), chief among them the Roth and Traditional IRAs. These vehicles represent significant innovations in allowing individuals to take control of their retirement savings, providing distinct tax advantages that cater to diverse financial strategies. Their emergence and subsequent evolution are deeply intertwined with the increasing sophistication of financial technology, which has democratized access to investment tools and complex financial planning. The ability to manage these accounts, track performance, and make informed decisions has been significantly enhanced by digital platforms, robo-advisors, and AI-driven financial insights, making them more accessible and powerful than ever before. Understanding their core differences is not just about tax rules; it’s about leveraging innovative financial structures in a technologically advanced world.

Evolution of Personal Savings and Tax Strategy
Historically, retirement planning was often a more opaque and less individualized process, heavily reliant on employer-sponsored pensions. The introduction of IRAs marked a paradigm shift, empowering individuals with direct control over their retirement savings and offering innovative tax incentives designed to encourage long-term wealth accumulation. This innovation wasn’t merely about creating new account types but about introducing flexibility in how individuals could manage their tax burden across their working lives and into retirement. The traditional model offered immediate tax relief, deferring the tax liability, while the Roth model pioneered the concept of tax-free growth and withdrawals in retirement, contingent on after-tax contributions. This strategic divergence allowed for a more personalized approach to tax planning, a complexity that modern financial technology, from sophisticated tax software to predictive analytics, now helps investors navigate with unprecedented clarity. These digital tools analyze an individual’s current income, projected future earnings, and risk tolerance to recommend the optimal IRA choice, a level of personalized guidance that was unthinkable a few decades ago.
Digital Platforms and Accessible Investment
The true power of Roth and Traditional IRAs in the modern era is amplified by the technological infrastructure that supports them. Online brokerage platforms, mobile investment apps, and robo-advisors have transformed these retirement accounts from niche financial products into mainstream tools. These digital innovations provide intuitive interfaces for setting up accounts, automating contributions, selecting investments, and monitoring performance in real-time. For instance, sophisticated algorithms now offer personalized asset allocation strategies within IRAs, dynamically rebalancing portfolios based on market conditions and an individual’s evolving financial goals. This digital accessibility has lowered the barriers to entry for countless investors, allowing them to manage their retirement savings with a level of control and insight previously reserved for institutional investors or those with significant wealth to afford dedicated financial advisors. The integration of AI and machine learning further refines these platforms, offering predictive insights into optimal contribution levels, withdrawal strategies, and even potential tax implications, truly embedding these innovative financial products within a broader technological ecosystem.
Understanding Traditional IRAs: A Cornerstone of Tax-Deferred Growth
The Traditional IRA stands as a foundational element of innovative retirement planning, distinguished by its unique approach to tax deferral. It represents a strategic financial instrument designed for individuals seeking immediate tax relief and long-term tax-deferred growth. Its operational framework, while seemingly straightforward, harnesses a nuanced understanding of future tax liabilities and present-day financial optimization, all significantly enhanced by contemporary financial technology.
Pre-Tax Contributions and Immediate Benefits
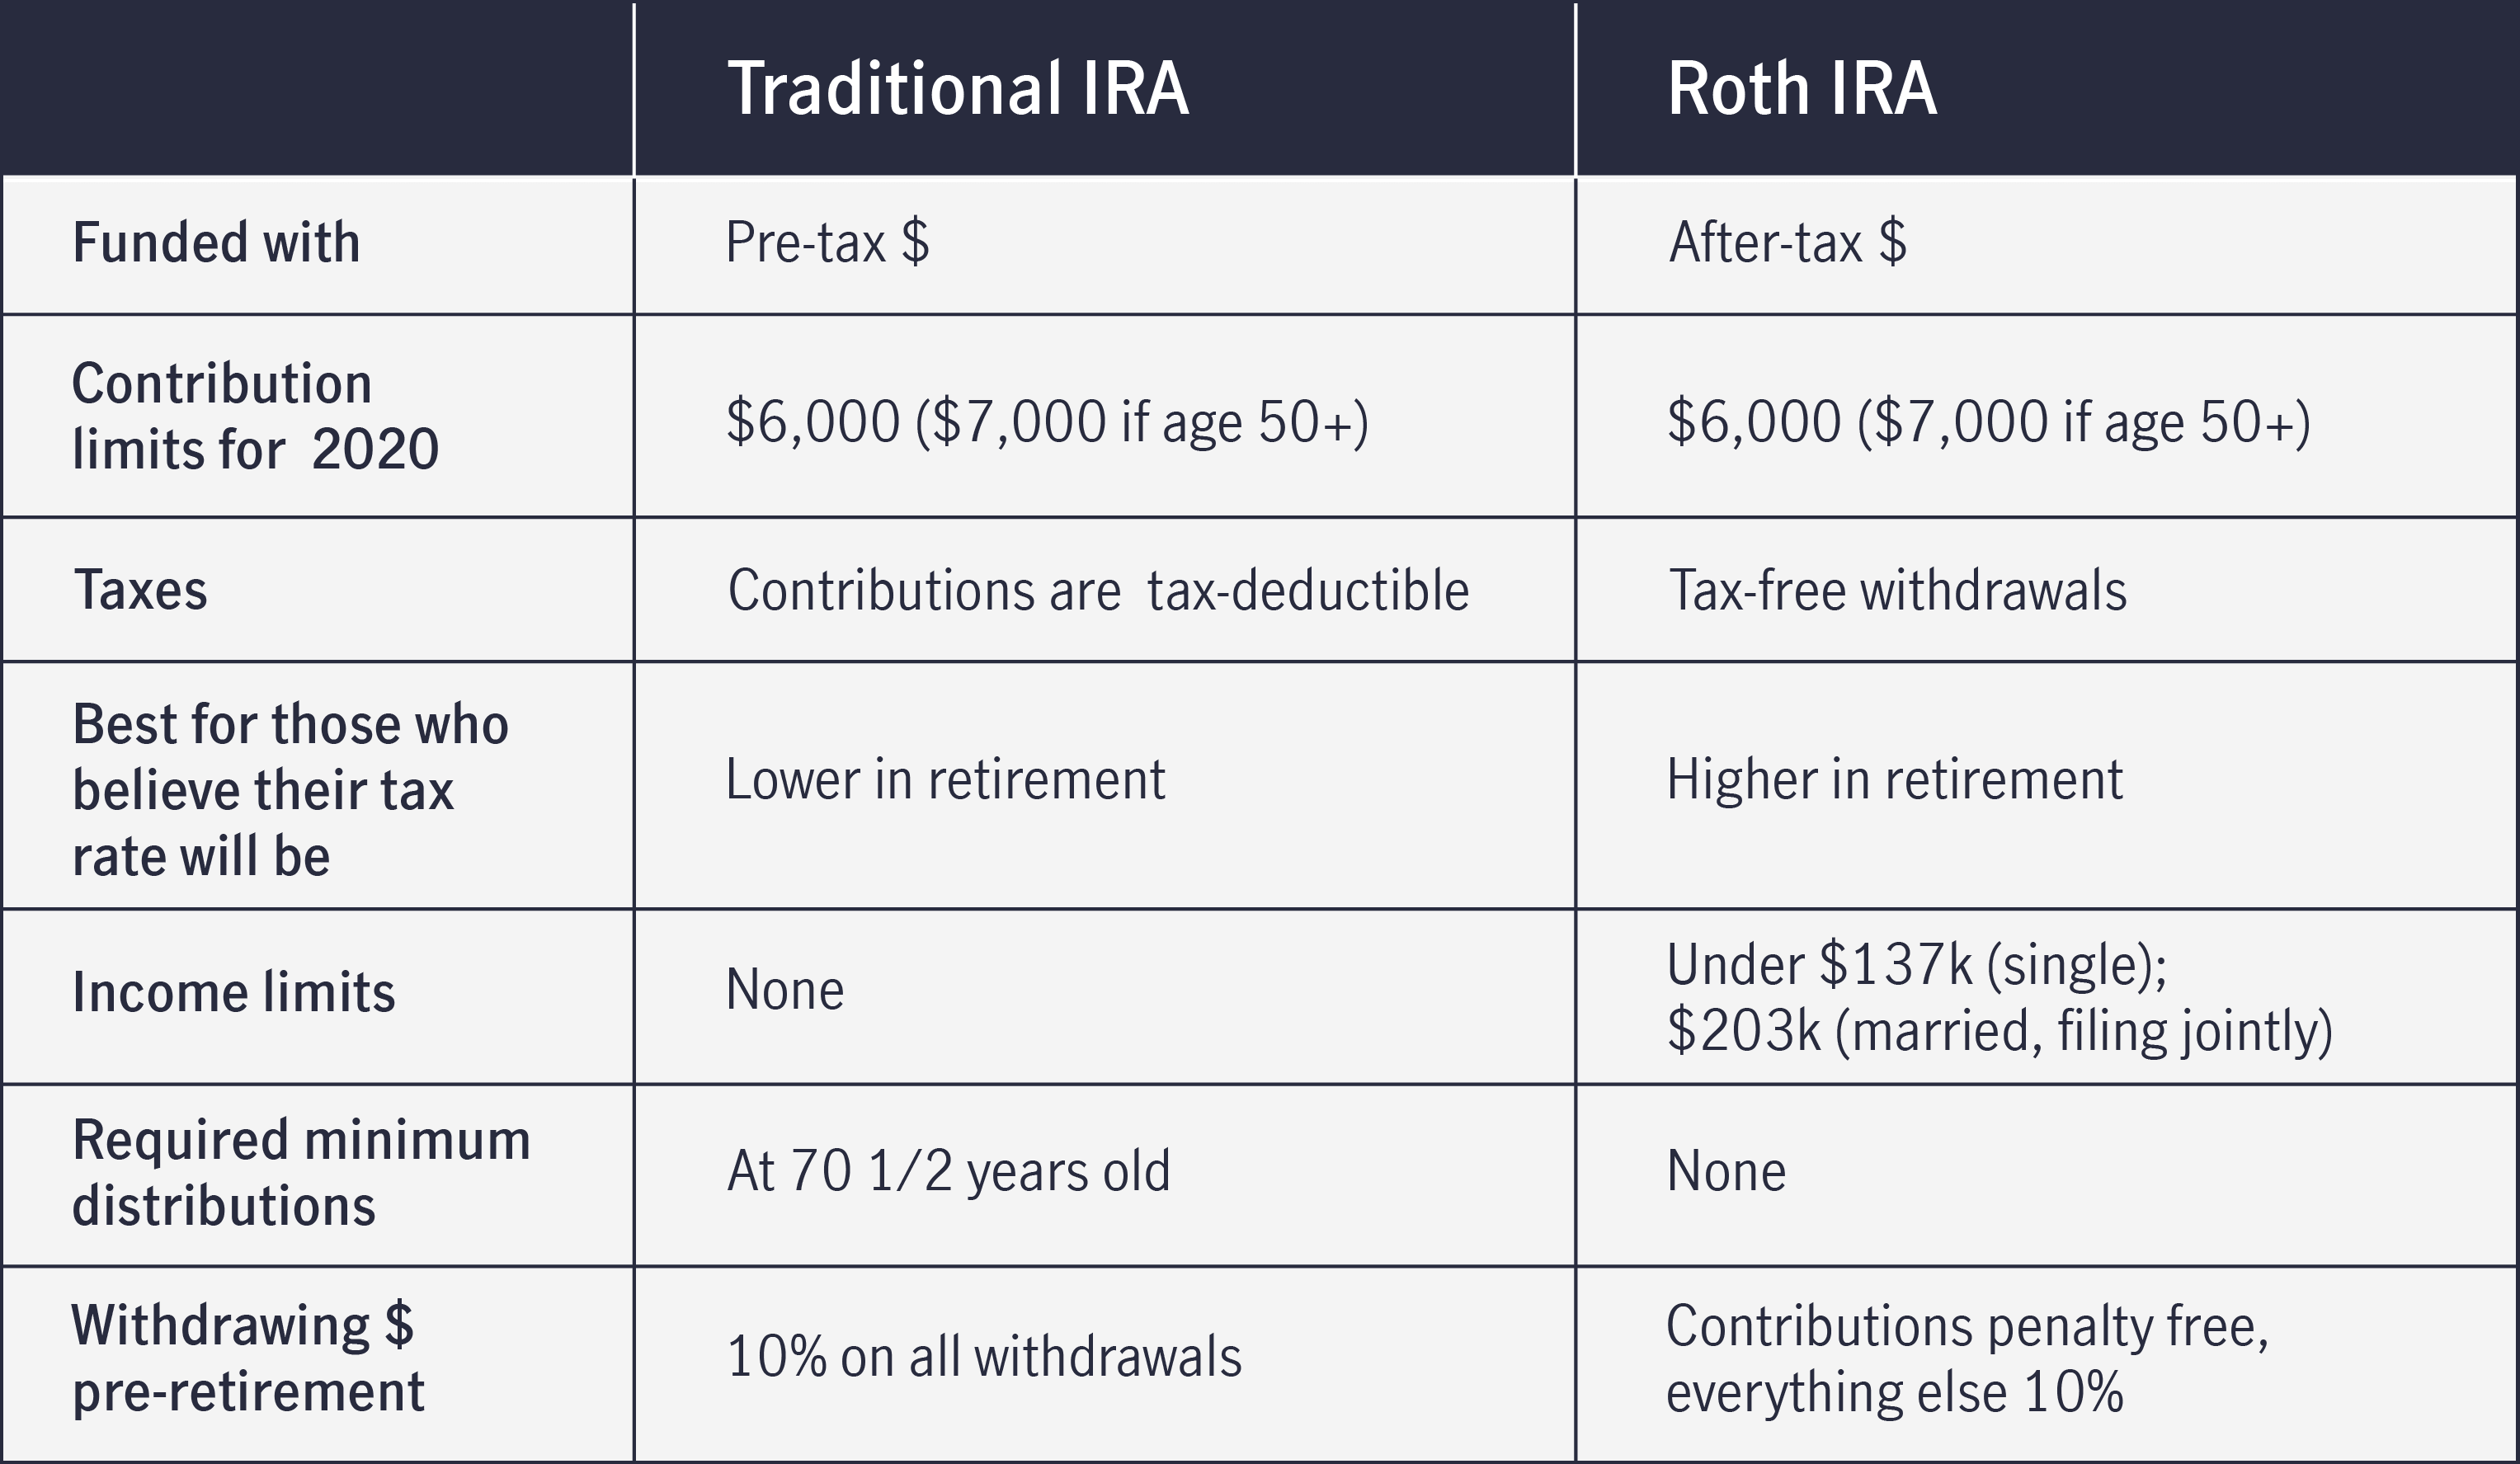
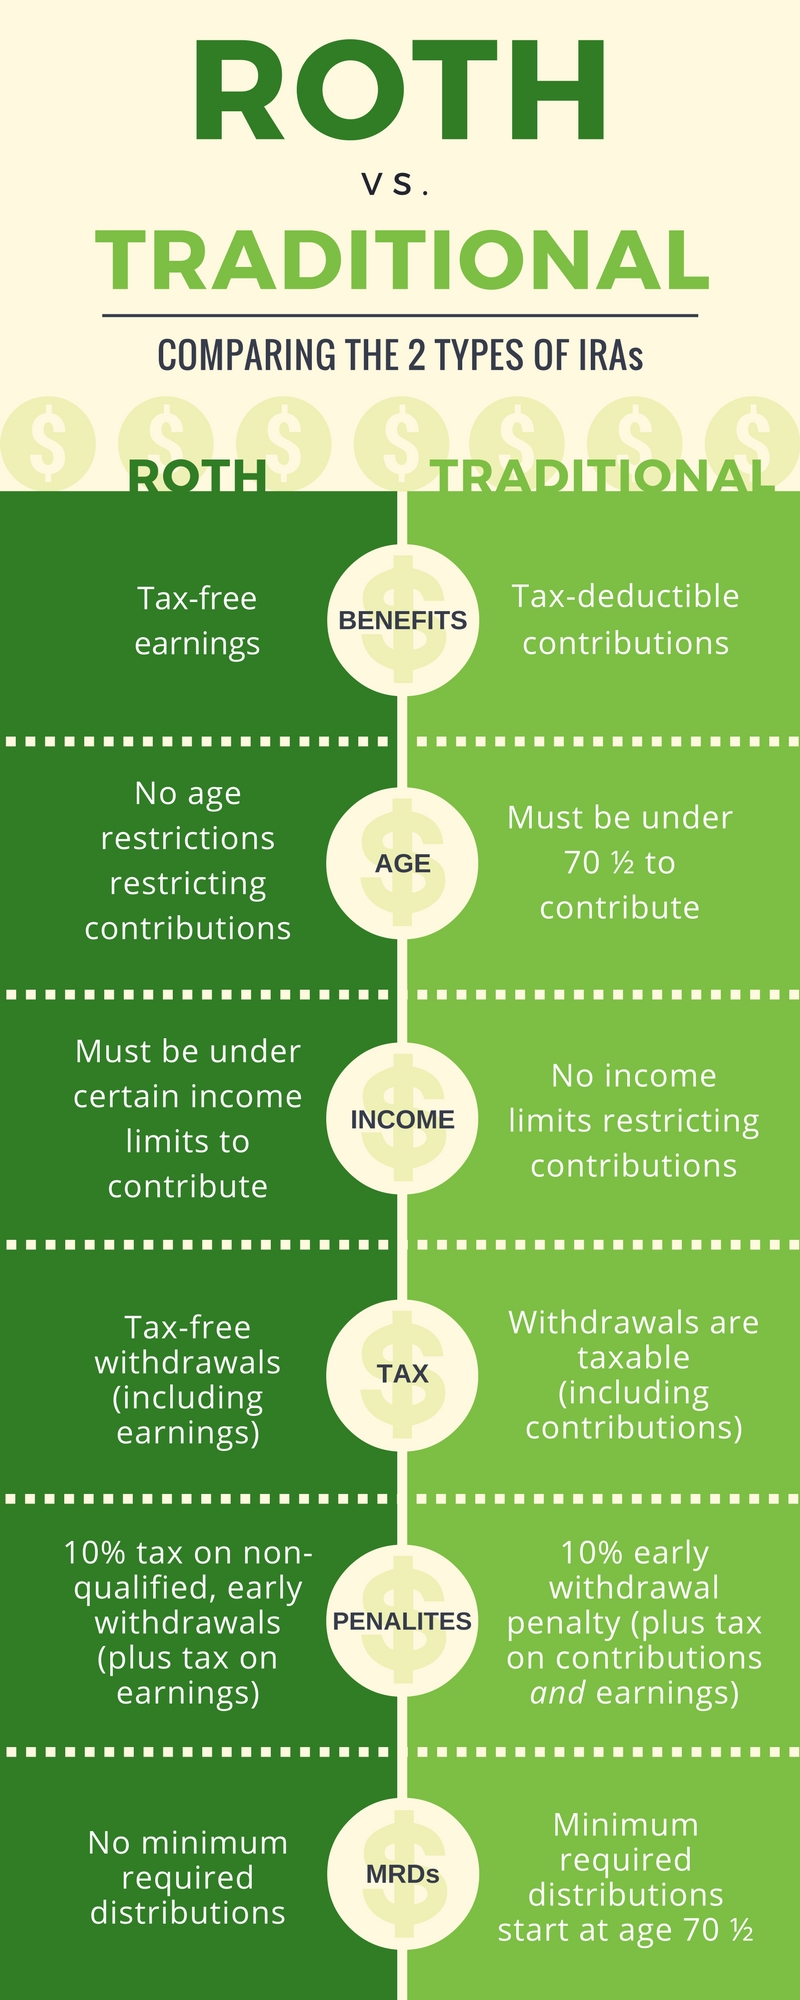
A defining feature of the Traditional IRA is the ability to make pre-tax contributions. For eligible individuals, these contributions are tax-deductible in the year they are made, effectively reducing taxable income. This immediate tax benefit is a powerful incentive, particularly for those in higher tax brackets, offering a tangible return on investment from day one. Modern financial planning software and online tax preparation services leverage this feature, using sophisticated algorithms to calculate the exact tax savings based on an individual’s income, filing status, and other deductions. These digital tools provide real-time estimates of tax implications, allowing investors to dynamically adjust contributions to maximize their current year’s tax advantage. The integration of payroll systems with automated contribution setups further streamlines this process, allowing for seamless, recurring investments that harness the power of dollar-cost averaging and immediate tax relief without constant manual intervention.
Tax-Deferred Growth and Future Planning
Another critical innovation of the Traditional IRA lies in its tax-deferred growth mechanism. Investments within the account grow without being subject to annual taxation on capital gains or dividends. This allows for compounding returns to accelerate significantly over decades, as earnings are reinvested without being eroded by yearly tax obligations. Taxation only occurs when distributions are taken in retirement, at which point the entire withdrawal (contributions and earnings) is typically taxed as ordinary income. This design implicitly assumes that an individual will be in a lower tax bracket during retirement than during their peak earning years, an assumption that modern predictive analytics and financial modeling software help investors assess. These sophisticated digital platforms can project future income streams, estimate potential retirement tax brackets, and model various investment growth scenarios to help individuals optimize their deferral strategy. They provide clear visualizations of how tax deferral enhances wealth accumulation over time, illustrating the long-term compounding benefits that might be less apparent with manual calculations.
The Role of Technology in Managing Distributions
The distribution phase of a Traditional IRA, particularly the management of required minimum distributions (RMDs) starting at age 73, further highlights the utility of financial technology. Calculating RMDs, which are based on factors like age, account balance, and life expectancy, can be complex. However, advanced financial planning software and dedicated investment platforms automate these calculations, sending alerts and guiding account holders through the withdrawal process to avoid penalties. Furthermore, these platforms can integrate with broader financial plans, optimizing withdrawal strategies across multiple retirement accounts (e.g., 401(k)s, other IRAs) to minimize overall tax liability in retirement. AI-driven advisory services can even suggest optimal withdrawal sequences and timing, taking into account prevailing tax laws, market conditions, and an individual’s specific financial needs, demonstrating how technology transforms what was once a cumbersome compliance task into a streamlined, optimized financial strategy.
Roth IRAs: A Forward-Thinking Approach to Tax-Free Income
The Roth IRA represents a profound innovation in retirement savings, offering a fundamentally different tax treatment compared to its traditional counterpart. Its “pay taxes now, enjoy tax-free later” model appeals to a forward-thinking investor, confident in future tax rates or seeking ultimate flexibility in retirement. This innovative structure, too, is made more accessible and potent through the application of contemporary technology.
Post-Tax Contributions and Long-Term Advantages
Unlike Traditional IRAs, contributions to a Roth IRA are made with after-tax dollars, meaning they are not tax-deductible in the year they are made. While this foregoes an immediate tax break, it unlocks a powerful long-term advantage: qualified withdrawals in retirement are entirely tax-free. This characteristic is particularly appealing to younger investors or those who anticipate being in a higher tax bracket during retirement than during their working years. Advanced financial planning tools and online calculators are instrumental in illustrating this long-term benefit. They can project decades into the future, comparing the cumulative tax savings of a Roth IRA against a Traditional IRA under various tax rate assumptions. AI-powered advisory services can help individuals, especially those with fluctuating incomes or complex financial situations, determine if their current or future tax bracket makes a Roth IRA the more advantageous choice, considering factors like income limits for direct contributions and the possibility of backdoor Roth conversions, which themselves are an innovative workaround facilitated by financial technology.
Tax-Free Withdrawals in Retirement
The crowning jewel of the Roth IRA is the prospect of completely tax-free withdrawals in retirement, provided certain conditions are met (the account must be open for at least five years and the account holder must be at least 59½, disabled, or using the funds for a first-time home purchase). This tax-free income stream provides immense peace of mind and simplifies retirement budgeting. It also acts as an innovative hedge against future tax rate increases, a significant concern in an era of unpredictable fiscal policy. Financial modeling software can simulate different future tax environments, demonstrating the value of tax-free income in scenarios where general tax rates are higher. Furthermore, for those managing multiple retirement accounts, digital wealth management platforms can optimize withdrawal strategies, prioritizing Roth withdrawals to maintain lower taxable income in retirement, thus potentially reducing Medicare premiums or avoiding higher tax brackets on other income sources. This strategic flexibility, maximized by intelligent software, is a key innovation for comprehensive retirement planning.
Flexibility and Estate Planning in the Digital Age
Beyond its tax-free withdrawals, the Roth IRA offers unparalleled flexibility that underscores its innovative design, particularly when viewed through the lens of modern digital estate planning. There are no required minimum distributions (RMDs) for the original owner, allowing funds to continue growing tax-free for their entire lifetime. This feature makes it an exceptional tool for estate planning, as funds can be passed on to beneficiaries tax-free. Digital estate planning platforms and legal tech solutions are increasingly integrating with financial account management, allowing for seamless designation of beneficiaries and ensuring that the tax-free legacy of a Roth IRA is preserved and easily transferable. Furthermore, the ability to withdraw contributions (not earnings) tax-free and penalty-free at any time offers a unique emergency fund option, providing a liquidity safety net that few other retirement vehicles can match. This combination of long-term growth, tax-free distributions, and accessible emergency funds, all managed and optimized through advanced digital interfaces, solidifies the Roth IRA’s position as a truly innovative financial instrument.
Strategic Selection: Leveraging Technology for Optimal Choice
Choosing between a Roth and Traditional IRA is a critical decision in retirement planning, with implications spanning decades. The complexity of this choice, which depends on numerous individual financial factors and assumptions about future tax environments, is where technology and innovation truly shine, transforming it from a speculative guess into an informed, data-driven strategy.
Financial Planning Software and Predictive Analytics
Modern financial planning software has revolutionized the decision-making process for IRAs. These advanced platforms utilize predictive analytics and sophisticated algorithms to analyze a user’s current income, tax bracket, anticipated career trajectory, projected retirement age, and desired lifestyle. By inputting these variables, the software can model various scenarios, illustrating the long-term financial impact of choosing a Roth versus a Traditional IRA. It can forecast cumulative tax savings, project account balances under different investment growth rates, and even simulate the effects of future tax law changes. This level of personalized, data-driven insight, accessible through user-friendly digital dashboards, empowers individuals to make choices that are precisely tailored to their unique circumstances, moving beyond generic advice to truly optimized strategies.
Automated Investment Platforms and Robo-Advisors
The advent of automated investment platforms, commonly known as robo-advisors, has democratized access to professional-grade portfolio management for both Roth and Traditional IRAs. These platforms leverage algorithms to create diversified portfolios based on an individual’s risk tolerance and financial goals, then automatically rebalance them as market conditions change. For IRA holders, this means sophisticated investment strategies, previously only available to clients of high-cost human advisors, are now accessible at a fraction of the cost. Robo-advisors often integrate tax-loss harvesting capabilities (relevant for taxable accounts, but the underlying tech can inform IRA management), and can dynamically adjust investment mixes within an IRA to align with evolving market trends or life events. This innovative approach to investment management ensures that whether one chooses a Roth or Traditional IRA, the underlying assets are managed efficiently and optimally through intelligent automation.
Adapting to Evolving Tax Codes with Digital Tools
Tax codes are not static; they evolve, often with significant implications for retirement planning. This dynamic environment makes the initial choice between Roth and Traditional IRAs challenging, but modern digital tools provide innovative ways to adapt. Financial planning software can be updated in real-time to reflect new tax laws, allowing users to rerun projections and reassess their strategy. Furthermore, these platforms can highlight opportunities for strategies like Roth conversions, where funds from a Traditional IRA are converted into a Roth IRA. While such conversions incur a tax liability in the year of conversion, digital tools can calculate the optimal amount to convert each year to stay within desired tax brackets, transforming a complex maneuver into a manageable, strategically timed action. This ability to continuously adapt and optimize IRA strategies in response to legislative changes is a testament to the powerful synergy between financial innovation and technological advancement.
The Future of Retirement Planning: Integration with Broader Tech Innovations
The evolution of Roth and Traditional IRAs is far from complete. As technology continues its rapid advancement, these foundational retirement vehicles will undoubtedly integrate with even broader technological innovations, offering unprecedented levels of personalization, security, and strategic foresight.
AI-Driven Personalization
The future of IRA management will likely see even deeper integration of artificial intelligence, moving beyond current robo-advisor capabilities to truly personalized financial ecosystems. AI will analyze not just financial data but also behavioral patterns, spending habits, health data (with consent), and even macroeconomic trends to provide hyper-personalized recommendations for IRA contributions, investment choices, and withdrawal strategies. Imagine an AI that not only suggests whether a Roth or Traditional IRA is better for you but also predicts potential future life events (e.g., career changes, family expansions) and proactively adjusts your IRA strategy in real-time. This level of predictive personalization, driven by machine learning, will transform retirement planning from a periodic review into a continuously optimized, dynamic process.
Blockchain for Secure Record-Keeping
While still in nascent stages for mainstream financial applications, blockchain technology holds immense potential for enhancing the security, transparency, and efficiency of retirement accounts like IRAs. Decentralized ledger technology could provide an immutable record of all contributions, transactions, and ownership, significantly reducing the risk of fraud and simplifying auditing processes. Smart contracts could automate compliance with RMDs or other account rules, ensuring timely and accurate execution without manual intervention. The inherent security features of blockchain could offer an unparalleled level of protection for sensitive financial data, addressing growing concerns about cybersecurity in an increasingly digital world. This innovative application of blockchain could further streamline the administrative aspects of IRAs, freeing up resources for more advanced financial planning.
The Blurring Lines of Investment and Lifestyle Management
Looking ahead, retirement planning, including the management of Roth and Traditional IRAs, will likely become more seamlessly integrated with broader lifestyle management platforms. Imagine an integrated app that not only tracks your IRA performance but also analyzes your daily spending, health metrics, and even travel plans to offer holistic financial advice. This platform could suggest optimal spending reductions to increase IRA contributions, recommend health investments to extend working years, or even tailor investment choices within your IRA to align with your personal values and sustainable investment preferences. This blurring of lines, facilitated by advanced data analytics and interoperable digital ecosystems, represents the ultimate innovation in making retirement planning an intuitive, integrated part of daily life, ensuring Roth and Traditional IRAs remain central to a well-managed financial future.