
New York City stands as a global beacon of commerce, culture, and increasingly, technological innovation. Within this vibrant ecosystem, the intricate web of sales tax regulations plays a pivotal role, influencing everything from daily consumer purchases to the operational strategies of cutting-edge tech enterprises. For businesses engaged in the rapidly evolving drone and flight technology sector, understanding the nuances of New York City sales tax is not merely an administrative chore but a critical component of strategic planning and sustainable growth, particularly concerning the unique challenges and opportunities presented by innovation.
Understanding New York City Sales Tax Fundamentals
At its core, New York City sales tax is a consumption tax levied on the sale of various goods and services within the city limits. It’s a combined rate, incorporating both New York State and Metropolitan Commuter Transportation District (MCTD) components, along with a distinct New York City portion. This layered structure creates a complex landscape that tech companies, especially those dealing with innovative hardware, software, and services related to drones, must meticulously navigate.
Standard Rate and Exemptions Relevant to Tech
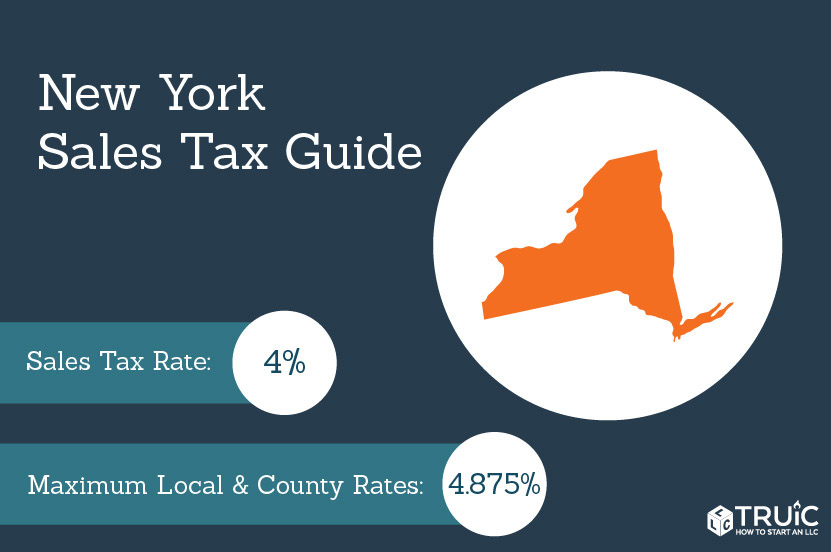
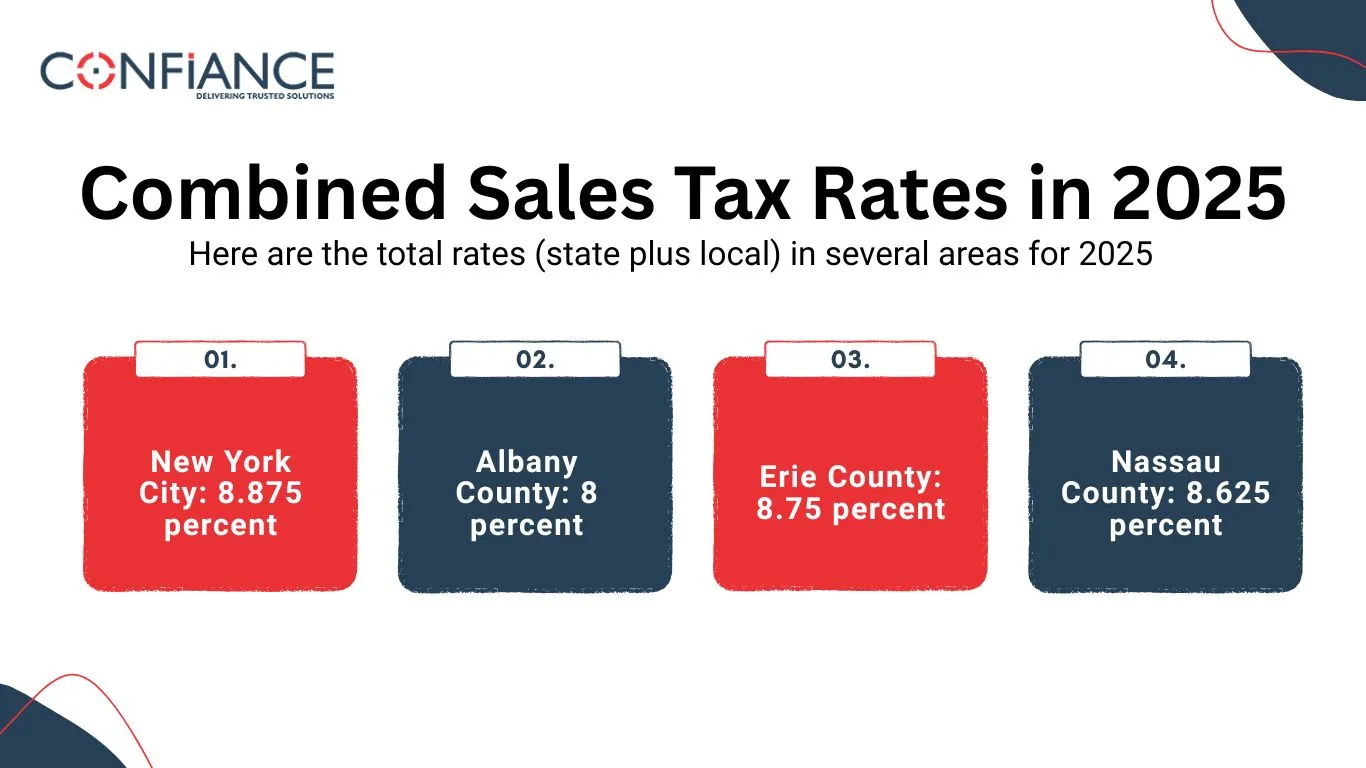
As of the current period, the combined sales tax rate in New York City is 8.875%. This comprises the 4% New York State rate, a 0.375% MCTD surcharge, and a 4.5% New York City local tax. While this rate generally applies to tangible personal property sold at retail, the application to technology-driven products and services often involves intricate distinctions.
Certain exemptions exist, though they are not always straightforward for the dynamic tech sector. For instance, some services may be exempt, while others are taxable. The critical challenge for drone technology innovators lies in classifying their offerings. Is an autonomous flight system a piece of tangible hardware, taxable? Is the AI-powered mapping software a taxable “prewritten software,” or a non-taxable “custom software service”? The distinction often determines tax liability and can significantly impact pricing strategies and competitive positioning. Research and development activities, while crucial for innovation, generally do not incur sales tax on the cost of the R&D itself, but components purchased for R&D might. However, if the output of R&D is a tangible product sold, that sale would be taxable.
Services vs. Tangible Personal Property
The differentiation between services and tangible personal property is perhaps the most significant area of complexity for drone-related tech and innovation. Generally, New York sales tax applies to tangible personal property. Many services are exempt, but there are specific categories of taxable services, such as installation services, repair services, and certain information services.
Consider a company developing advanced drone technology:
- Sale of a drone (hardware): Clearly tangible personal property and subject to sales tax.
- Subscription to AI-driven flight planning software (prewritten): Often considered tangible personal property in New York, even if delivered electronically, and thus taxable.
- Custom development of a unique autonomous flight algorithm for a client: This might be classified as a non-taxable service, especially if the software is developed specifically for one client and is not “prewritten.”
- Drone pilot training services: Generally considered a non-taxable educational service.
- Data analysis service from drone-collected imagery: If the output is a tangible report or a prewritten software application, it could be taxable. If it’s pure consulting or analysis without a tangible product, it might be exempt.
The highly integrated nature of modern drone technology – combining sophisticated hardware, embedded software, cloud-based services, and data analytics – blurs these lines considerably, demanding meticulous interpretation of tax law and, often, expert guidance.
Sales Tax Impact on Drone Technology and Innovation
The tax treatment of various components and services within the drone tech sphere can significantly influence investment, development cycles, and market adoption. For companies pioneering in areas like AI-powered autonomous flight or advanced remote sensing, these tax considerations are baked into their financial models from the outset.
AI Follow Mode and Autonomous Flight Systems: Software vs. Hardware
The development of AI-driven functionalities, such as “follow me” modes or fully autonomous navigation systems, exemplifies the software-hardware nexus in drone technology. When an AI system is embedded directly into a drone’s hardware and sold as an integral unit, the entire product is typically taxed as tangible personal property. However, if the AI functionality is delivered as a separate software license, especially a cloud-based subscription, the tax implications can shift.
New York’s rules on software are critical here. “Prewritten software” (canned software) is generally taxable, even if delivered electronically. “Custom software,” developed for a specific client, is generally considered a non-taxable service. The challenge arises with hybrid models, where prewritten software is heavily customized or where a software service includes access to extensive cloud infrastructure. Businesses must carefully document the nature of their software offerings to ensure accurate tax compliance, as misclassification can lead to significant liabilities or competitive disadvantages if products are overtaxed.
Tax Considerations for Drone Mapping and Remote Sensing Services
Drone mapping and remote sensing are increasingly vital applications, offering precise data for industries ranging from construction and agriculture to environmental monitoring. These services typically involve several components: the flight operation, data collection, data processing, and the delivery of insights or reports.
- Drone flight operation: If a company provides a drone flight service to collect data, this service itself is generally not subject to sales tax, assuming it doesn’t involve the transfer of tangible personal property.
- Data processing and analysis: If the outcome of this processing is a tangible output like a physical map, a CD-ROM with data, or access to a prewritten online mapping application, it could be taxable. However, if the service results in pure consulting advice or the delivery of custom-developed digital insights without a tangible medium or prewritten software component, it may be exempt.
- Sales of Raw Data: Selling raw drone-collected data, depending on its format and delivery method, could also fall under taxable tangible personal property if delivered via a physical medium or as access to prewritten digital content.
Innovators in this space must dissect each stage of their service delivery to determine taxability, especially as the industry moves towards more integrated “data-as-a-service” models that blur the lines between traditional services and software products.
Investment in R&D and Tax Incentives (or lack thereof)
New York State offers various tax credits and incentives, some of which are relevant to technology companies, such as the R&D tax credit. However, these generally apply to income tax or corporate franchise tax, not directly to sales tax. While the costs incurred during R&D (e.g., purchasing components for a prototype) might be subject to sales tax at the time of purchase, the R&D activity itself is typically not a taxable sale for sales tax purposes.
The absence of direct sales tax exemptions for R&D purchases in many cases means that companies engaged in heavy prototyping and component testing face upfront tax costs that can impact their cash flow. This indirectly affects the innovation cycle, as businesses must account for sales tax on numerous inputs before a taxable output (a final product sale) even materializes. A more favorable sales tax environment for R&D inputs could potentially stimulate more rapid innovation within the drone sector by reducing immediate costs.
Navigating Sales Tax for Drone Startups and Manufacturers in NYC
For drone startups and established manufacturers operating within New York City, effective sales tax management is paramount for financial health and compliance. This involves strategic planning for procurement, sales, and understanding nexus requirements.
Procurement of Components and Raw Materials
Manufacturers producing drones or advanced drone components (e.g., specialized sensors, custom flight controllers) purchase numerous raw materials and sub-components. New York sales tax generally applies to these purchases unless a specific exemption applies. A key exemption is for items purchased for resale. If a component is purchased and then incorporated into a final product that will be sold, the manufacturer can often provide a resale certificate to the supplier, thereby avoiding sales tax on that input purchase. This is crucial for maintaining competitive pricing and avoiding cascading taxes.
However, items purchased for use in the manufacturing process that do not become part of the final product (e.g., machinery, tools, office supplies) are generally subject to sales tax. Startups must be diligent in classifying their purchases to properly apply resale certificates where applicable and accrue use tax where sales tax was not collected by the vendor.
Sales of Innovative Drone Products and Solutions
When a New York City-based drone company sells its innovative products, whether complete drones, specialized payloads, or software licenses, it must collect sales tax from its customers if the sale is taxable and the customer is located in New York. This requires having robust systems to calculate and collect the correct combined city and state rate. For businesses selling a mix of tangible goods and services, their point-of-sale or invoicing systems must be sophisticated enough to differentiate taxable from non-taxable items. Clear articulation on invoices regarding what is being sold (e.g., “drone hardware,” “software license,” “consulting service”) is vital for both compliance and customer clarity.
Cross-Jurisdictional Sales and Remote Seller Nexus
The digital nature of much of modern tech, including drone software and services, often involves sales to customers outside New York City or even New York State. This brings into play the complex concept of “nexus.” Nexus determines where a business has a sufficient presence to be required to collect sales tax. For a New York City-based company, sales to customers outside New York State are generally not subject to New York sales tax, but they might create sales tax obligations in the customer’s state if the seller has nexus there.
Conversely, drone tech companies based outside New York but selling into New York City must understand New York’s remote seller nexus laws. These include economic nexus thresholds (e.g., a certain volume of sales or transactions into the state) which can obligate out-of-state sellers to register and collect New York sales tax. As drone tech becomes more globally integrated, understanding these cross-jurisdictional rules is vital for expanding businesses.
Economic Implications for New York City’s Tech Ecosystem
The specific application and enforcement of sales tax regulations in New York City significantly impact its attractiveness as a hub for drone technology and innovation. Tax policy can act as either a catalyst or an impediment to growth within this nascent yet rapidly expanding sector.
Fostering or Hindering Drone Innovation
A sales tax regime that is overly burdensome or ambiguous, particularly regarding the distinction between taxable products and non-taxable services for cutting-edge technologies, can deter innovation. Startups with limited resources may find the compliance costs daunting, potentially shifting their operations to areas with more favorable tax environments. Conversely, a clear, pragmatic, and perhaps incentivized sales tax framework could encourage drone tech companies to establish and expand their R&D and manufacturing operations within New York City, fostering job creation and economic growth. The classification of software, particularly custom AI and autonomous systems, is a critical area where clearer guidance or specific exemptions could significantly boost the local tech scene.
The Role of Tax Policy in Attracting Tech Businesses
New York City actively competes with other global tech hubs for talent and investment. Its tax policies, including sales tax, are a factor in this competition. While property taxes, income taxes, and corporate taxes often garner more attention, the daily impact of sales tax on procurement, pricing, and revenue recognition for a tech business can be substantial. Policies that support emerging technologies by simplifying tax compliance, offering targeted exemptions for innovative R&D inputs, or providing clarity on evolving service models could enhance New York City’s appeal to drone manufacturers, software developers, and service providers. This would signal a supportive environment for businesses at the forefront of aerospace and AI innovation.
Future Outlook for Drone Sector Taxation
As drone technology continues to evolve at an unprecedented pace, so too must the regulatory and taxation frameworks. New York City faces the ongoing challenge of adapting its sales tax laws to encompass new business models, such as drone-as-a-service, advanced urban air mobility systems, and highly customized AI solutions. Proactive engagement between tax authorities and the tech industry could lead to more nuanced and equitable tax policies that recognize the unique characteristics of innovation. The future outlook suggests a growing need for specific guidelines addressing the complex interplay of hardware, software, and services in the drone sector to ensure both fair taxation and continued economic dynamism within New York City’s vibrant tech landscape.