
In the intricate world of finance, the term “instrument” carries a fundamental and far-reaching significance. It serves as the bedrock upon which financial transactions, investments, and risk management strategies are built. Far from being a mere technicality, understanding financial instruments is crucial for anyone seeking to navigate the complexities of markets, whether as an individual investor, a corporate treasurer, or a financial professional. Essentially, a financial instrument is a monetary contract between parties. It can be created, traded, modified, and settled. These contracts are typically negotiable and represent a claim to the payment of money or to some other form of value. They are the building blocks of the financial system, enabling the flow of capital, the transfer of risk, and the facilitation of economic growth.

The diversity of financial instruments is vast, reflecting the myriad needs and objectives of market participants. They range from simple, straightforward agreements to highly complex, derivative-based contracts. This diversity allows for a wide spectrum of investment opportunities, risk mitigation tools, and financing mechanisms. In essence, financial instruments are the standardized, quantifiable means by which financial value is exchanged and managed. They are the tangible manifestations of financial obligations and entitlements.
Types of Financial Instruments
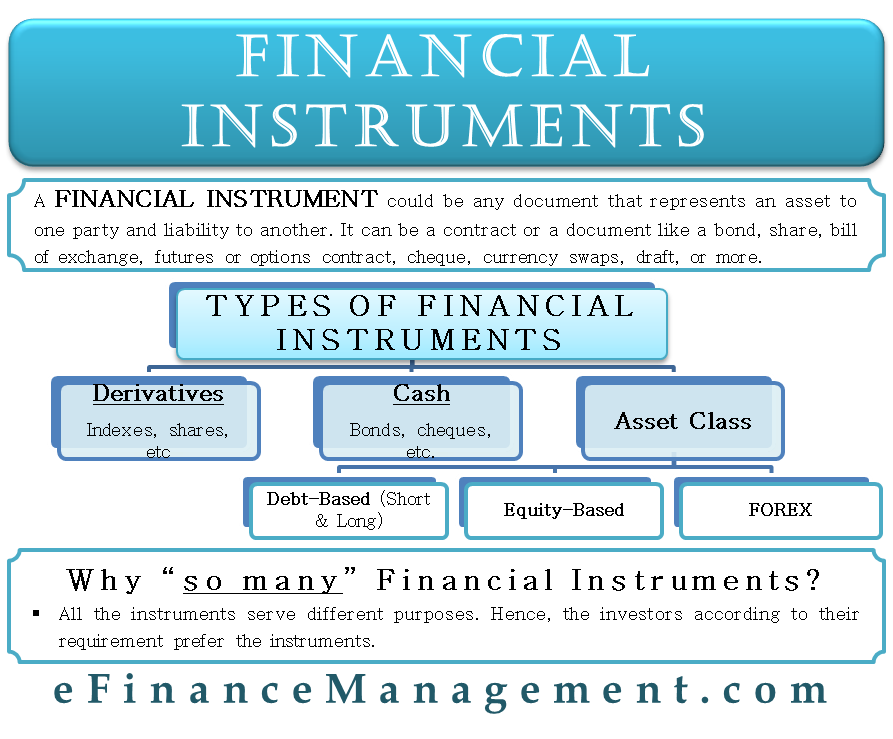
The landscape of financial instruments can be broadly categorized based on their underlying characteristics and the nature of the claims they represent. This classification helps in understanding their role within the financial system and how they are utilized by different market participants.
Debt Instruments
Debt instruments represent a loan made by an investor to a borrower. The borrower promises to repay the principal amount of the loan on a specified maturity date, along with periodic interest payments. These instruments are characterized by their fixed or variable repayment schedules and the seniority of the claim they represent.
Bonds
Bonds are perhaps the most common type of debt instrument. They are issued by governments, municipalities, and corporations to raise capital. When you buy a bond, you are essentially lending money to the issuer. In return, the issuer agrees to pay you periodic interest payments (coupons) and to repay the principal amount (face value) on the maturity date. The risk associated with bonds varies greatly depending on the creditworthiness of the issuer. Government bonds are generally considered very safe, while corporate bonds carry varying degrees of risk.
Loans
Loans, in their various forms, are also debt instruments. These can range from personal loans and mortgages to complex syndicated loans arranged for large corporations. The key feature is the borrower’s obligation to repay the borrowed amount with interest over a defined period.
Treasury Bills (T-Bills)
Treasury Bills are short-term debt obligations issued by governments, typically with maturities of one year or less. They are considered among the safest investments due to the backing of the issuing government and are often used as a benchmark for interest rates.
Equity Instruments
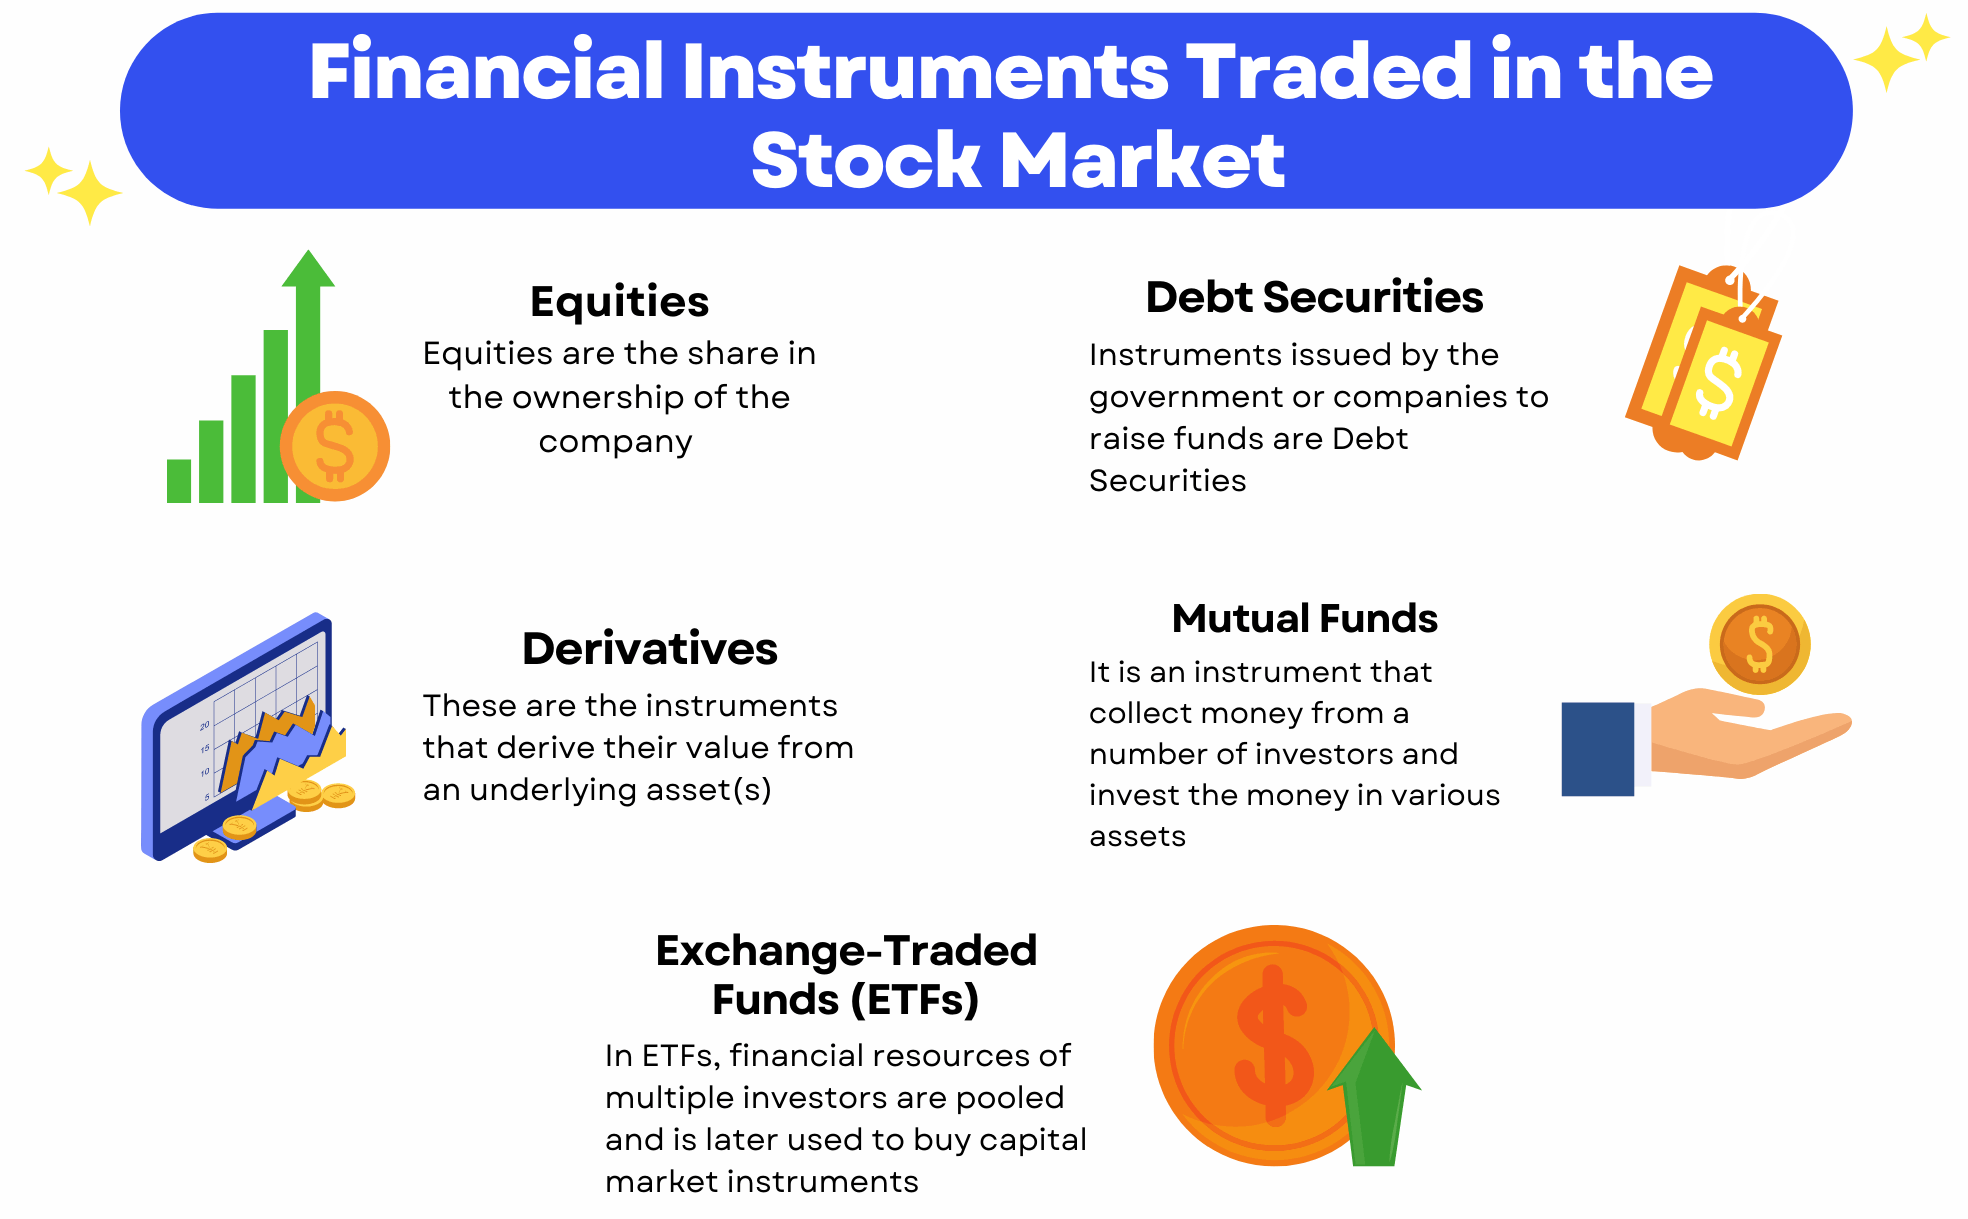
Equity instruments represent ownership in a company. Holders of equity instruments, known as shareholders or stockholders, have a claim on the company’s assets and earnings. Unlike debt holders, equity holders do not have a guaranteed return. Their returns are dependent on the company’s profitability and performance.
Common Stock
Common stock is the most prevalent form of equity instrument. When you own shares of common stock in a company, you are a part-owner of that company. You may receive dividends (a portion of the company’s profits distributed to shareholders) and can profit from any increase in the stock’s market price. However, if the company performs poorly or goes bankrupt, the value of your investment can significantly decrease or become worthless.
Preferred Stock
Preferred stock offers a hybrid form of ownership, combining features of both debt and equity. Preferred stockholders typically receive fixed dividends, which are paid before any dividends are distributed to common stockholders. They also generally have a higher claim on company assets in the event of liquidation compared to common stockholders. However, they usually do not have voting rights.
Derivatives
Derivatives are financial instruments whose value is derived from an underlying asset, index, or rate. These instruments are often used for hedging (managing risk) or speculation. They allow parties to gain exposure to the price movements of an asset without directly owning it.
Options
An option contract gives the buyer the right, but not the obligation, to buy or sell an underlying asset at a specified price (strike price) on or before a certain date (expiration date). There are two main types: call options (the right to buy) and put options (the right to sell). Options can be highly leveraged, meaning a small price movement in the underlying asset can lead to a significant profit or loss.
Futures Contracts
A futures contract is a standardized legal agreement to buy or sell a particular commodity or financial instrument at a predetermined price at a specified time in the future. Futures contracts are traded on exchanges and are often used by producers and consumers to hedge against price fluctuations.
Swaps
Swaps are derivative contracts where two parties agree to exchange streams of cash flows over a specified period. The most common types are interest rate swaps (exchanging fixed-rate payments for floating-rate payments) and currency swaps (exchanging principal and interest payments in one currency for those in another).
Other Financial Instruments
Beyond these primary categories, there are numerous other financial instruments that serve specific purposes in the financial markets.
Mutual Funds
A mutual fund is an investment vehicle that pools money from many investors to purchase a diversified portfolio of stocks, bonds, or other securities. This diversification can help reduce risk compared to investing in individual securities. Investors in mutual funds own shares of the fund, not the underlying assets directly.
Exchange-Traded Funds (ETFs)
ETFs are similar to mutual funds in that they pool investor money and hold a basket of assets. However, ETFs are traded on stock exchanges like individual stocks, offering more trading flexibility. Many ETFs are designed to track a specific index, such as the S&P 500.
Certificates of Deposit (CDs)
Certificates of Deposit are time deposits offered by banks. They typically offer a fixed interest rate for a specified term, with penalties for early withdrawal. CDs are generally considered low-risk investments.
Functions and Significance of Financial Instruments
Financial instruments are not merely abstract contracts; they are vital components that enable the functioning of modern economies. Their primary roles include facilitating capital raising, managing risk, enabling investment, and providing liquidity.
Capital Raising
For businesses and governments, financial instruments are the primary means of raising capital. By issuing debt (bonds, loans) or equity (stocks), entities can secure the funds necessary for expansion, research and development, infrastructure projects, and operational expenses. This capital infusion is essential for economic growth and job creation.
Risk Management
Derivatives, in particular, play a crucial role in risk management. Companies can use futures, options, and swaps to hedge against adverse movements in interest rates, exchange rates, or commodity prices. For instance, an exporter expecting payment in a foreign currency can use a futures contract to lock in an exchange rate, protecting themselves from potential currency depreciation.
Investment and Wealth Creation
For individuals and institutions, financial instruments offer a diverse range of investment opportunities. They allow investors to participate in the growth of companies, earn interest on their savings, and potentially profit from market fluctuations. The ability to invest in various instruments allows for the creation of diversified portfolios tailored to different risk appetites and return objectives, fostering wealth accumulation over time.
Facilitating Liquidity
Financial markets, underpinned by tradable financial instruments, provide liquidity. This means that assets can be easily bought and sold without significant price impact. For investors, this liquidity ensures they can access their capital when needed. For the economy, it ensures that capital can flow efficiently to where it is most productive.
The Role of Regulation and Innovation
The creation, trading, and management of financial instruments are heavily regulated to ensure market integrity, protect investors, and maintain financial stability. Regulatory bodies establish rules regarding disclosure, transparency, trading practices, and capital requirements.
Innovation in financial technology (FinTech) is continuously reshaping the landscape of financial instruments. The development of new platforms, algorithms, and digital currencies is leading to the creation of novel instruments and more efficient ways to trade and manage existing ones. This includes advancements in areas like algorithmic trading, decentralized finance (DeFi), and the tokenization of traditional assets, all of which are likely to influence the future evolution of financial instruments.
In conclusion, financial instruments are the fundamental building blocks of the financial system. They are the contracts that define monetary relationships, facilitate the flow of capital, and enable the management of risk. From simple savings accounts to complex derivatives, each instrument serves a specific purpose, contributing to the dynamism and complexity of global finance. Understanding their nature, types, and functions is therefore indispensable for anyone seeking to engage effectively with the financial world.