
Understanding the intricacies of health insurance is paramount in navigating the complex landscape of personal healthcare and financial well-being. Among the various types of plans available, high-deductible health plans (HDHPs) have gained significant traction, offering a distinct approach to coverage. This article delves into the core definition of a high-deductible insurance plan, its defining characteristics, and the implications for individuals seeking to manage their healthcare expenses.
Defining the High Deductible Health Plan
At its essence, a high-deductible health plan is a type of health insurance policy characterized by a higher deductible amount compared to traditional health insurance plans. The deductible is the amount of money you, as the policyholder, must pay out-of-pocket for covered healthcare services before your insurance company begins to pay. In the context of HDHPs, this threshold is significantly elevated.
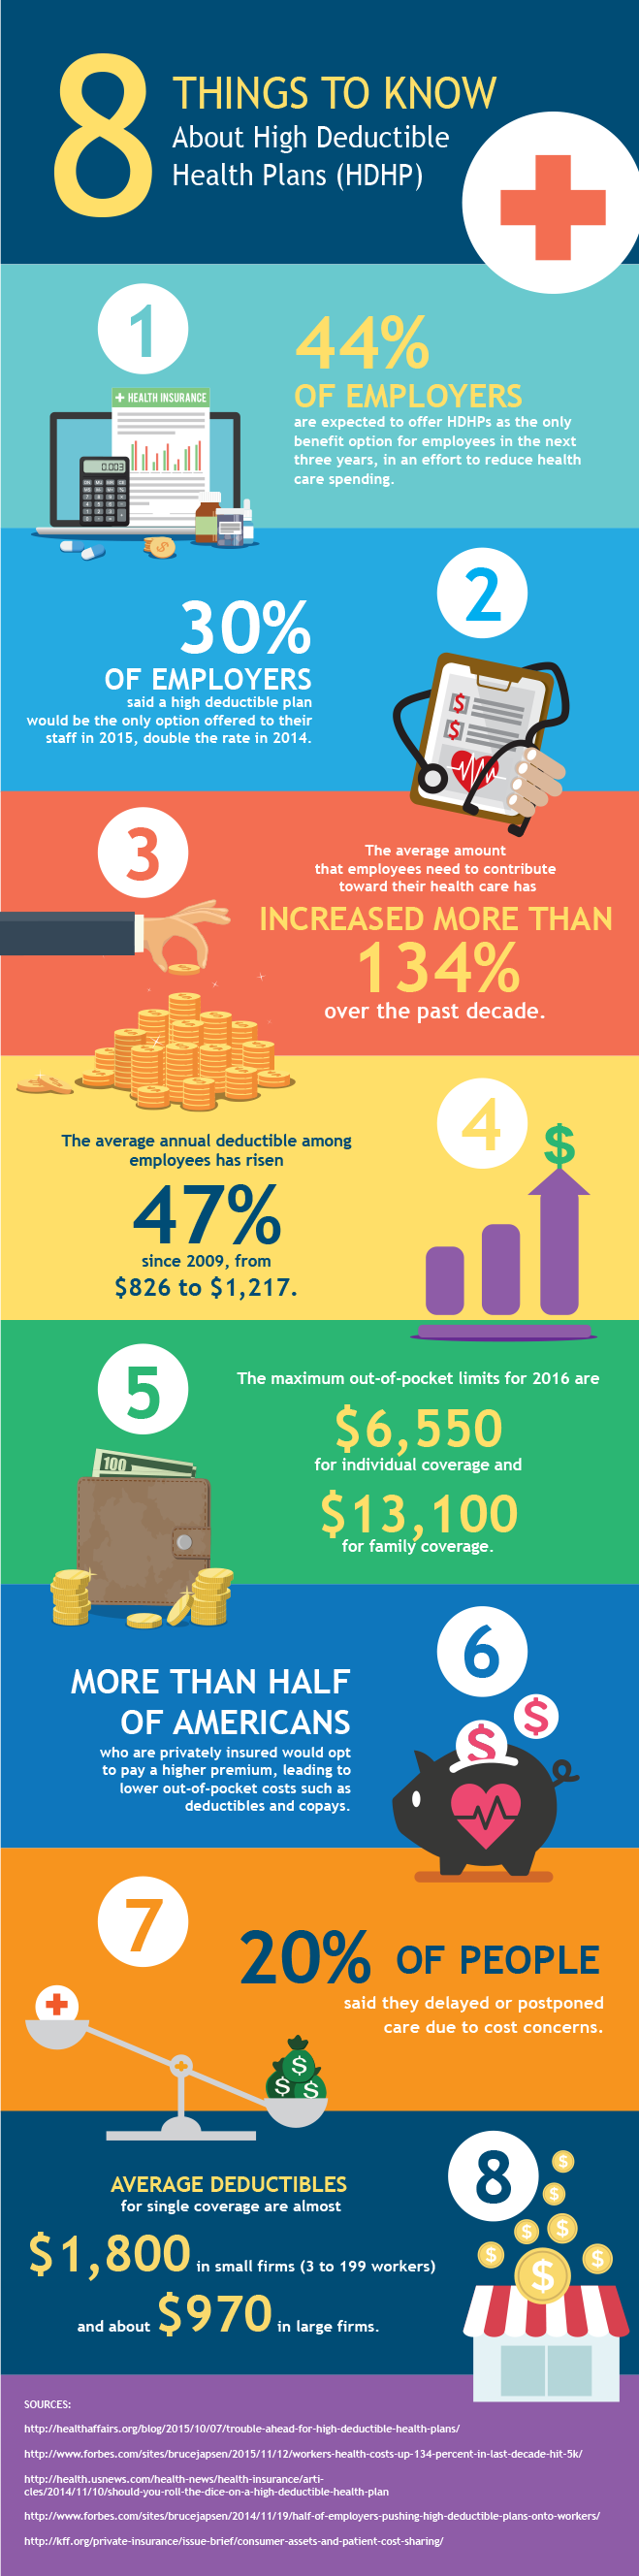
The U.S. Department of Health and Human Services (HHS) provides specific definitions for what constitutes a high-deductible health plan for both individuals and families. For 2023, a qualifying HDHP for an individual must have an annual deductible of at least $1,500 and an out-of-pocket maximum of no more than $7,500. For a family, the deductible must be at least $3,000, with an out-of-pocket maximum not exceeding $15,000. These figures are subject to change annually, typically adjusted for inflation.
It’s crucial to distinguish the deductible from other out-of-pocket costs. While the deductible is the initial amount you pay, other expenses like copayments (a fixed amount you pay for a covered healthcare service after you’ve paid your deductible) and coinsurance (your share of the costs of a covered healthcare service, calculated as a percentage of the allowed amount for the service) may also apply after the deductible has been met. However, HDHPs often have lower monthly premiums, which is a primary draw for many consumers.
Key Components of an HDHP
- Deductible: The fixed amount you pay for covered services before your insurance plan starts to pay. This is the defining feature of an HDHP.
- Out-of-Pocket Maximum: The absolute most you will have to pay for covered services in a plan year. Once you reach this limit, your health plan pays 100% of the covered healthcare costs for the rest of the plan year.
- Premium: The monthly amount you pay to have health insurance. HDHPs typically have lower monthly premiums than plans with lower deductibles.
The Appeal of High-Deductible Health Plans
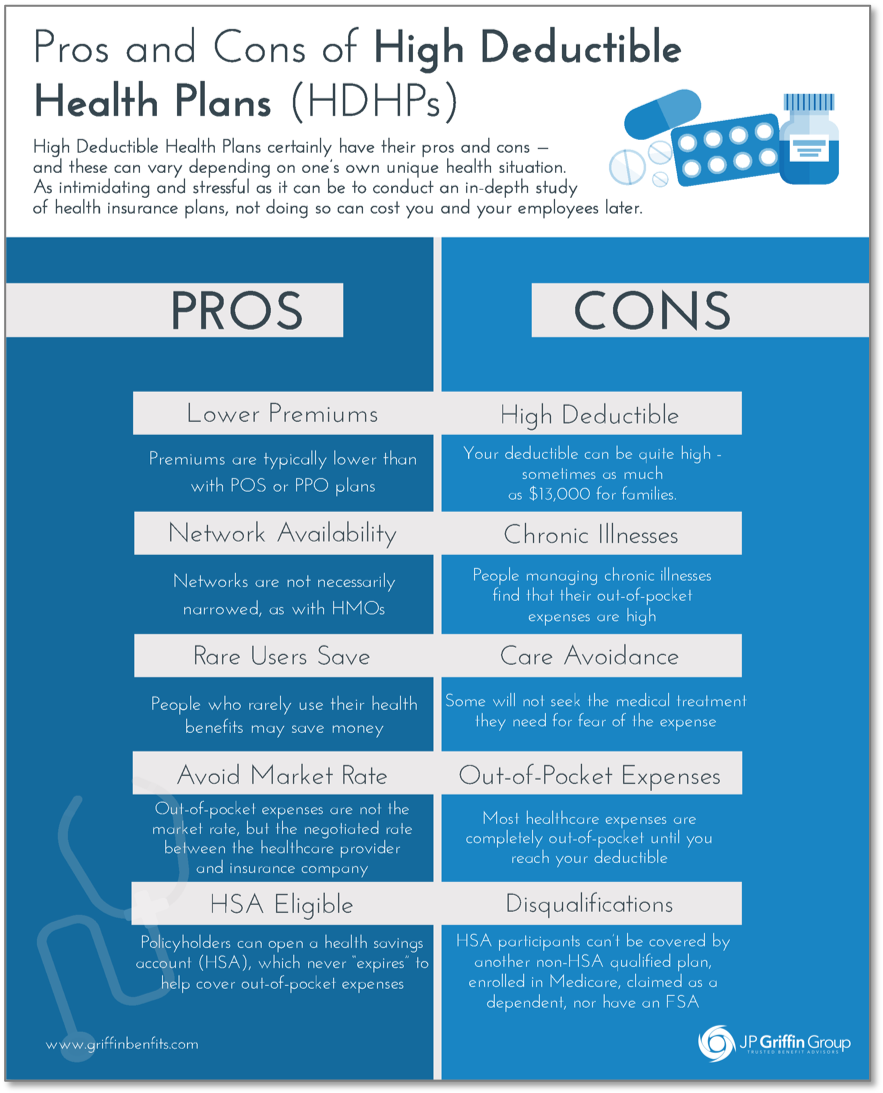
The primary allure of HDHPs for many individuals and families lies in their lower monthly premiums. For those who are generally healthy and do not anticipate frequent or extensive medical care, the savings on monthly premiums can be substantial. This makes HDHPs an attractive option for those looking to reduce their ongoing healthcare costs, especially when combined with other financial planning strategies.
Furthermore, HDHPs are often paired with a Health Savings Account (HSA). An HSA is a tax-advantaged savings account that individuals can use to pay for qualified medical expenses. Contributions to an HSA are tax-deductible, the money grows tax-free, and withdrawals for qualified medical expenses are also tax-free. This trifecta of tax benefits makes HSAs a powerful tool for managing healthcare costs, especially in conjunction with an HDHP. The ability to save pre-tax dollars for healthcare expenses can significantly offset the higher deductible.
Advantages of HDHPs
- Lower Monthly Premiums: Reduced ongoing cost of insurance coverage.
- Potential for Savings: For healthy individuals, the lower premiums can result in overall savings compared to plans with higher premiums and lower deductibles.
- Encourages Cost Consciousness: By requiring individuals to pay more out-of-pocket initially, HDHPs can encourage more thoughtful consideration of healthcare services and costs.
- Eligibility for HSAs: The tax advantages associated with HSAs can provide a significant financial benefit.
Who Benefits Most from an HDHP?
High-deductible health plans are not a one-size-fits-all solution. They are best suited for individuals and families who meet certain criteria.
The Healthy and Proactive Consumer
Individuals who are generally healthy and have predictable, low healthcare needs are prime candidates for HDHPs. If you rarely visit the doctor, have no chronic conditions requiring ongoing treatment, and do not anticipate significant medical procedures in the near future, the lower monthly premiums can offer substantial savings. This demographic can also leverage the HSA to save for future healthcare needs or even as a supplementary retirement savings vehicle due to its tax benefits.
The Savvy Financial Planner

Those who are disciplined with their finances and can comfortably afford to set aside funds to meet the deductible if necessary will find HDHPs more manageable. The ability to save for potential medical expenses in an HSA or a separate savings account provides a financial safety net. This proactive approach to financial planning ensures that the higher deductible doesn’t become a barrier to accessing necessary care.
Young Professionals and Small Business Owners
Younger individuals, who typically have fewer health issues, can benefit from the lower premiums of HDHPs, allowing them to allocate more of their income to other financial goals like saving for a home or investing. Similarly, small business owners looking to provide health benefits to their employees might find HDHPs a more cost-effective option, especially when bundled with HSAs, to control overall healthcare spending for the company.
Considerations and Potential Drawbacks of HDHPs
While HDHPs offer compelling advantages, it’s imperative to acknowledge their potential drawbacks and consider them carefully before enrollment.
The Risk of Unexpected Medical Expenses
The most significant concern with HDHPs is the potential for substantial out-of-pocket expenses if unexpected medical issues arise. A serious illness, a major accident, or the need for surgery can quickly deplete savings and result in significant financial strain if one is not adequately prepared to meet the high deductible. This can lead to difficult decisions about delaying or forgoing necessary medical treatment, which can have detrimental long-term health consequences.
Understanding Your Healthcare Needs
Thoroughly assessing your current and projected healthcare needs is crucial. This includes considering any chronic conditions, ongoing medications, potential for planned procedures, and family history of health issues. If you have significant or ongoing medical expenses, an HDHP might not be the most financially prudent choice, and a plan with a lower deductible and higher premium might offer better value by spreading costs more evenly throughout the year.
The Importance of an HSA
While not mandatory, enrolling in an HDHP without a paired HSA significantly diminishes its attractiveness. The tax advantages and savings potential of an HSA are integral to making the higher deductible more manageable. If you are not comfortable or able to contribute to an HSA, the financial burden of the deductible can be considerably higher.
Limitations on Provider Choice
While many HDHPs offer a broad network of providers, some plans might have narrower networks than traditional PPOs. It’s essential to verify if your preferred doctors and hospitals are covered within the plan’s network to avoid unexpected out-of-network charges, which can further increase out-of-pocket costs.
Navigating Your HDHP Options
Choosing the right health insurance plan is a critical decision that impacts both your health and your finances. For those considering a high-deductible health plan, a comprehensive understanding of its structure, benefits, and potential challenges is essential.
Step-by-Step Evaluation
- Assess Your Health Status: Honestly evaluate your current health, any pre-existing conditions, and your anticipated healthcare utilization for the coming year.
- Analyze Your Financial Situation: Determine your capacity to meet the deductible out-of-pocket if necessary and your ability to contribute consistently to an HSA.
- Compare Premiums and Deductibles: Weigh the monthly premium savings against the potential out-of-pocket liability.
- Investigate HSA Benefits: Understand the rules and benefits of a linked Health Savings Account.
- Verify Network Coverage: Ensure your preferred healthcare providers are within the plan’s network.
- Read the Fine Print: Familiarize yourself with all plan details, including copayments, coinsurance, and any limitations.
High-deductible health plans offer a distinct pathway to health coverage, characterized by lower premiums and higher out-of-pocket deductibles. For individuals who are generally healthy, financially disciplined, and keen on leveraging the tax advantages of Health Savings Accounts, HDHPs can be a financially savvy choice. However, a thorough understanding of one’s personal health needs and financial readiness is paramount to ensure that the potential savings do not come at the cost of delayed or forgone essential medical care. By carefully considering all aspects, individuals can make an informed decision that best aligns with their unique circumstances and healthcare objectives.