
Understanding the nuances between Individual Retirement Arrangements (IRAs) and 401(k) plans is fundamental for anyone looking to effectively plan for their future financial security. Both are powerful retirement savings vehicles, but they differ significantly in their structure, contribution limits, investment options, and tax treatments. Navigating these distinctions empowers individuals to make informed decisions that best align with their personal financial goals and circumstances. This exploration will delve into the core differences, highlighting their individual strengths and how they can be strategically employed in a comprehensive retirement savings strategy.
The Foundation: Defining IRAs and 401(k)s
At their core, both IRAs and 401(k)s are tax-advantaged accounts designed to help individuals save for retirement. The primary benefit of both is the deferral of taxes on investment growth, allowing savings to compound over time without the immediate drag of annual taxation. However, the way these accounts are established, managed, and the specific rules governing them lead to their distinct characteristics.
Individual Retirement Arrangements (IRAs)
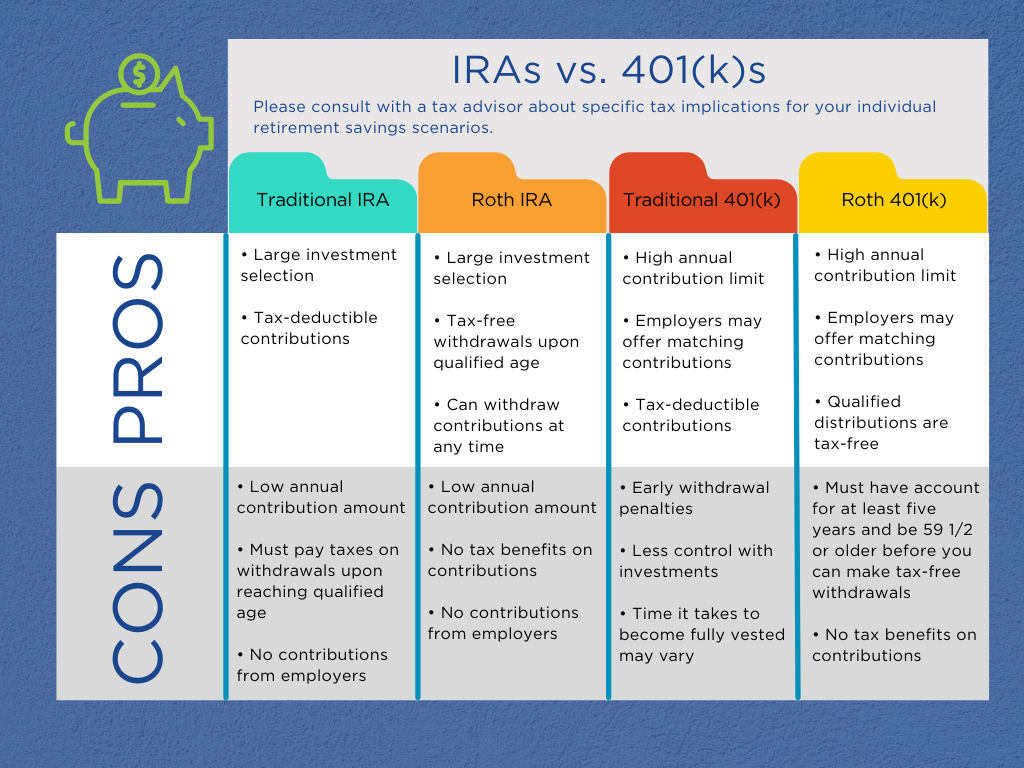
An IRA is an individual account established by a person, not tied to an employer. This means that individuals can open and manage an IRA independently, regardless of whether their employer offers a retirement plan. There are two main types of IRAs: Traditional IRAs and Roth IRAs, each with different tax implications during contribution and withdrawal phases.
- Traditional IRA: Contributions to a Traditional IRA may be tax-deductible in the year they are made, depending on income level and whether the individual is covered by a retirement plan at work. Earnings grow tax-deferred, meaning taxes are not paid on the investment gains until withdrawal in retirement. Withdrawals in retirement are taxed as ordinary income.
- Roth IRA: Contributions to a Roth IRA are made with after-tax dollars, meaning they are not tax-deductible in the year of contribution. However, qualified withdrawals in retirement are tax-free, including both contributions and earnings. This offers significant tax diversification and can be particularly advantageous for individuals who expect to be in a higher tax bracket in retirement than they are currently.
401(k) Plans
A 401(k) is an employer-sponsored retirement savings plan. It allows employees to contribute a portion of their paycheck to a retirement account, often with the employer offering a matching contribution. This employer match is essentially free money, significantly boosting an individual’s savings. Like IRAs, 401(k)s offer tax advantages, with contributions typically made on a pre-tax basis, reducing current taxable income.
- Traditional 401(k): Contributions are made pre-tax, lowering your current taxable income. Earnings grow tax-deferred, and withdrawals in retirement are taxed as ordinary income.
- Roth 401(k): Some employers offer a Roth 401(k) option. Contributions are made with after-tax dollars, and qualified withdrawals in retirement are tax-free. This option is becoming increasingly popular, providing a Roth-style benefit within an employer-sponsored plan.
Key Differences in Structure and Accessibility
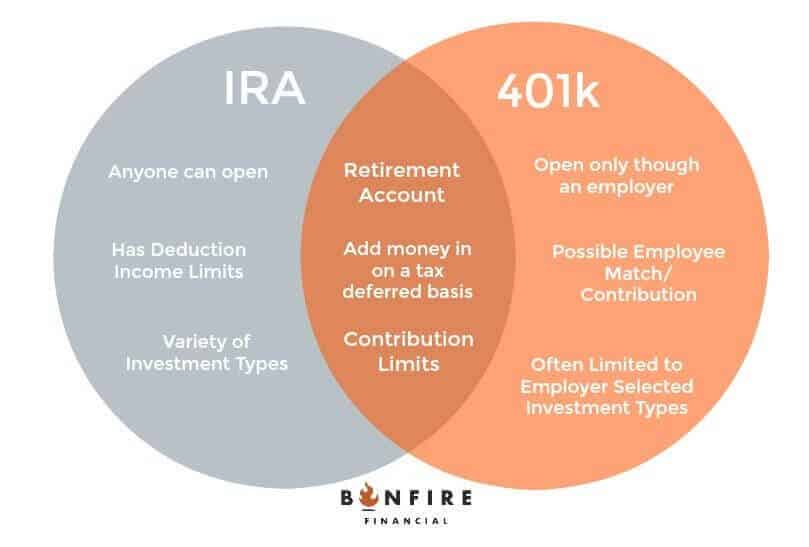
The most significant divergence between IRAs and 401(k)s lies in their origin and accessibility. An IRA is a personal financial tool, available to virtually anyone with earned income, whereas a 401(k) is a benefit provided by an employer. This fundamental difference dictates who can open them, how they are managed, and the range of investment choices available.
Employer Sponsorship vs. Individual Initiative
- 401(k)s: These plans are established and administered by employers. Employees must be eligible to participate based on their employer’s plan rules, which often include a vesting schedule for employer contributions. The investment options are curated and limited by the employer’s chosen plan administrator.
- IRAs: Individuals establish IRAs directly with financial institutions such as brokerage firms, banks, or mutual fund companies. Anyone with earned income is generally eligible to open an IRA, irrespective of their employment status or whether their employer offers a retirement plan. This independence offers a far broader spectrum of investment choices.
Investment Options and Control
- 401(k)s: Investment choices within a 401(k) plan are typically limited to a menu of mutual funds selected by the employer. While these options are usually diversified and professionally managed, they may not always perfectly align with an individual’s specific investment preferences or risk tolerance. The employer’s plan administrator makes these selections.
- IRAs: With an IRA, individuals have almost unlimited investment freedom. They can invest in a vast array of stocks, bonds, mutual funds, exchange-traded funds (ETFs), and other securities offered by their chosen financial institution. This autonomy allows for highly personalized portfolio construction, catering to individual investment strategies and goals.
Contribution Limits and Catch-Up Provisions
A crucial distinction that impacts how much one can save annually is the difference in contribution limits. 401(k) plans generally have much higher annual contribution limits than IRAs, reflecting their design as a primary retirement savings vehicle for employees.
Annual Contribution Limits
- 401(k)s: For 2023, the employee contribution limit for a 401(k) plan is $22,500. For individuals aged 50 and over, there is an additional catch-up contribution of $7,500, bringing the total to $30,000. These limits are set by the IRS and are subject to change annually.
- IRAs: For 2023, the annual contribution limit for both Traditional and Roth IRAs is $6,500. Individuals aged 50 and over can make a catch-up contribution of $1,000, bringing their total to $7,500. These limits are considerably lower than those for 401(k)s, making it more challenging to save a substantial portion of one’s income solely through an IRA.
Employer Contributions
A significant advantage of 401(k) plans is the potential for employer matching contributions. Many employers offer to match a percentage of an employee’s contributions, which can significantly accelerate retirement savings growth. For example, an employer might match 50% of an employee’s contributions up to 6% of their salary. These matching contributions are separate from the employee’s own contribution limit and do not count towards the $22,500 (or $30,000) limit. IRAs do not have employer contributions.
Tax Treatment: A Deeper Dive
While both IRAs and 401(k)s offer tax advantages, the timing and nature of these benefits can vary, especially between Traditional and Roth versions of each.
Pre-Tax vs. After-Tax Contributions
- Traditional 401(k) and Traditional IRA: Contributions are generally made on a pre-tax basis. This means the money is deducted from your gross income before taxes are calculated, reducing your current taxable income. The trade-off is that withdrawals in retirement will be taxed as ordinary income.
- Roth 401(k) and Roth IRA: Contributions are made with after-tax dollars. You pay taxes on the money now, but qualified withdrawals in retirement are tax-free. This can be a strategic advantage if you anticipate being in a higher tax bracket in retirement.
Tax-Deferred Growth
Both Traditional and Roth IRAs, as well as Traditional and Roth 401(k)s, benefit from tax-deferred or tax-free growth. This means that any interest, dividends, or capital gains earned within the account are not taxed annually. This allows investments to compound more effectively over time, as earnings on earnings are reinvested.
Withdrawal Rules and Penalties
Both account types have rules regarding withdrawals before retirement age. Generally, withdrawals made before age 59½ are subject to a 10% early withdrawal penalty, in addition to ordinary income taxes (for Traditional accounts). There are some exceptions, such as for qualified higher education expenses, first-time home purchases (for IRAs), or unforeseen financial hardship. However, the specific exceptions can differ between IRAs and 401(k)s. Required Minimum Distributions (RMDs) also apply to Traditional IRAs and 401(k)s, typically starting at age 73 (as of current legislation), requiring account holders to withdraw a minimum amount annually. Roth IRAs do not have RMDs for the original owner.
Making the Right Choice: Leveraging Both
Understanding the differences between IRAs and 401(k)s is not about choosing one over the other, but rather about recognizing how they can complement each other in a robust retirement savings strategy.
Maximizing Employer Match First
The golden rule for anyone with access to a 401(k) plan is to contribute enough to receive the full employer match. This is essentially a guaranteed return on your investment that you cannot get anywhere else. Once the match is secured, individuals can then consider directing additional savings towards an IRA if it offers more appealing investment options or tax advantages that better suit their situation.
Diversifying Tax Treatment
Having both pre-tax (Traditional) and after-tax (Roth) accounts can provide valuable tax diversification in retirement. This flexibility allows individuals to manage their tax liability in retirement by drawing from different account types depending on their income needs and prevailing tax laws.

When to Prioritize an IRA
If an employer’s 401(k) plan has high fees or a limited selection of investment options, an individual might choose to contribute enough to get the employer match and then prioritize maxing out an IRA, especially if they desire more control over their investments or a Roth option. Conversely, if an IRA’s contribution limit is too low to meet significant savings goals, a 401(k) becomes essential.
In conclusion, while both IRAs and 401(k)s serve the critical purpose of enabling tax-advantaged retirement savings, their operational frameworks, contribution capacities, and investment freedoms are distinct. By grasping these differences, individuals can strategically deploy both tools to build a secure and prosperous financial future.