
The term “bank code” can be multifaceted, especially when discussing its relevance within the broader technological landscape that supports various industries. While not directly a component of a drone’s physical construction or flight mechanics, understanding bank codes is crucial for the financial infrastructure that underpins drone-related businesses, research, and development. In the context of technology and innovation, especially those areas that involve significant investment and complex operational models like drone technology, financial codes play a silent but indispensable role.
The Financial Foundation of Drone Technology
The burgeoning drone industry, encompassing everything from sophisticated commercial UAVs for industrial inspection to high-speed racing drones and advanced aerial imaging platforms, relies heavily on a robust financial ecosystem. This ecosystem facilitates everything from the procurement of components and advanced manufacturing processes to the funding of research and development for cutting-edge features like AI-powered autonomous flight, advanced remote sensing, and sophisticated mapping solutions. Within this ecosystem, various financial codes act as identifiers, ensuring that transactions are processed accurately and efficiently.

Understanding the SWIFT Code
One of the most prominent “bank codes” that has significant implications for international transactions within any technology sector, including drones, is the SWIFT code. This stands for Society for Worldwide Interbank Financial Telecommunication. It’s an international messaging network used by banks and financial institutions to send and receive information, such as money transfer instructions, in a secure and standardized way.
What a SWIFT Code Represents
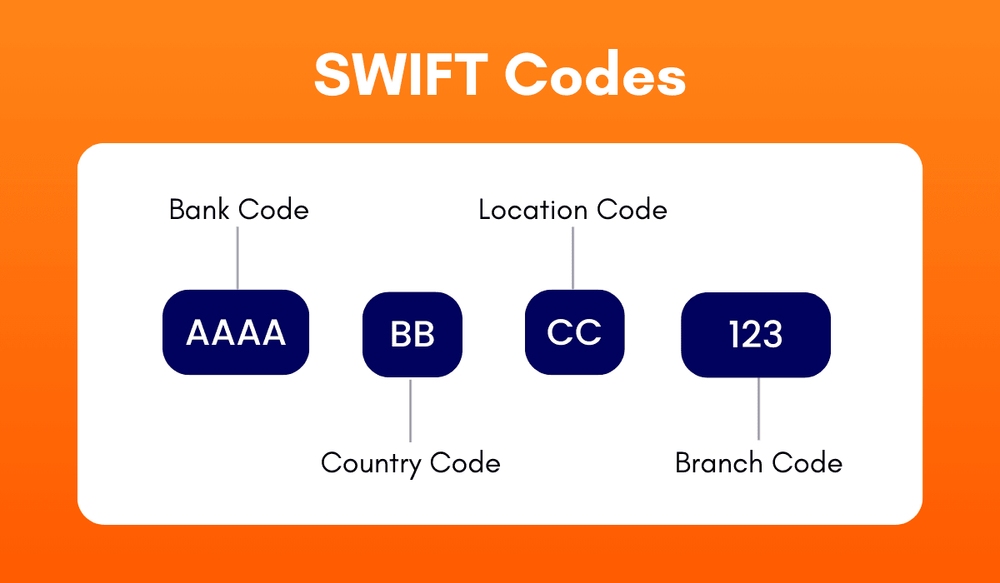
A SWIFT code, also known as a Bank Identifier Code (BIC), is an 8 or 11-character code that identifies a specific bank and country. It’s not a bank account number but rather an address for a financial institution. The structure of a SWIFT code is as follows:
- AAAA: The first four letters represent the bank’s name (e.g., BGLA for Bank of America).
- BB: The next two letters are the country code (e.g., US for the United States, GB for the United Kingdom).
- CC: The following two characters (letters or numbers) represent the location of the bank’s head office or main branch.
- DDD (Optional): The last three digits are optional and refer to a specific branch of the bank. If this part is omitted, it refers to the primary office of the bank.
Relevance to Drone Innovation and Business
For companies involved in the drone industry, whether they are manufacturing advanced sensors for obstacle avoidance, developing AI algorithms for autonomous flight, or producing high-end gimbal cameras for aerial filmmaking, international trade is often a reality. Manufacturers might source components from overseas, or companies might sell their finished drone products to international markets. In such scenarios, SWIFT codes are essential for:
- International Payments: When a drone manufacturer in Germany needs to pay a supplier of specialized gyroscopes in Japan, the SWIFT code of the Japanese supplier’s bank will be required to ensure the funds reach the correct institution.
- Cross-Border Investments: Venture capital firms or angel investors looking to fund promising drone startups might be located in different countries. SWIFT codes are vital for transferring investment capital.
- Supply Chain Management: The global nature of the drone supply chain means that components, software licenses, and specialized services are often procured internationally. Accurate bank codes are necessary for seamless financial operations.
- Global Expansion: Drone service providers aiming to expand their operations internationally will need to establish business accounts in foreign countries, requiring the use of local bank codes for transactions.
The ABA Routing Number: A Domestic Identifier
While SWIFT codes are primarily for international transactions, within the United States, the American Bankers Association (ABA) Routing Transit Number (RTN), commonly known as the ABA Routing Number, serves a similar purpose for domestic financial operations. This nine-digit number identifies a specific financial institution within the United States.
Structure and Function of ABA Routing Numbers
The ABA Routing Number is structured to indicate geographical regions and the Federal Reserve Bank district where the financial institution is located. Its primary function is to facilitate the clearing and settlement of checks and electronic payments within the U.S. banking system.
Impact on U.S.-Based Drone Operations
For drone-related businesses operating solely within the U.S., or for those receiving payments from U.S. customers, the ABA Routing Number is paramount.
- Domestic Payments and Payroll: When a U.S. drone company pays its employees, its suppliers for domestic components, or receives payments from U.S. clients for aerial mapping or inspection services, the ABA Routing Number is a key piece of information for initiating direct deposits, wire transfers, and check processing.
- Funding and Loans: Securing loans or investment from U.S. financial institutions for drone manufacturing facilities or R&D projects will necessitate the provision of accurate ABA Routing Numbers for the relevant accounts.
- E-commerce and Payment Gateways: When selling drones or drone services online within the U.S., payment processors will utilize ABA Routing Numbers to move funds between customer accounts and business accounts.
Other Bank Identifiers and Their Significance
Beyond SWIFT and ABA Routing Numbers, various other bank identifiers exist globally, each serving specific functions within national or regional financial systems. While the specific terminology might differ, the underlying principle of identifying a financial institution for transaction purposes remains constant.
- Sort Codes (UK): In the United Kingdom, a sort code is a six-digit number used to route money transfers between banks within the UK. It identifies both the bank and the specific branch.
- IBAN (International Bank Account Number): While not strictly a “bank code” in the same vein as SWIFT or ABA, the IBAN is an internationally agreed-upon system of identifying bank accounts across national borders. It contains country codes, bank codes, and account numbers, making international transfers more streamlined and less prone to errors. For drone companies operating internationally, ensuring correct IBANs are used for transactions is as important as the SWIFT code.
- National Clearing Codes: Many countries have their own national systems for identifying banks and routing transactions domestically. For instance, Canadian banks use transit numbers, and Australian banks use BSB (Bank, State, Branch) numbers.
The Interplay Between Bank Codes and Technological Advancement
The intricate web of financial identifiers, such as bank codes, forms the invisible backbone of modern commerce and innovation. For the drone industry, characterized by rapid technological advancements and a globalized marketplace, this financial infrastructure is particularly vital.
Facilitating R&D Investment
Developing next-generation drone technology requires substantial investment. This can come from government grants, private equity, venture capital, or corporate partnerships. Regardless of the source, the transfer of these funds across borders or between institutions relies on accurate bank codes. Innovations in AI-driven autonomous flight, advanced sensor fusion for enhanced navigation, or the creation of more efficient power systems for extended flight times are all contingent on a functioning financial system that can support these ambitious projects.
Enabling Global Supply Chains
The components that make up a sophisticated drone – from the flight controller and GPS modules to the high-resolution cameras and advanced battery management systems – are often sourced from manufacturers worldwide. A company producing advanced FPV systems might source specialized lenses from one country, microprocessors from another, and assembly might occur in a third. Without the ability to reliably and efficiently transfer funds internationally, these complex and often cost-effective supply chains would be impossible to manage. Bank codes are the keys that unlock these global financial flows.
Supporting the Growth of Drone Services
The application of drones is expanding rapidly into sectors such as agriculture, construction, energy, and public safety. Companies offering drone-based inspection services, aerial surveying, or delivery solutions need to manage their finances effectively, both domestically and internationally. If a drone inspection company operates in multiple countries or relies on foreign software or hardware providers, understanding and correctly using various bank codes is a fundamental business requirement.

The Role in E-commerce and Digital Platforms
The sale of drones, accessories, and related services often occurs through online platforms. These platforms, whether they are global marketplaces or specialized e-commerce sites, rely on secure and efficient payment processing. This processing, in turn, depends on the accurate identification of banks and accounts using codes like ABA Routing Numbers for domestic U.S. transactions and SWIFT codes for international ones. The seamless flow of money allows businesses to grow and consumers to access the latest drone technology.
In conclusion, while “bank code” might not immediately evoke images of flight paths or gimbal stabilization, it represents a critical element of the financial infrastructure that enables the entire drone ecosystem to thrive. From funding cutting-edge research and development to managing global supply chains and facilitating everyday transactions, understanding and correctly utilizing these financial identifiers is essential for any entity operating within the dynamic and innovative world of drone technology.