
The Foundation of Algorithmic Strategy Validation
Backtesting trading is a critical analytical process used by traders and quantitative analysts to evaluate the viability and profitability of a trading strategy using historical data. In essence, it involves applying a set of trading rules to past market conditions and observing the hypothetical outcomes. This rigorous examination provides a simulated track record, offering invaluable insights into how a strategy might have performed in real-world scenarios, thereby informing future investment decisions and risk management protocols.
Defining Backtesting
At its core, backtesting is a form of simulation. Instead of deploying capital with an untested strategy, market participants can create a hypothetical portfolio and execute trades based on their defined rules against years, or even decades, of historical price and volume data. This allows for an objective assessment of the strategy’s potential before risking actual funds. It moves strategy development from speculative theory to evidence-based analysis, enabling refinement and optimization based on tangible, simulated results.
Historical Data as the Proving Ground
The quality and breadth of historical data are paramount in backtesting. This data typically includes not just price (open, high, low, close) and volume, but can also extend to tick data, order book data, fundamental economic indicators, news sentiment, and more, depending on the complexity of the strategy. By subjecting a strategy to diverse market conditions—bull markets, bear markets, volatile periods, and calm stretches—analysts can gauge its resilience and adaptability. Without robust, high-quality historical data, the backtesting process risks yielding misleading or irrelevant results, undermining the entire exercise.
Key Components and Methodologies
Effective backtesting is not merely about running a script; it’s a methodical process involving several critical steps and considerations to ensure the integrity and reliability of the results.
Data Selection and Quality
The first and most crucial step is selecting appropriate historical data. This involves choosing a sufficiently long period to capture various market cycles and ensuring the data is clean, accurate, and free from errors or biases. Data should ideally reflect the actual conditions under which the strategy would be deployed, including considerations for survivor bias (e.g., excluding delisted stocks from a universe) and look-ahead bias (e.g., using data that would not have been available at the time of the hypothetical trade decision). High-frequency strategies, for instance, demand tick-level data, while longer-term position strategies might suffice with daily or weekly closes.
Strategy Formulation
Before backtesting, the trading strategy must be meticulously defined. This includes explicit entry and exit rules, position sizing logic, stop-loss and take-profit levels, and any other parameters that govern trade execution. The rules must be unambiguous and quantifiable, allowing for programmatic implementation. A clear understanding of the strategy’s underlying rationale—whether it’s trend-following, mean-reversion, arbitrage, or event-driven—is essential for interpreting the results and identifying areas for improvement.
Simulation and Performance Metrics
Once the data and strategy are ready, the simulation engine applies the strategy’s rules chronologically to the historical data. As trades are hypothetically executed, the system tracks a myriad of performance metrics. Key metrics include:
- Net Profit/Loss: The total hypothetical gain or deficit.
- Return on Investment (ROI): The profit as a percentage of initial capital.
- Drawdown: The peak-to-trough decline in portfolio value during a specific period. Maximum drawdown indicates the worst historical loss.
- Sharpe Ratio: Measures risk-adjusted return, comparing excess return to volatility.
- Sortino Ratio: Similar to Sharpe, but focuses only on downside deviation (bad volatility).
- Win Rate: The percentage of profitable trades.
- Profit Factor: Total gross profit divided by total gross loss.
- Average Win/Loss: The average profit from winning trades versus the average loss from losing trades.
- Holding Period: The average duration a trade remains open.
These metrics collectively paint a comprehensive picture of the strategy’s hypothetical performance, risk profile, and efficiency.
Mitigating Common Pitfalls
Despite its utility, backtesting is not without its challenges. Overfitting is a significant concern, where a strategy is optimized too closely to past data, leading to exceptional backtested results but poor real-world performance. This often occurs when too many parameters are tweaked to fit historical noise. Another pitfall is look-ahead bias, where future information inadvertently influences past trading decisions. Transaction costs (commissions, slippage, bid-ask spread) are also frequently underestimated or omitted, leading to inflated net profits in simulations. Robust backtesting methodologies include techniques like out-of-sample testing, walk-forward analysis, and monte carlo simulations to address these issues and enhance the reliability of the results.

The Technological Edge in Modern Backtesting
The evolution of technology has profoundly transformed backtesting, making it more sophisticated, efficient, and accessible. Modern backtesting platforms leverage significant computational power and advanced algorithms.
Computational Power and Cloud Solutions
The sheer volume of data required for robust backtesting, especially for high-frequency or multi-asset strategies, necessitates substantial computing resources. Cloud computing platforms have revolutionized this aspect, providing scalable infrastructure that allows analysts to run complex simulations across vast datasets without the need for prohibitive local hardware investments. This accessibility empowers individual traders and smaller firms to conduct analyses previously limited to institutional players. Parallel processing and distributed computing further accelerate simulations, enabling rapid iteration and testing of numerous strategy variations.
Advanced Analytics and Machine Learning
The integration of advanced analytics and machine learning (ML) models has pushed the boundaries of backtesting. ML algorithms can be used to identify complex patterns in historical data that human intuition or traditional rule-based systems might miss. Strategies can be trained and validated using techniques like supervised learning for prediction or reinforcement learning for optimal decision-making. Backtesting provides the critical environment to validate these ML-driven strategies, assessing their robustness and generalization capabilities before deployment. This synergy between ML and backtesting allows for the development of adaptive and highly dynamic trading systems.
Automation and Continuous Improvement
Modern backtesting frameworks often integrate with automated trading systems. Once a strategy is backtested and deemed robust, it can be transitioned to live trading with a higher degree of confidence. Furthermore, automated backtesting pipelines can continuously monitor strategy performance against new incoming data, triggering alerts or initiating refinements if performance degrades. This continuous feedback loop facilitates an agile approach to strategy development, allowing for ongoing optimization and adaptation to evolving market dynamics without constant manual intervention.
Beyond Profit: Risk Management and Robustness
While profitability is a primary goal, a truly effective backtest extends beyond just assessing returns. It critically evaluates the risks inherent in a strategy and its robustness under various market conditions.
Stress Testing and Scenario Analysis
A backtest should ideally include stress testing, where the strategy is run against periods of extreme market stress, such as major financial crises, market crashes, or significant geopolitical events. This helps reveal how the strategy would perform during adverse conditions, highlighting its resilience or vulnerability. Scenario analysis involves examining how the strategy would react to specific hypothetical future events, even if they haven’t occurred historically in the exact same form. These techniques are crucial for understanding potential tail risks and preparing for unforeseen market movements.
Understanding Drawdowns and Volatility
A strategy might show impressive overall returns but experience severe drawdowns along the way. Backtesting rigorously quantifies these drawdowns, providing metrics like maximum drawdown, average drawdown, and drawdown duration. Understanding these figures is vital for assessing the psychological and capital requirements of a strategy. A strategy with a high potential return but unbearable drawdowns might not be practically tradable. Similarly, volatility measures (e.g., standard deviation of returns) help quantify the risk associated with the strategy’s profit generation, ensuring that returns are not merely a result of excessive risk-taking.
The Role of Backtesting in Innovation
Backtesting is not merely a validation tool; it is a catalyst for innovation within the financial technology and trading domains.
Iterative Development and Refinement
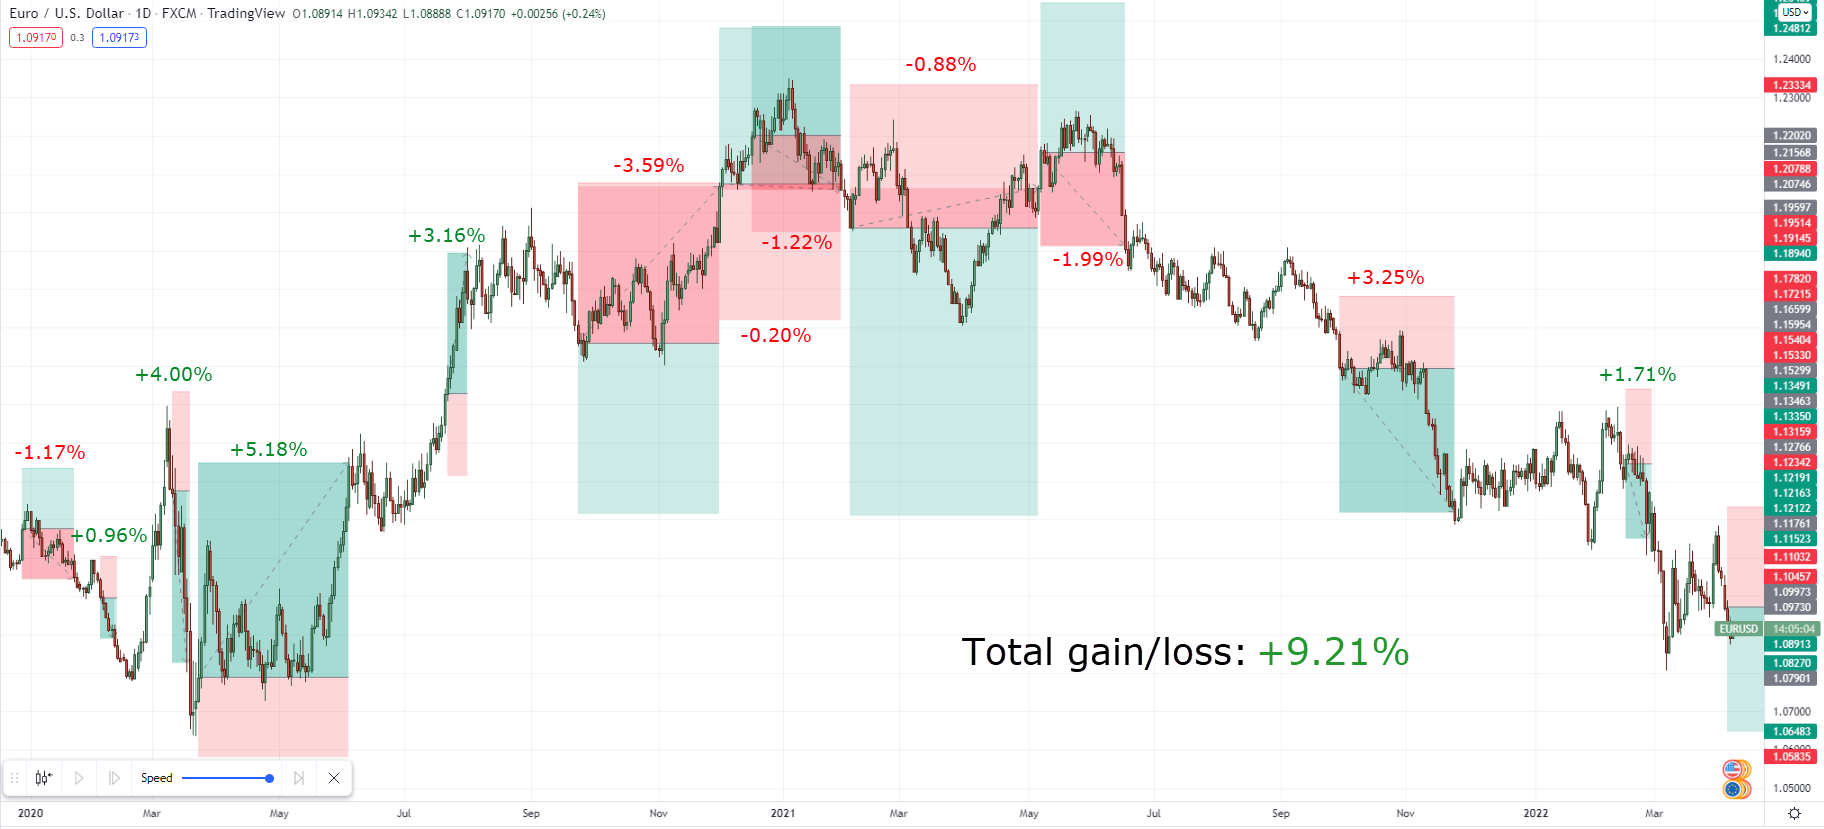
The ability to quickly test and refine ideas against historical data fosters an iterative development cycle. Traders and quantitative researchers can rapidly prototype new concepts, identify weaknesses, make adjustments, and re-test, accelerating the process of strategy discovery. This iterative nature allows for constant experimentation, leading to incremental improvements and the potential for breakthroughs in trading methodology. It turns the complex art of trading into a more systematic and scientific endeavor.
Fostering New Trading Paradigms
By providing a quantifiable framework for evaluating novel approaches, backtesting encourages the exploration of new trading paradigms. Whether it’s the application of advanced econometric models, the integration of alternative data sources (like satellite imagery or social media sentiment), or the development of entirely new market prediction algorithms, backtesting offers the necessary empirical foundation. It allows innovators to demonstrate the historical efficacy of their concepts, paving the way for the adoption of more sophisticated and data-driven trading strategies that continuously push the boundaries of financial markets. In this sense, backtesting is an indispensable engine of progress, transforming theoretical insights into actionable, high-performance trading solutions.