
The rapid proliferation of drones, from recreational quadcopters to advanced industrial Unmanned Aerial Vehicles (UAVs), has revolutionized countless industries and hobbies. Yet, alongside the benefits of aerial perspectives and operational efficiencies, comes an inherent set of risks. Understanding these risks, and more importantly, how to mitigate them, is paramount for any drone operator. Central to this risk mitigation strategy is third-party insurance coverage, a vital safeguard often misunderstood or overlooked by even experienced pilots.
Demystifying Third-Party Drone Insurance
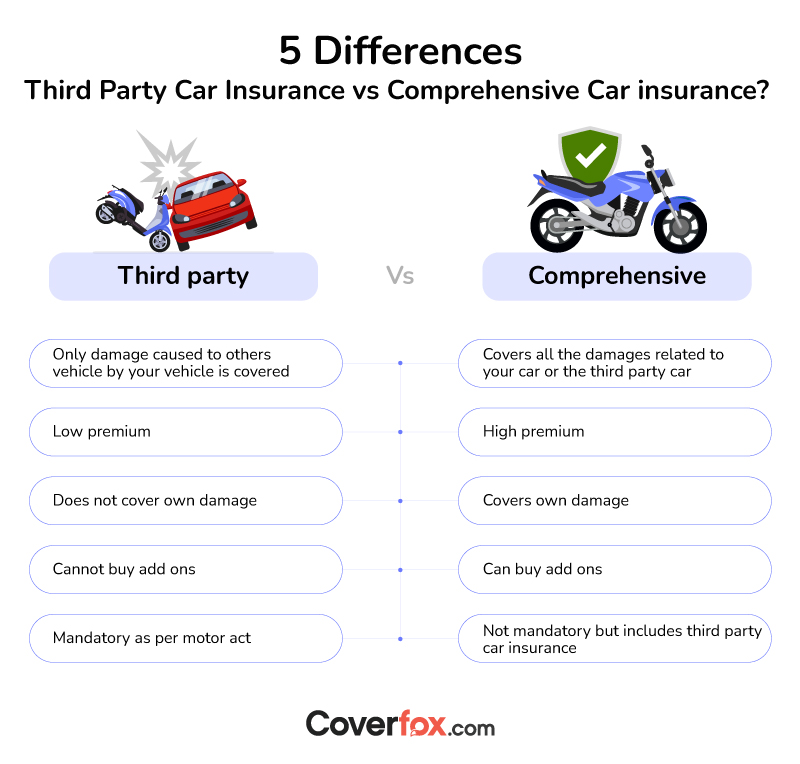
At its core, third-party insurance for drones, often referred to as third-party liability insurance, is designed to protect the drone operator from financial liabilities arising from damage or injury caused to other people or their property. It is distinct from coverage that protects the drone itself (hull damage) or its specialized equipment. The “third party” refers to anyone other than the policyholder (the drone operator) and the insurance company.

Imagine a scenario where a drone, due to a malfunction, pilot error, or unforeseen environmental factor, crashes into a bystander’s vehicle, shatters a window on a commercial building, or worse, causes personal injury to an innocent pedestrian. Without adequate third-party coverage, the financial burden of repairs, medical bills, legal fees, and potential compensation claims would fall squarely on the drone operator. This could amount to tens of thousands, hundreds of thousands, or even millions of dollars, depending on the severity of the incident.
This form of insurance is critical because drones, even small consumer models, possess kinetic energy that can cause significant damage upon impact. They operate in shared airspace, often over or near populated areas, and their operational environment is dynamic and unpredictable. From a hobbyist flying their first FPV drone in a park to a professional UAV pilot conducting complex industrial inspections, the potential for an unforeseen incident with a third party is a constant.
The Imperative for Drone Operators: Why Third-Party Liability is Essential
The necessity of third-party drone insurance extends beyond mere financial protection; it is often a legal requirement, a professional mandate, and a cornerstone of responsible operation. The consequences of not having this coverage can be severe, impacting not only personal finances but also reputation and legal standing.
Mitigating Financial Catastrophe
The most immediate and obvious reason for third-party coverage is the protection it offers against crippling financial losses. A simple accident, such as a drone impacting a car, could easily lead to repair costs exceeding the value of the drone itself. More complex incidents, involving commercial property damage or personal injury, can result in lawsuits with astronomical settlements. Third-party insurance acts as a buffer, ensuring that these costs are borne by the insurer, up to the policy’s limits, rather than draining an operator’s life savings. This is particularly relevant for professional drone pilots who operate more frequently and often in higher-risk environments, such as construction sites, public events, or crowded urban settings.
Legal Compliance and Regulatory Mandates
Many national and regional aviation authorities now mandate third-party liability insurance for certain drone operations, especially commercial flights. For instance, regulations in some countries require specific liability coverage amounts before a commercial drone operation permit is granted. Even for recreational pilots, there might be stipulations in local bylaws or park regulations requiring insurance. Operating a drone without the legally required insurance can lead to hefty fines, confiscation of equipment, and even criminal charges, irrespective of whether an accident occurs. Staying abreast of these evolving regulations is crucial for all drone pilots, ensuring continuous compliance.
Professionalism and Client Trust
For commercial drone service providers, having robust third-party liability insurance isn’t just a legal requirement; it’s a mark of professionalism and a prerequisite for securing contracts. Clients, whether in real estate, construction, agriculture, or media production, will often request proof of insurance before engaging a drone operator. This demonstrates that the operator is responsible, prepared for potential contingencies, and can protect the client from indirect liabilities should an incident occur during a contracted job. Without it, opportunities for lucrative contracts can be severely limited. Insurance builds trust, assuring clients that their projects and property are safeguarded.
Peace of Mind
Beyond the tangible benefits, third-party drone insurance provides invaluable peace of mind. Knowing that one is protected against unexpected liabilities allows pilots to focus on safe and effective drone operation without the constant worry of potential financial ruin from an unforeseen accident. This psychological benefit enhances concentration and decision-making during flights, indirectly contributing to safer operations.
Components and Types of Third-Party Drone Insurance Policies
Third-party drone insurance isn’t a one-size-fits-all product. Policies vary widely based on the operator’s needs, the type of drone, and the nature of its use. Understanding these variations is key to selecting appropriate coverage.
Coverage Limits and Deductibles
Every third-party policy comes with a maximum payout limit, often ranging from hundreds of thousands to several millions of dollars. The appropriate limit depends on the perceived risk of operations. For a hobbyist flying a micro drone in a secluded area, a lower limit might suffice. For a commercial operator flying a heavy-lift UAV over a film set, a much higher limit is indispensable. Policies also typically include a deductible, which is the amount the policyholder must pay out-of-pocket before the insurance coverage kicks in. A higher deductible usually translates to lower premiums.
Types of Policies
- Annual Policies: These provide continuous coverage for a full year, ideal for commercial operators or active hobbyists who fly frequently. They often cover multiple drones and pilots under a single policy, making them cost-effective for businesses with a fleet. Annual policies offer broad coverage and eliminate the need to secure insurance before each flight.
- On-Demand or Per-Flight Policies: A newer and increasingly popular option, particularly for hobbyists or commercial operators with infrequent flights. These policies allow operators to purchase coverage for specific durations (e.g., an hour, a day, a week) directly through a mobile app or online platform. This offers flexibility and can be more economical for occasional use, as operators only pay for coverage when they need it.
- Commercial Drone Insurance: Specifically tailored for professional operations, these policies are more comprehensive. They often include higher liability limits, cover specific commercial applications (e.g., mapping, inspection, cinematography), and may extend to cover specific equipment on the drone (payloads like high-end cameras or LiDAR sensors) and sometimes even privacy liabilities.
- Hobbyist/Recreational Drone Insurance: Generally less extensive than commercial policies, these are designed for non-commercial flight activities. While often not legally mandatory, they are highly recommended for responsible hobbyists. Some homeowner’s insurance policies might offer limited drone liability, but it’s crucial to verify the specifics, as drone-related incidents are often excluded or have very low limits. Dedicated drone liability insurance is typically a safer bet.
Factors Influencing Your Drone Insurance Premium
Several variables come into play when insurance providers calculate premiums for third-party drone coverage. Understanding these factors can help operators secure the most appropriate and cost-effective policy.
Drone Type and Value
Larger, heavier drones (e.g., industrial UAVs, heavy-lift cinematic platforms) generally pose a greater risk of causing significant damage or injury compared to smaller, lighter consumer drones or micro drones. Consequently, premiums for operating heavier aircraft are typically higher. The value of the drone itself can also play a minor role, especially if the policy bundles hull coverage, but for pure third-party liability, the potential for damage to others is the primary concern.
Operational Environment and Usage
Where and how a drone is flown significantly impacts risk. Flying in densely populated urban areas, near airports, over public events, or within restricted airspace presents a higher risk profile than flying in an open field. Commercial operations, particularly those involving complex maneuvers or hazardous environments (e.g., inspecting active power lines), will naturally incur higher premiums than recreational flights. The frequency of flights also plays a role, with more active pilots generally paying more for annual policies.
Pilot Experience and Training
Experienced pilots with a proven track record of safe flying, along with relevant certifications (e.g., Part 107 in the US, A2 CofC in the UK), are often viewed as lower risk by insurers. Participation in recognized drone safety training programs can also sometimes lead to reduced premiums. Insurers recognize that well-trained pilots are less likely to commit errors that lead to incidents.
Coverage Limits and Deductibles Chosen
As mentioned earlier, higher liability limits naturally result in higher premiums. Conversely, choosing a higher deductible can reduce the premium cost, albeit at the expense of greater out-of-pocket exposure in the event of a claim. Striking the right balance between coverage and cost is a crucial decision for every drone operator.
Navigating the Evolving Landscape of Drone Regulations and Insurance
The drone industry is still relatively nascent, and both its technological capabilities and regulatory frameworks are in constant flux. Drone insurance, particularly third-party liability, must evolve in tandem to remain relevant and effective.
Staying Compliant with Regulatory Changes
Drone regulations are continually updated, expanding to cover new types of operations, specific drone classes, and airspace classifications. These changes often impact insurance requirements. For example, the introduction of “Specific” category operations in Europe or advanced operations in the US may necessitate more specialized or higher-limit insurance policies. Operators must make it a priority to stay informed about these regulatory shifts, not only to ensure legal compliance but also to adjust their insurance coverage accordingly. Industry associations, civil aviation authorities, and reputable drone news outlets are excellent resources for tracking these changes.
The Impact of Emerging Technologies
As drones become more autonomous, incorporate advanced AI, and expand into complex operations like package delivery or urban air mobility, the scope and nature of third-party liability will inevitably broaden. Issues such as cyber liability (e.g., a drone’s system being hacked and causing damage), privacy infringements from advanced surveillance capabilities, or liability for fully autonomous flight decisions will become increasingly relevant. Insurance providers are already working to develop policies that address these nuanced and futuristic risks.

The Role of Data and Telemetry
The rich telemetry data collected by modern drones can play a significant role in insurance claims. Flight logs, GPS data, and sensor readings can provide crucial evidence regarding the cause of an incident, helping to determine liability and expedite claims processing. Some insurers may even offer discounts to operators who utilize advanced flight planning software or maintain meticulous flight records, signifying a commitment to safe practices.
In conclusion, third-party insurance coverage is not merely an optional add-on for drone operators; it is a fundamental aspect of responsible and sustainable drone use. Whether a recreational enthusiast enjoying aerial photography or a commercial enterprise leveraging UAV technology, understanding, acquiring, and maintaining appropriate third-party liability insurance is indispensable for protecting oneself, others, and the continued growth of the drone industry.